


EN
Tsugami China (01651) Lean management improves quality and efficiency, reports performance to a new high, with outstanding structural highlights and increased contributions
Core financial data has reached a record high across the board. This is the strongest value signal released by Tsugami Machine Tool China (01651)'s latest fiscal year 2027 mid-term report.
According to Tsugami China's financial report, in the first half of fiscal year 2027, the company achieved revenue of 3.02 billion yuan, up 20.9% year on year; gross profit increased 26.6% year on year to 1.09 billion yuan, corresponding gross profit margin of 36.2%, up 1.6 percentage points year on year; net profit increased 32.2% year on year to 660 million yuan, corresponding net interest rate of 22.0%, up 1.9 percentage points year on year. Both business scale and profit indicators were the best performance in history.
Zhitong Finance notes that while Tsugami China's strong performance is being realized, companies at the capital market level are also making positive progress. On September 7, Tsugami China was officially included in the Hang Seng Composite Index and entered the scope of the Hong Kong Stock Exchange. For Tsugami China, the invisible champion of the manufacturing industry, which has both growth elasticity and sustainability, this financial report once again confirms the high visibility and high elasticity of its growth; while the inclusion of Hong Kong stocks means an effective expansion of the investor base, the company's value discovery will be more efficient and thorough.
Furthermore, at the level of returns to shareholders, Tsugami China continues the tradition of actively giving back to shareholders. According to the interim report, Tsugami China plans to pay an interim dividend of HK$0.90 per share, while the dividend for the same period last year was HK$0.6 per share. It can be seen that as profits continue to reach new highs, Tsugami China is also increasing its dividend efforts at the same time. Furthermore, Tsugami China also enhances shareholders' rights through active buybacks and cancellations. According to statistics, since the company went public, a total of 12.756 million shares have been repurchased and cancelled, consolidating shareholders' returns and enhancing the majority shareholders' sense of gain with the “dividend+repurchase” combo.
Profitability has reached the next level, and prominent structural highlights drive high-quality growth
Since this year, although the global macroeconomic situation continues to be complex, the domestic manufacturing industry has achieved steady and progressive performance under the combined effects of transformation and upgrading and the continued implementation of large-scale equipment renewal policies. Take the machine tool industry as an example. On the one hand, along with the restoration of corporate profits and inventory cycles, traditional demand such as general equipment remains stable; on the other hand, AI computing power infrastructure construction is driving the growth in demand for liquid cooling systems and high-speed optical communication, and emerging applications represented by AI liquid cooling are “taking over” at an accelerated pace, becoming an emerging increase with high certainty.
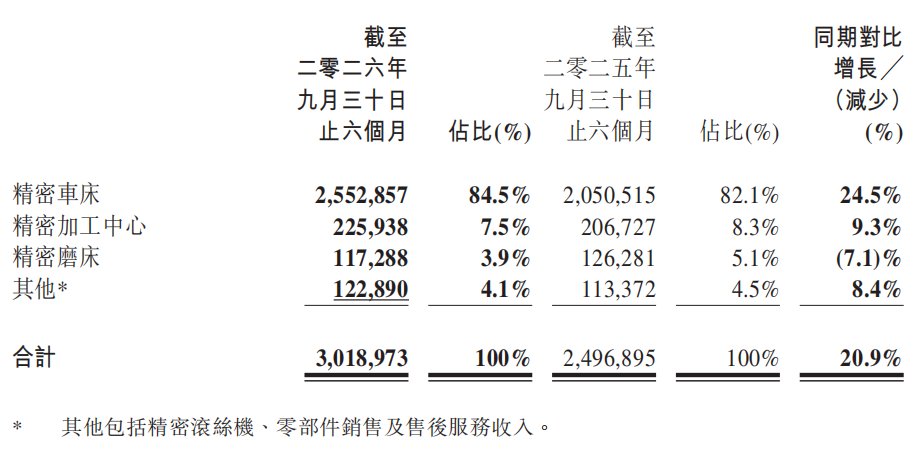
Tsugami's comprehensive upward breakthrough in China's core financial data is directly related to its accurate grasping of structural opportunities in the industry. During the reporting period, the revenue contributed by Tsugami China's precision lathes and precision machining centers increased by 24.5%, 9.3% to 2.55 billion yuan and 230 million yuan respectively, accounting for 84.5% and 7.5% of the corresponding revenue, respectively. Other businesses, including precision rolling machines, parts sales and after-sales service, also continued to grow, with revenue increasing 8.4% year-on-year to 120 million yuan. At the same time, since the second half of the previous fiscal year began, the automobile industry, which accounts for more than half of precision grinder orders, entered an adjustment cycle, and orders and shipments fluctuated due to falling demand. The revenue of precision grinders during the period was 120 million yuan, accounting for 3.9%.
Throughout the first half of the fiscal year, domestic and overseas sales of Tsugami Machine Tools showed a full blossom trend. Sales in China reached 2.77 billion yuan, up 18.2% year on year and 12.1% month on month, and domestic revenue continued to reach record highs. At the same time, thanks to the continued recovery in overseas demand, the company's overseas revenue rose to 250 million yuan during the period, which surged 62.3% and 15.3%, respectively, compared with the same period last month.
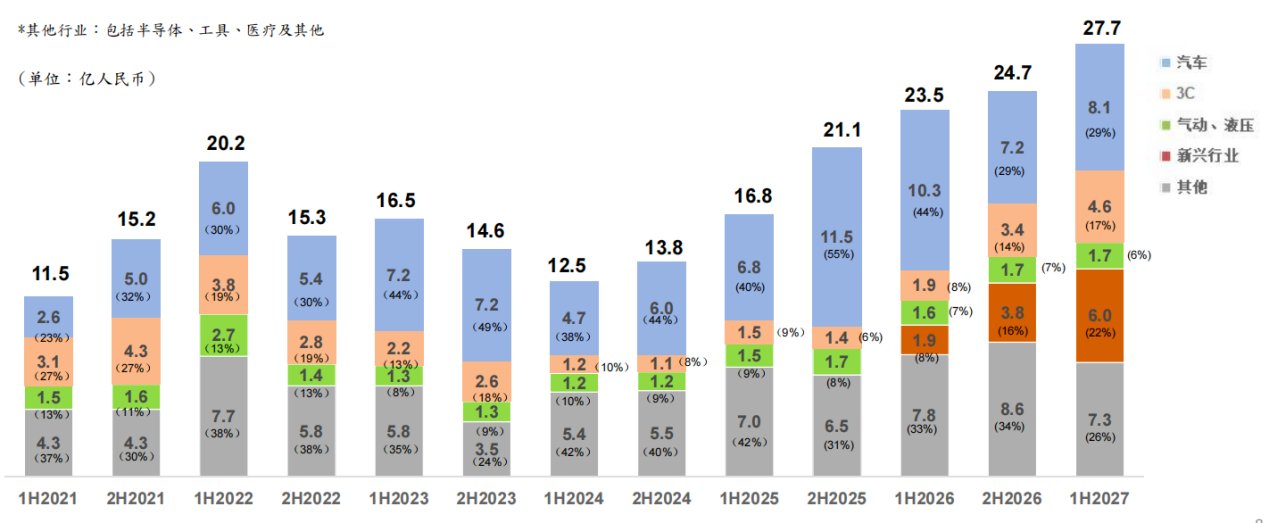
If you look at the distribution of downstream customers by dividing the industry, you can more clearly sense how Tsugami China is seizing structural opportunities and turning them into its own growth potential. According to the data, the company's revenue from emerging industries reached 600 million yuan during the period, which not only achieved a leap forward growth of 212% year over year, but also surged 55% month over month in the context of a high base. At this stage, in emerging scenarios such as AI liquid cooling, Tsugami China has formed a first-mover advantage with process barriers and delivery experience. Subsequently, with large-scale development of industry segments such as AI liquid cooling, optical modules, and humanoid robots, the contribution of emerging industries to the company's revenue is expected to rise further and become an important engine driving performance growth.
The 3C industry also saw a significant rise in prosperity. The first half of the fiscal year benefited from leading consumer electronics manufacturers restarting a strong new product cycle, and the pace of equipment bidding accelerated markedly. Among them, the revenue from the 3C industry reached 460 million yuan during the period, a sharp increase of 143% over the previous year, and a month-on-month increase of 34%.
During the reporting period, although the automobile industry was under total pressure due to the capital expenditure cycle, Tsugami China achieved growth of about 13% month-on-month. Subsequently, as the development logic of the automotive parts sector shifts from total expansion to structural upgrading, precision machining requirements around scenarios such as electric drives and integrated chassis die-casting processing will relay traditional production line demand, and Tsugami China is expected to further consolidate its competitive advantage with its own technical reserves and customer base. In the same period, Tsugami China's revenue from the pneumatic and hydraulic industry increased by about 12% year on year and remained basically the same month on month, continuing the overall steady development trend.
On the basis of the orderly expansion of the business scale, the profit potential of Tsugami China has been fully unleashed, and the company's profit elasticity is significantly superior to revenue elasticity. In the first half of the fiscal year, the company's gross margin increased to 36.2%, and net profit margin reached 22%. Profitability was further strengthened from the high base of the 2026 fiscal year. Behind this, on the one hand, thanks to the continuous expansion of revenue scale, which has effectively diluted fixed costs such as depreciation, management, and R&D, laying the foundation for high profits; on the other hand, under the guarantee of a lean management and operation system, Tsugami China is actually turning the cost advantages brought about by scale expansion into profit.
Lean management improves quality and efficiency, and capacity expansion opens up room for growth
As far as the current state of macroeconomic operation is concerned, it goes without saying that uncertainties such as external tariffs and geographical disturbances will be repeated. However, under the historic opportunity of transformation and upgrading of China's manufacturing industry, the rigid demand for equipment upgrading will continue to grow over a long period of time, and the development base for precision processing equipment is very stable. In this context, Tsugami China, a leader in precision machine tools, will continue to benefit deeply.
Tsugami China's high growth visibility is underpinned by a lean management system that runs through the entire R&D and manufacturing process of the company. According to our understanding, with “high accuracy, high speed, and high rigidity” as the core quality goal, Tsugami China integrates lean ideas into daily operations, and continues to eliminate waste and improve efficiency through an improvement proposal mechanism involving all employees — employees can directly submit improvement proposals and participate in company operations. This highly participatory mechanism maximizes the results of cost reduction and efficiency.
Currently, the product advantages of Tsugami Machine Tool are being transformed into a real increase in orders in the process of developing new industries. At present, the company's AI liquid cooling and optical modules have entered the batch procurement stage, and downstream demand is strong, which is the main driving force for performance growth. At the same time, along with the increase in humanoid robot shipments, demand for high-precision machine tools for precision structural parts processing is also rapidly increasing. In fiscal year 2027, Tsugami China took the lead in launching a precision automatic lathe model BW389ZJ in overseas markets. This product is mainly used in hydraulic, automotive and other industries.
In order to better meet the rapidly growing incremental demand of the downstream industry, Tsugami China is also stepping up construction of a new plant in Pinghu. According to the company, the new plant in Pinghu has now completed basic backfilling, and scaffolding construction and column structure construction are being promoted. It is expected to be put into operation in early 2028. At that time, the annual production capacity of the new equipment assembly will reach about 3,000 units. At the same time, in order to expand processing categories and guarantee delivery capacity, Tsugami China is also actively introducing machining equipment to increase production capacity for parts processing.
Looking at it from an investment perspective, the excellent latest financial report can be said to once again provide the strongest proof of the fundamentals of Tsugami China; and the changes in the investor structure brought about by being included in the Hong Kong Stock Connect are expected to open up a more efficient channel for its long-term value discovery. It is well known that when the high visibility of fundamentals resonates with the expansion of the investor base, Tsugami China, as an invisible champion in the manufacturing industry with both high growth and a stable shareholder return mechanism, is expected to gain fuller market recognition and pricing for its long-term allocation value.