


EN
Did Quarterly Revenue Growth Just Shift Rhythm Pharmaceuticals (RYTM) Investment Narrative?
- Rhythm Pharmaceuticals reported third quarter 2026 results, with revenue of US$92.13 million and a net loss of US$41.37 million, compared with US$51.3 million revenue and a US$52.9 million loss in the prior year period.
- The nine month figures show revenue of US$223.49 million and a net loss of US$146.31 million, which indicates growing commercial scale alongside ongoing investment that continues to weigh on profitability.
- Next, the focus turns to how Rhythm Pharmaceuticals' expanding revenue base, highlighted by the latest quarterly sales, relates to the broader investment narrative.
Compare Rhythm Pharmaceuticals with a curated set of commercial stage biopharma peers by scanning the 19 high quality undiscovered gems that may still be flying under most investors' radar.
Rhythm Pharmaceuticals Investment Narrative Recap
To own Rhythm Pharmaceuticals, you need to be comfortable with a rare disease business that is still loss making but building commercial scale around IMCIVREE and an MC4R focused pipeline. According to peter_4mgsy, an investor in the Simply Wall St Community, the appeal comes from multiple approved indications and future label expansion opportunities in genetic obesity disorders.
The latest quarter fits that story, with higher revenue alongside a continuing net loss that reflects ongoing R&D and commercialization spend. In the near term, a key catalyst remains execution in new and existing indications for IMCIVREE. The biggest operational risk is that spending stays heavy without matching uptake or reimbursement depth in target patient groups.
The fresh third quarter 2026 earnings release is the announcement that matters most right now. Rhythm Pharmaceuticals reported US$92.13 million in quarterly revenue and a loss of US$41.37 million, with nine month revenue of US$223.49 million and a nine month loss of US$146.31 million. Basic loss per share also narrowed compared with the prior year period.
For catalysts, that update gives you a clearer view of how IMCIVREE commercialization is tracking before considering any future pipeline inflection points flagged by peter_4mgsy. The figures indicate that Rhythm Pharmaceuticals remains in an investment heavy phase, so execution risk around operating costs, trial progress and payer access still sits front and center for shareholders.
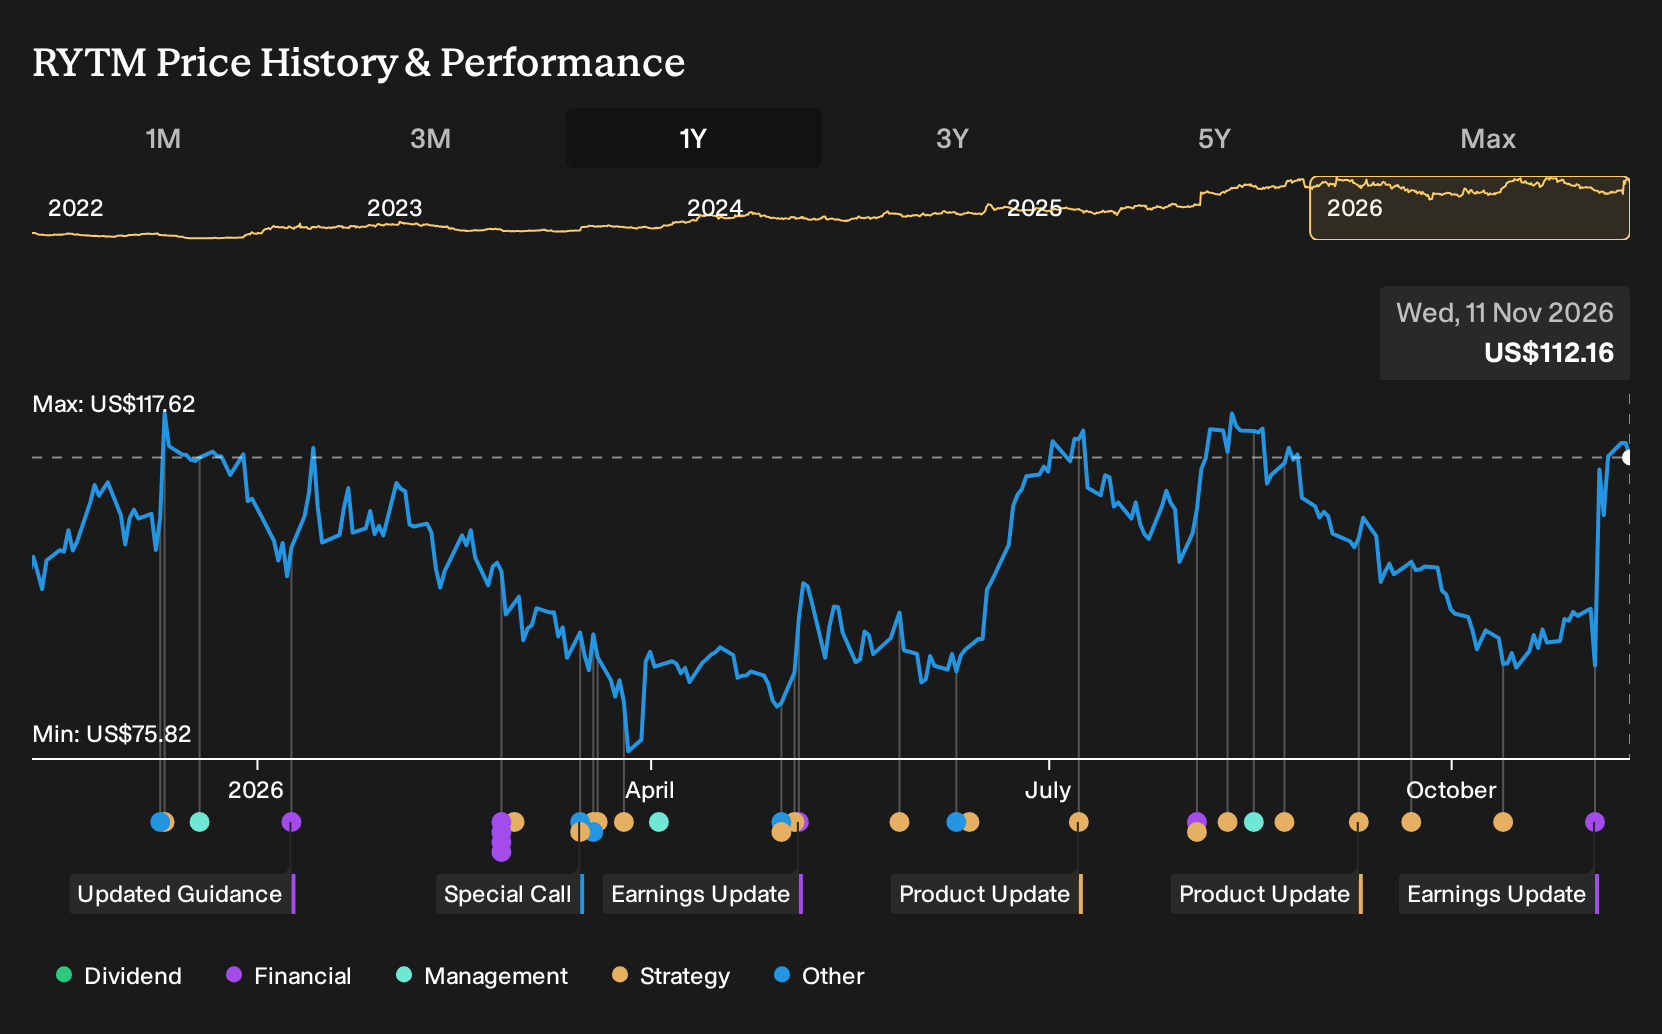
In that context, peter_4mgsy sees Rhythm Pharmaceuticals reaching a fair value of US$134.00 per share, primarily because IMCIVREE already serves multiple approved genetic obesity indications and, in this view, still has meaningful room to expand into additional targeted obesity disorders.
Uncover why Rhythm Pharmaceuticals' fair value indicates a 19% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
For Rhythm Pharmaceuticals, the lowest analysts focus less on new indications and more on competition risk. They worry that rival MC4R drugs could cap the value of IMCIVREE, and were pencilling in about US$918.6 million of revenue and US$197.0 million of earnings by 2029. Those projections came before this latest earnings update, so their story may shift.
Explore 2 other Rhythm Pharmaceuticals fair value estimates, including one that suggests it could be worth just $134.00.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment outcomes often come from careful independent thinking, so consider your own analysis.
- A great starting point for your Rhythm Pharmaceuticals research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Rhythm Pharmaceuticals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to review Rhythm Pharmaceuticals' overall financial health at a glance.
Looking For More Rhythm Pharmaceuticals Investment Ideas?
If the Rhythm Pharmaceuticals story has sharpened your appetite for research, use the Simply Wall St Screener to line up a watchlist that actually fits your style rather than chasing every headline that comes across your feed.
- For investors who care most about quality at a fair price, run your filters across a 32 high quality undervalued stocks that already score well on both fundamentals and valuation checks.
- If capital preservation sits higher on your priority list than excitement, narrow the field to a 30 resilient stocks with low risk scores that aim to keep risk scores in check while still offering equity upside.
- When balance sheet strength matters more to you than short term share price moves, concentrate on a list of solid balance sheet and fundamentals (23 results) that pair healthier leverage and liquidity profiles with underlying business resilience.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com