


EN
Why Did Power Integrations (POWI) Shares Jump After Its Latest Update?
Power Integrations (POWI) just delivered third quarter results that shifted from a net loss to net income, paired with fresh fourth quarter revenue guidance and a reaffirmed quarterly dividend for shareholders.
Power Integrations shares jumped 5.8% on the day of the earnings release. However, the 90-day share price return is down 25.39% after a strong year-to-date rise of 24.64%, while the 1-year total shareholder return of 32.65% contrasts with a weaker 3- and 5-year total shareholder return. This suggests that recent momentum has picked up after a much tougher multi-year stretch as investors reassess growth prospects and risks around the current US$46.49 share price and ongoing dividend payments.
See how Power Integrations compares with other potential rebound stories by reviewing our curated list of 19 high quality undiscovered gems featuring solid fundamentals but limited current market attention.
Power Integrations has returned to profit and the share price has bounced, yet the longer-term chart still looks bruised. So at about US$46 a share, are you paying up for quality or still getting a deal?
Most Popular Narrative: 23% Undervalued
Power Integrations is trading at a last close of $46.49, while the analyst consensus Narrative on Simply Wall St sets fair value at about $60.67 based on detailed revenue and earnings forecasts that are discounted at 11.32%.
Power Integrations' proprietary high-voltage GaN technology, now extending from 750–1700 V up to 2,200 V and reaching into applications that have used silicon carbide, supports premium positioning in higher power systems and has the potential to lift average selling prices and gross margins.
See why 9 investors see Power Integrations as 23% undervalued.
Result: Fair Value of $60.67 (UNDERVALUED)
Still, the bullish Power Integrations story relies heavily on higher voltage GaN adoption, while stretched valuation and elevated channel inventory could quickly test that optimism.
Find out about the key risks to this Power Integrations narrative.
Another View: What The P/E Ratio Says About Power Integrations
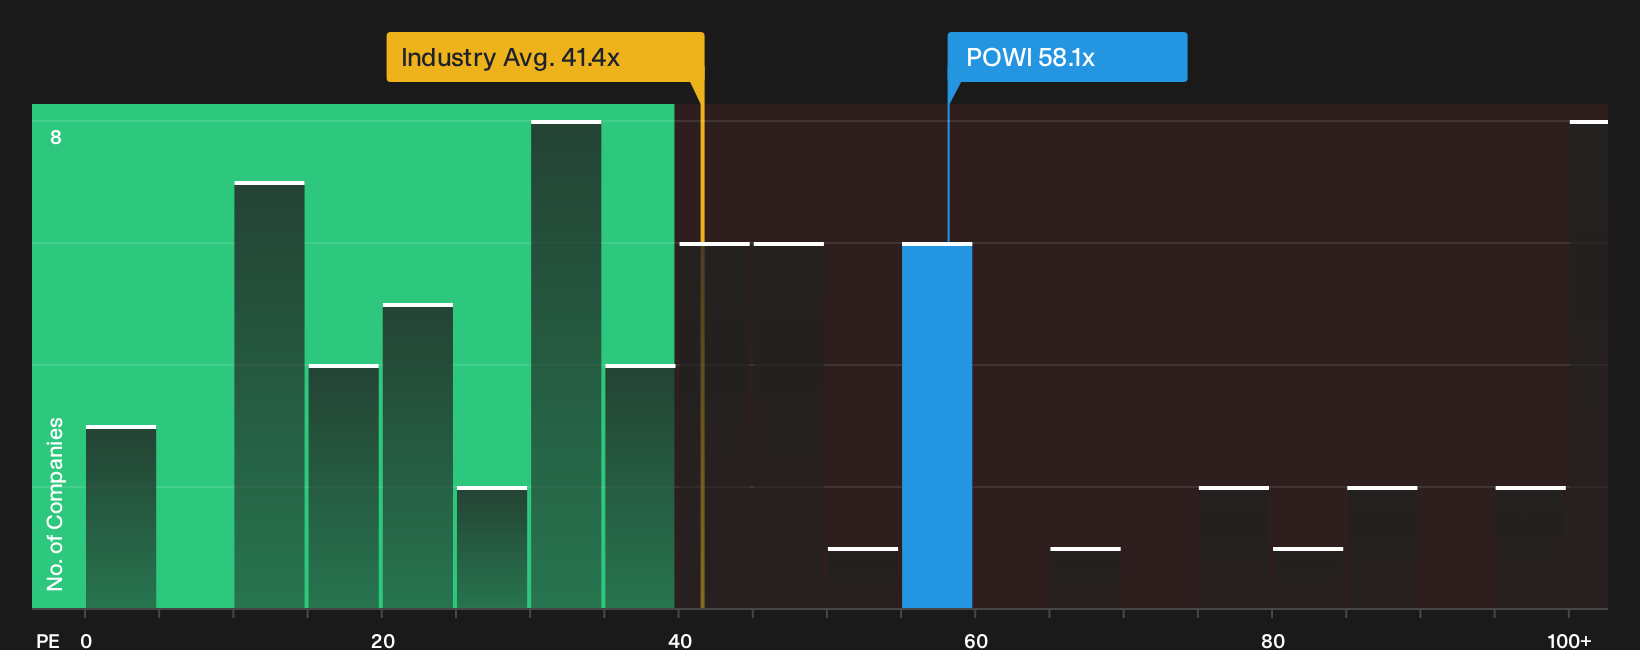
The analyst narrative presents Power Integrations as about 23% undervalued based on a discounted cash flow style fair value of $60.67. The market, however, is applying a P/E of 58.1x, which is far above the US Semiconductor industry at 39.1x, peers at 25.9x, and a fair ratio of 34.7x. That kind of premium leaves far less room if the story around GaN, earnings growth, or margins loses steam even slightly.
Given that gap, it is worth asking whether the DCF-driven upside case is generous, or whether the earnings multiple eventually drifts closer to the fair ratio and industry levels over time.
See what the numbers say about this price in our valuation breakdown. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the Power Integrations story feels finely balanced between promise and pressure, do not wait for consensus to harden before checking the underlying data yourself. Put the recent results, valuation signals, and sentiment into context by weighing its 3 key rewards and 1 important warning sign with 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Power Integrations?
If Power Integrations has your attention, do not stop there. A broader watchlist gives you more options when sentiment or valuations shift again.
- Target potential mispricings by reviewing a curated 32 high quality undervalued stocks that filters for quality businesses trading below their estimated worth.
- Strengthen your income stream by scanning a focused 6 dividend fortresses built around companies with higher yields and an emphasis on payout resilience.
- Dial back risk by assessing a 30 resilient stocks with low risk scores that highlights resilient businesses with more conservative risk scores and steadier profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com