


EN
Is Icahn Enterprises (IEP) Undervalued As Sales Rose But Losses Returned?
Icahn Enterprises (IEP) is back in focus after third quarter results showed higher reported sales alongside a swing to a net loss, while the partnership kept its quarterly cash distribution unchanged at $0.50 per unit.
Icahn Enterprises’ unit price has retreated sharply in 2026, with a year to date share price return down 33.1% and a 30 day share price return down 24.3%. The 1 year total shareholder return has fallen 28.2%, which points to fading momentum as investors reassess risk around deeper reported losses despite the steady cash distribution.
Spot opportunities beyond Icahn Enterprises by scanning a curated 32 high quality undervalued stocks that combines solid cash flows with balance sheets built to handle tougher conditions.Icahn Enterprises now trades far below its assessed intrinsic value after a steep slide, and it still pays a cash distribution that has not moved. Does it make more sense to step in today or wait for an even cheaper entry point?
Preferred Price-to-Sales of 0.3x: Is It Justified for Icahn Enterprises?
Icahn Enterprises currently trades on a P/S ratio of 0.3x, which looks low beside both its peers at 2.6x and the wider Global Industrials group at 0.7x. With the last close at $5.01, that discount suggests the market is pricing the partnership on far slimmer revenue expectations than comparable businesses.
The P/S multiple compares the market value of the equity to annual sales and is often used when a company is unprofitable. For a diversified partnership like Icahn Enterprises, where net income was a loss of $1,016.0m on revenue of $10,892.0m, earnings based metrics can be less informative. In this context, anchoring on revenue can help frame what investors are willing to pay for each dollar of turnover.
Based on the Simply Wall St assessment, Icahn Enterprises is also trading 49.3% below an estimate of its future cash flow value, with units at $5.01 versus a modelled value of $9.87. That gap, together with the low P/S ratio compared to both direct peers and the broader Industrials cohort, suggests the market is assigning a heavy discount to the partnership’s complex structure and its history of reported losses rather than the top line it generates.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Sales of 0.3x (UNDERVALUED)
Still, the ongoing net loss of $1,016.0m and the recorded loss in the Investment segment, alongside the complex multi segment structure, could keep pressure on Icahn Enterprises’ valuation story.
Find out about the key risks to this Icahn Enterprises narrative.
Another View: What The SWS DCF Says About Icahn Enterprises
The low P/S ratio presents Icahn Enterprises as inexpensive relative to its sales. The SWS DCF model points in the same direction, with units at $5.01 compared with an estimated future cash flow value of $9.87. That is a 49.3% gap, which indicates potential valuation upside but also raises a straightforward question for investors: Is this discount a mispricing, or is it compensation for real business and funding risks?
Look into how the SWS DCF model arrives at its fair value.
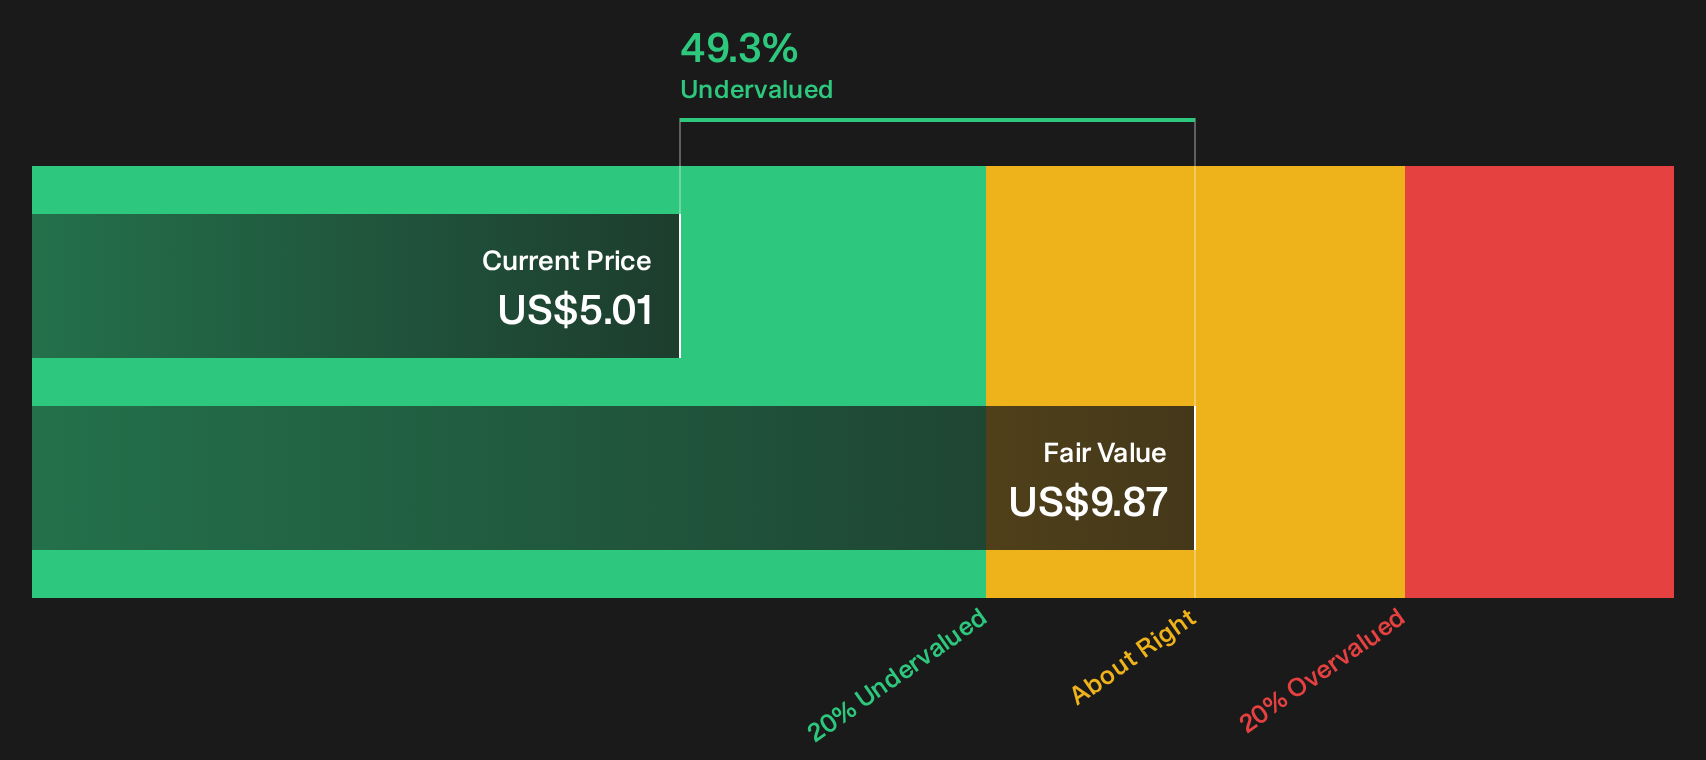
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Icahn Enterprises for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed feelings about Icahn Enterprises so far. If the mix of reported risks and potential upsides has you on the fence, move quickly from headline impressions to hard data and pressure test the story yourself with the 1 key reward and 3 important warning signs
Looking for more investment ideas beyond Icahn Enterprises?
If Icahn Enterprises has sharpened your focus on price, risk, and resilience, do not stop here. Broaden your watchlist with targeted ideas that match your style.
- Target potential upside by scanning a curated set of undervalued opportunities through the 32 high quality undervalued stocks that already screens for quality and pricing support.
- Prioritize resilience and support more stable outcomes by focusing on a 30 resilient stocks with low risk scores that filters for companies with more stable risk profiles.
- Hunt for underfollowed potential by reviewing a 19 high quality undiscovered gems that highlights strong fundamentals before they gain wider attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com