


EN
How AI Infrastructure Support At Impinj (PI) Has Changed Its Investment Story
- Impinj recently took part in the BMO Capital Technology and Innovation Leaders Conference in New York, where Chief Financial Officer Cary L. Baker presented the company’s story and financial positioning to institutional investors.
- This participation highlights how Impinj is engaging directly with the market at a time when AI infrastructure policy is shaping demand expectations for semiconductor components tied to its RAIN RFID platform.
- We will now look at how Impinj's investment narrative could be influenced by the sector rebound linked to AI infrastructure support.
Impinj Investment Narrative Recap
To own Impinj, you have to believe its RAIN RFID platform keeps gaining real-world use across retail, logistics and food traceability, and that this translates into more tagged items and a higher mix of systems and M800 based ICs. The analyst consensus narrative on Simply Wall St leans on that idea, along with an improving financial profile and record free cash flow in Q2 2026.
The near-term swing factor is how cleanly Impinj converts strong endpoint IC bookings into consistent orders after past Q1 demand misreads with a large logistics customer. The biggest risk is that channel visibility issues or pricing pressure offset the targeted gross margin lift from M800, which would leave earnings and cash generation under strain.
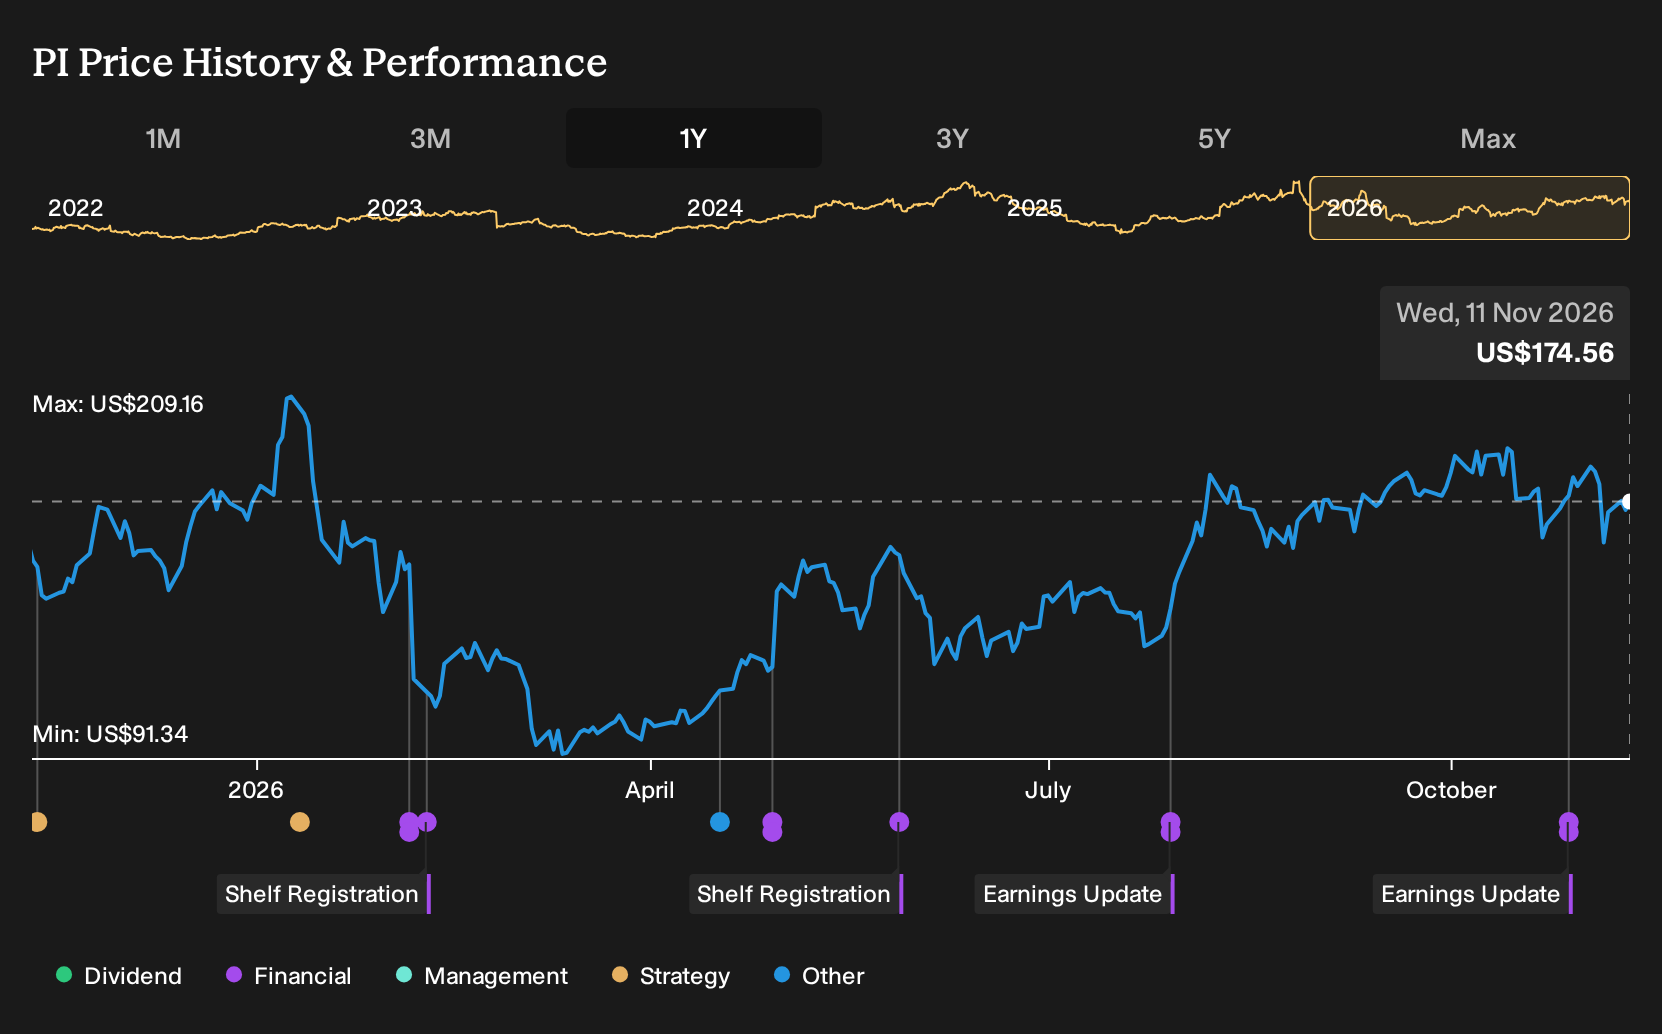
The most relevant development here is Impinj’s presence at the BMO Capital Technology and Innovation Leaders Conference on 12 November 2026, with CFO Cary L. Baker presenting in New York. That appearance came just after the stock moved 4.1% higher as semiconductor and hardware peers recovered from a sharp sell-off tied to AI infrastructure headlines.
For investors, the conference matters because it puts Impinj’s AI-related data center angle and broader RFID rollout story directly in front of institutional holders at a moment when the sector rebound has refreshed interest in high price-to-sales, execution-sensitive hardware stories. It also gives management a chance to explain demand visibility fixes and margin goals again as investors weigh both the AI infrastructure catalyst and the risk of renewed sentiment pushback on valuation and ongoing losses.
Impinj's current analyst framework points to revenues of $650.1 million and earnings of $107.2 million by 2029, built on an assumed 18.8% yearly revenue growth rate and a swing in earnings of roughly $116.7 million from a loss of $9.5 million today to that 2029 consensus level.
Uncover how Impinj's fair value indicates a 14% potential upside to its current price before the market closes the gap.
Exploring Other Perspectives
For Impinj, the bullish twist is not just more RAIN RFID tags. The most optimistic analysts frame the real catalyst as wider fixed reading solutions tied into AI heavy data centers. They were already pencilling in about US$714.3 million of revenue and US$135.0 million of earnings by 2029. Those projections came before this BMO conference appearance and the AI infrastructure headlines, so some investors may revisit both the upbeat and cautious narratives as fresh information lands.
Explore 2 other Impinj fair value estimates, including one that suggests up to 18% upside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Impinj research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Impinj. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Impinj's overall financial health at a glance.
Looking for more Impinj sized investment ideas?
If the Impinj story has sharpened your thinking, it can help to compare it with other opportunities that match different risk and quality profiles using the Simply Wall St Screener.
- For readers who care most about balance sheet strength, start with a list of solid balance sheet and fundamentals (23 results) that keeps financial resilience front and center.
- If capital preservation is your priority, filter for a 30 resilient stocks with low risk scores that may align better with a steadier riding style.
- For those hunting for overlooked opportunities, cast a wider net with a 19 high quality undiscovered gems that pairs quality fundamentals with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com