


EN
What Regeneron Pharmaceuticals (REGN)'s Liver Drug Trial Results Mean For Shareholders
- Regeneron Pharmaceuticals reported first-in-human data for its investigational CIDEBsiRNA in MASLD, with a single subcutaneous dose showing dose-dependent liver fat reductions of 58% to 80% at week 36, sustained improvements in liver injury markers, and an overall safety profile that was broadly similar to placebo in this early study.
- The early CIDEBsiRNA results highlight how Regeneron is using human genetics to design liver-targeted RNA therapies for steatotic liver disease. This could influence future development priorities, capital allocation across its pipeline, and how it balances near-term earnings from approved drugs with longer-horizon metabolic programs.
- The focus now shifts to how Regeneron Pharmaceuticals' investment narrative lines up with these MASLD trial data, particularly the deep liver fat reductions.
Scan beyond Regeneron Pharmaceuticals and this MASLD update by checking out 37 healthcare AI stocks, which are also working at the intersection of data, biology, and next-generation therapies.
What Is Regeneron Pharmaceuticals' Investment Narrative?
To own Regeneron Pharmaceuticals, you have to buy into a fairly simple idea. The core franchises that generated US$16.9b of revenue and US$4.8b of net income over the last year need to keep funding a wide research engine, while newer platforms like siRNA and gene editing gradually matter more. The CIDEBsiRNA MASLD data fits this story cleanly. It reinforces that Regeneron is willing to spend heavily on long cycle, genetics based programs while still reporting sizeable earnings today.
In the near term, the bigger operational drivers remain execution on existing products, pricing power in key categories and how aggressively management leans into buybacks and dividends after the recent US$839.5m repurchase and ongoing quarterly payout of US$0.94 per share. CIDEBsiRNA is more of a medium term swing factor than an immediate P&L event, although the Phase 2b and Phase 3 commitments raise the capital intensity of the metabolic pipeline. That sits against risks such as slower forecast revenue growth versus the broader US market and a P/E above the biotech industry average.
Even so, there is a catch that only really shows up once you look closely at how dependent Regeneron still is on ...
There's only one way to know the right time to buy, sell or hold Regeneron Pharmaceuticals. Head to Simply Wall St's company report for the latest analysis of Regeneron Pharmaceuticals's Fair Value.
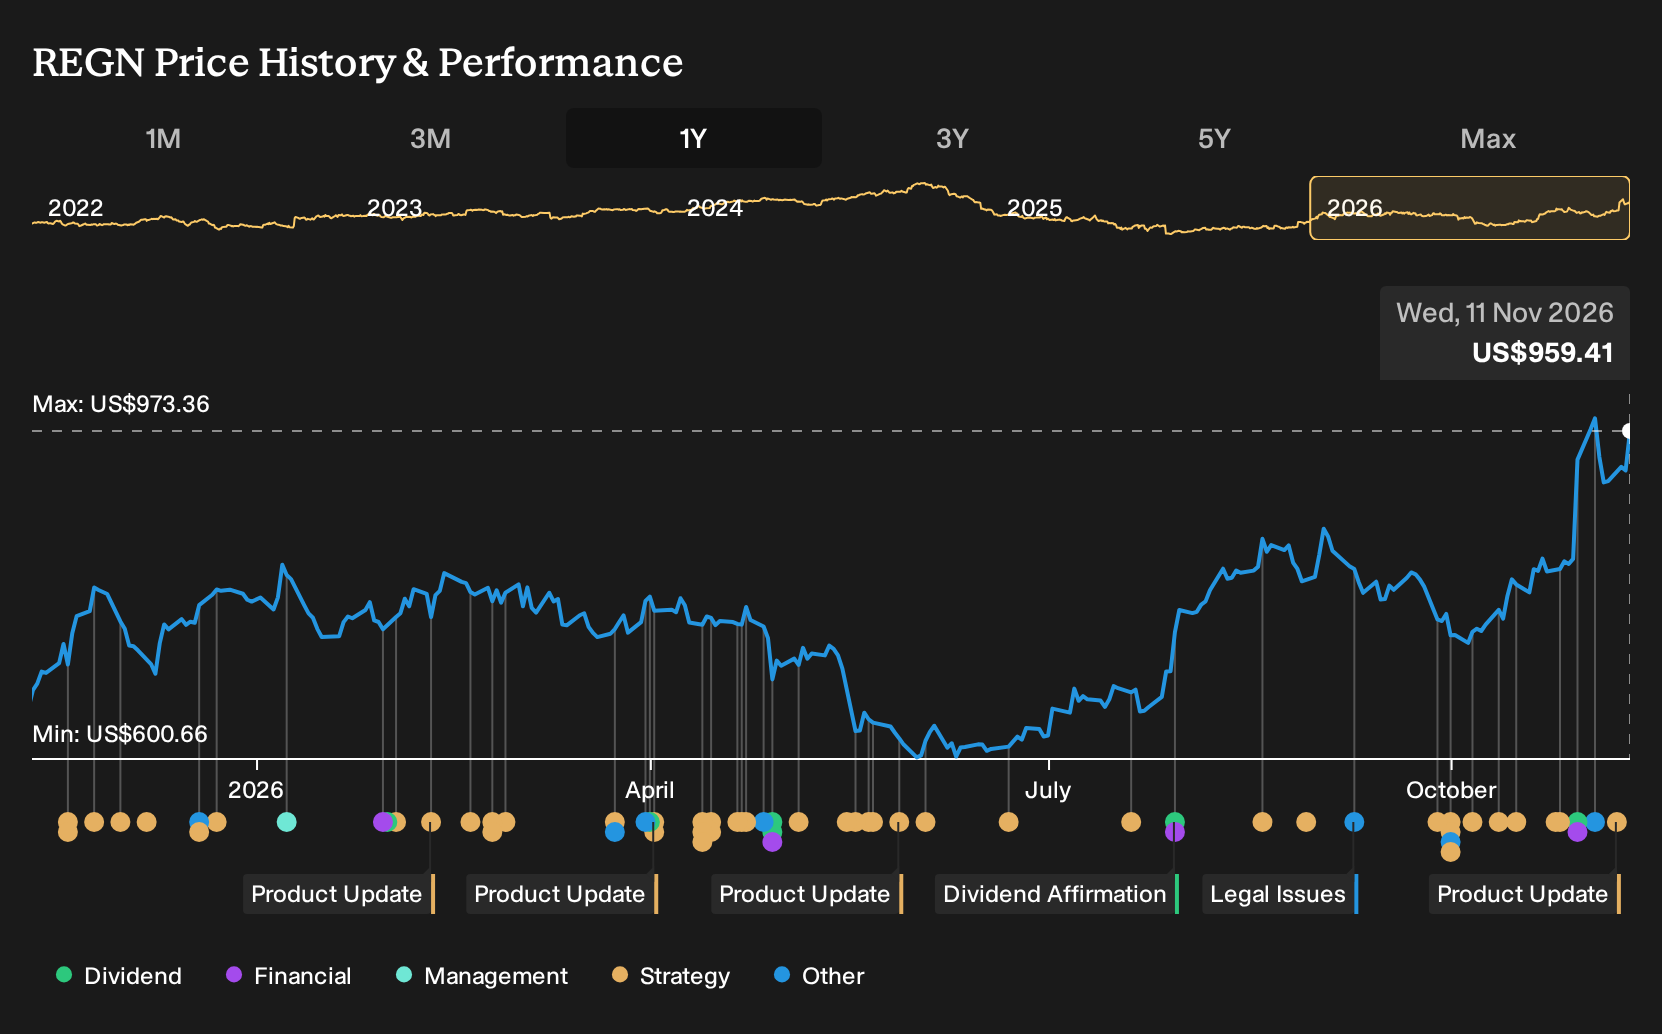
Exploring Other Perspectives
One alternate storyline around Regeneron Pharmaceuticals is much gloomier on concentration risk. The lowest analysts were penciling in revenue of about US$19.7b and earnings of roughly US$6.9b by 2029, yet still saw the stock meriting only a 13.5x P/E. Those forecasts came before the CIDEBsiRNA MASLD data, so you may see those views shift.
Explore 4 other Regeneron Pharmaceuticals fair value estimates, including one that suggests there could be as much as 12% downside from the current price.
Decide For Yourself
Do not just follow the ticker; dig into the data and build a conviction that is truly your own.
- A great starting point for your Regeneron Pharmaceuticals research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Regeneron Pharmaceuticals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Regeneron Pharmaceuticals' overall financial health at a glance.
Looking For More Investment Ideas Beyond Regeneron Pharmaceuticals?
Once you have a view on Regeneron Pharmaceuticals, it can help to widen the lens and compare it with other opportunities that share some of the qualities you are looking for.
- If you care most about valuation and want to focus on companies that combine quality fundamentals with pricing that looks appealing on multiple metrics, take a look at 32 high quality undervalued stocks.
- If balance sheet strength matters to you and you prefer businesses with cleaner debt profiles and solid financial footing, start with this list of solid balance sheet and fundamentals (23 results).
- If you are hunting for lesser known opportunities that still show strong underlying numbers, broaden your watchlist with 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com