


EN
Only Three Days Left To Cash In On TORM's (CPH:TRMD A) Dividend
It looks like TORM plc (CPH:TRMD A) is about to go ex-dividend in the next 3 days. Typically, the ex-dividend date is two business days before the record date, which is the date on which a company determines the shareholders eligible to receive a dividend. The ex-dividend date is important as the process of settlement involves at least two full business days. So if you miss that date, you would not show up on the company's books on the record date. Thus, you can purchase TORM's shares before the 16th of November in order to receive the dividend, which the company will pay on the 18th of November.
The company's next dividend payment will be US$1.35 per share, and in the last 12 months, the company paid a total of US$2.12 per share. Based on the last year's worth of payments, TORM has a trailing yield of 6.0% on the current stock price of kr.238.60. If you buy this business for its dividend, you should have an idea of whether TORM's dividend is reliable and sustainable. As a result, readers should always check whether TORM has been able to grow its dividends, or if the dividend might be cut.
Dividends are typically paid out of company income, so if a company pays out more than it earned, its dividend is usually at a higher risk of being cut. TORM is paying out an acceptable 70% of its profit, a common payout level among most companies. That said, even highly profitable companies sometimes might not generate enough cash to pay the dividend, which is why we should always check if the dividend is covered by cash flow. Over the past year it paid out 139% of its free cash flow as dividends, which is uncomfortably high. We're curious about why the company paid out more cash than it generated last year, since this can be one of the early signs that a dividend may be unsustainable.
While TORM's dividends were covered by the company's reported profits, cash is somewhat more important, so it's not great to see that the company didn't generate enough cash to pay its dividend. Cash is king, as they say, and were TORM to repeatedly pay dividends that aren't well covered by cashflow, we would consider this a warning sign.
Check out our latest analysis for TORM
Click here to see the company's payout ratio, plus analyst estimates of its future dividends.
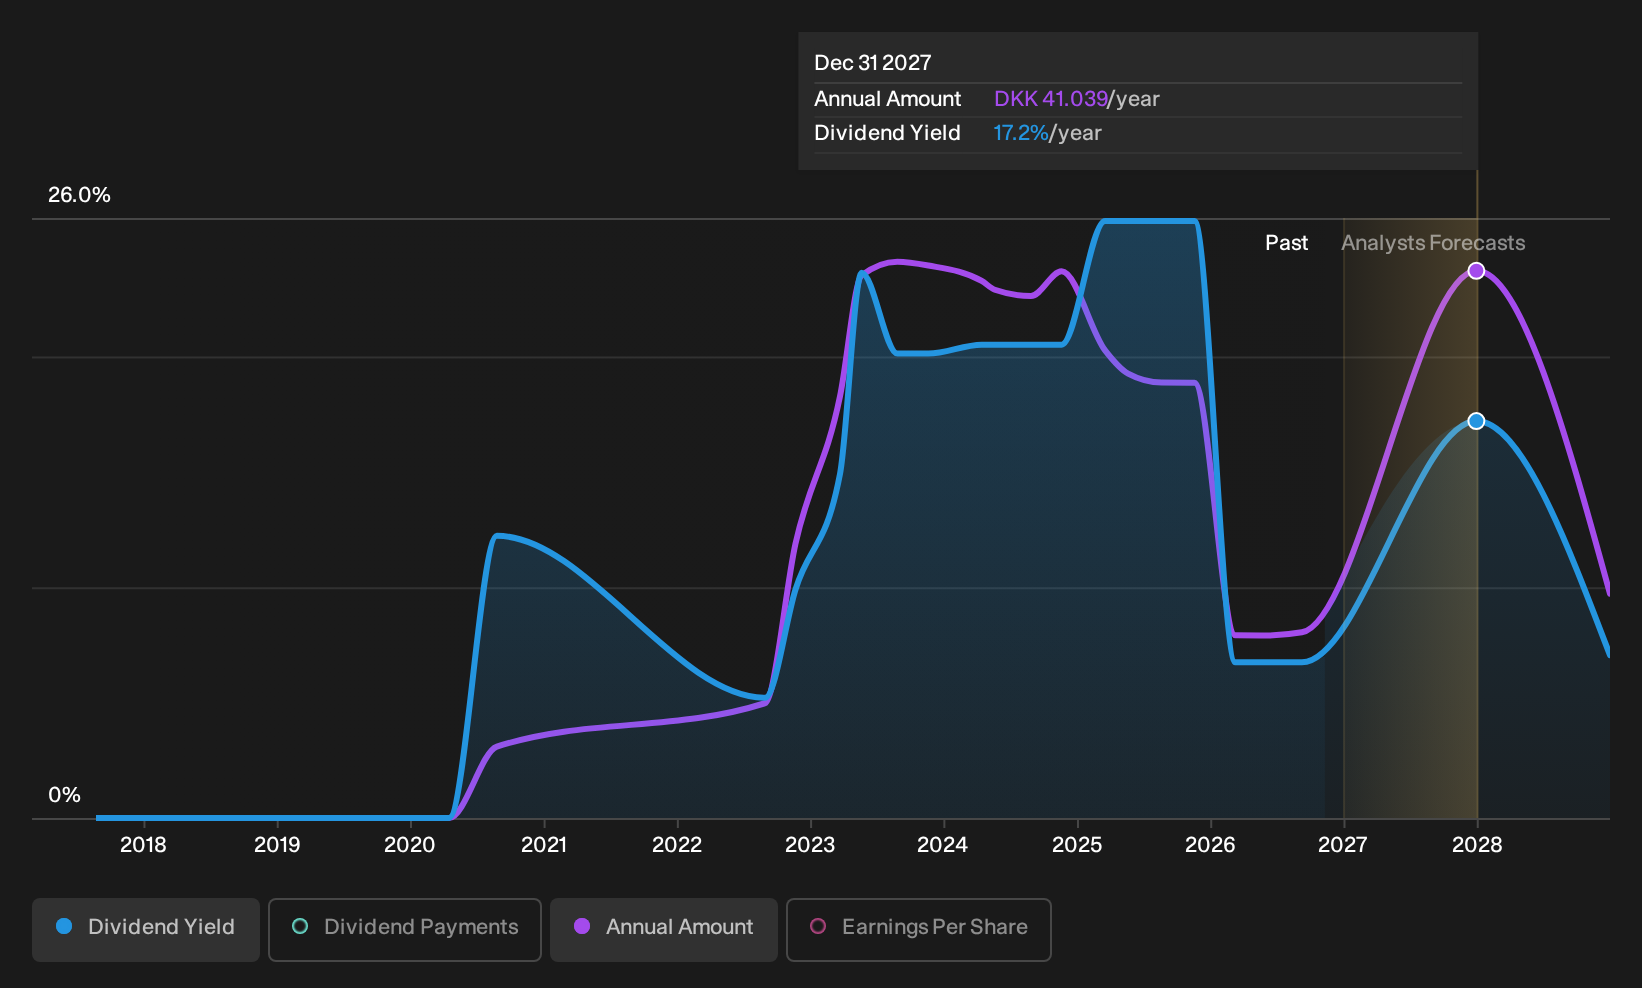
Have Earnings And Dividends Been Growing?
Companies with consistently growing earnings per share generally make the best dividend stocks, as they usually find it easier to grow dividends per share. If earnings fall far enough, the company could be forced to cut its dividend. That's why it's comforting to see TORM's earnings have been skyrocketing, up 44% per annum for the past five years. Earnings have been growing quickly, but we're concerned dividend payments consumed most of the company's cash flow over the past year.
Many investors will assess a company's dividend performance by evaluating how much the dividend payments have changed over time. In the last 10 years, TORM has lifted its dividend by approximately 10% a year on average. Both per-share earnings and dividends have both been growing rapidly in recent times, which is great to see.
To Sum It Up
Should investors buy TORM for the upcoming dividend? Earnings per share growth is a positive, and the company's payout ratio looks normal. However, we note TORM paid out a much higher percentage of its free cash flow, which makes us uncomfortable. It might be worth researching if the company is reinvesting in growth projects that could grow earnings and dividends in the future, but for now we're not all that optimistic on its dividend prospects.
If you want to look further into TORM, it's worth knowing the risks this business faces. We've identified 4 warning signs with TORM (at least 1 which is a bit unpleasant), and understanding them should be part of your investment process.
A common investing mistake is buying the first interesting stock you see. Here you can find a full list of high-yield dividend stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.