


EN
Optimized structure, offer confirmation, circulation calibration: is Cantelon (01912)'s annual increase of over 260% just the beginning?
In the undercurrent of Hong Kong's capital market, behind every seemingly bland announcement, there may be a game of carefully calculated chess hidden behind it.
This can be seen from Cantelon (01912), who has been moving a lot recently.
Since the second half of 2026, Cantelon has continued to implement processes such as position transfers, subscription and placement, mandatory offers, changes in directors, and resuming public shareholding. On the surface, it is a superposition of multiple capital actions. Essentially, it is more like a clear-paced, closed-loop capital restructuring — that is, removing historical burdens, resetting the chip structure, and completing governance handover within compliance boundaries to make room for subsequent industry implementation.
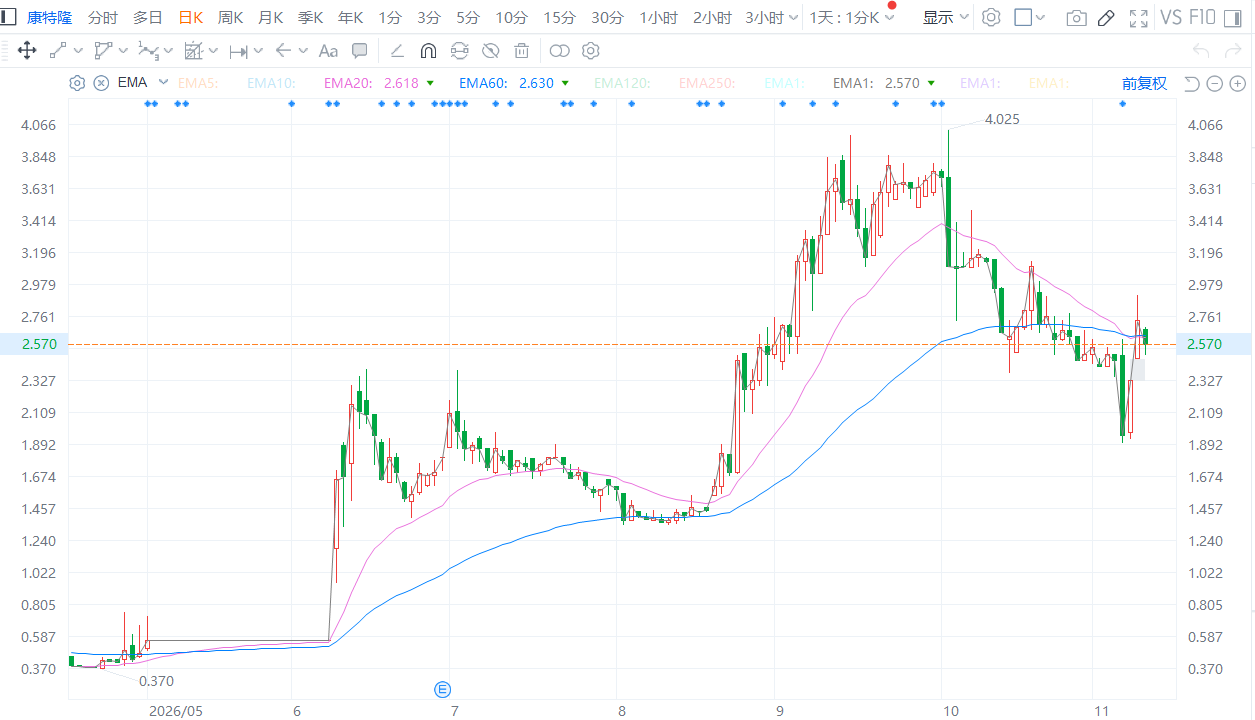
Meanwhile, since the second half of 2026, Cantelon's stock price has also emerged from a typical capital-driven market. From July to August, control changed hands, and the stock price remained at HK$1.6-1.8, far higher than the HK$0.365 offer price. Personnel changes on August 24 rose 14.38% on the same day; the September offer was implemented, and blood exchanges drove up high volatility; in October, the market gradually absorbed high expectations, and valuations followed the trend; in November, public shareholding compliance was implemented, and stock prices began to recover again. The volume surged 18.97% on November 9 and 17.67% on November 10. As of the close of trading on November 11, the stock price was HK$2.55. Although down from its high during the year, the increase is still as high as 261.97% this year.
(Market source: Futu)
Of course, whether Cantelon can complete the closed loop of capital operation and achieve value revaluation is yet to be answered at every step in the future — we might as well follow its capital trajectory and observe the success of this stock platform restructuring.
44.17% of chips were placed in the warehouse, and 58.81% of the holding was settled
Following its capital trajectory, the first key signal of Cantelon Capital's operation is not the wording of the announcement, but the market position: the beginning of the platform's revaluation begins with the collection of chips.
On July 29, Cantelon experienced significant position changes. A large number of shares were deposited into Astron Capital Management. The market value of the deposit reached HK$93.71 million, accounting for 44.17%. The concentration of large chips in a single seat is not an accidental transaction pulse; it is a key pre-project in the control chain: first collect chips, then calmly promote subscription, placement, and offers, reduce gaming costs caused by scattered chips, and lay the foundation for gaining control.
The plan underlying this layout was jointly announced as early as June 8: Cantelon and Ziil, owned by Zhuang Hezhong, announced that under special authorization, they would issue approximately 271 million shares and 58.205 million new shares to ZIIL for subscription at HK$0.365 each, raising about HK$99 million; at the same time, they publicly placed 58.205 million new shares at the same price to raise HK$21.2 million.
If all new shares are issued, ZIIL will hold about 58.81% of the expanded share capital, become the controlling shareholder, and make a possible unconditional mandatory cash offer. The offer price is HK$0.365, a discount of about 34.8% compared to the suspension of trading of HK$0.56. The maximum amount payable of the offer is about HK$693.42 million.
Among them, ZIIL Group intends to continue to operate its main business and maintain its listed position. It plans to nominate new directors to join the board of directors and replace several directors of subsidiary companies. The funding arrangement is also pragmatic: the total capital raised from the subscription and placement was about HK$120 million, prioritized for repayment of overdue debts and supplier arrears, and then reserved as working capital to free up space for subsequent debt settlement and business integration.
ZIIL's approach is essentially a “clean first, then raise the price” platform revaluation path. For platforms burdened with historical arrears, paying off overdue debts and supplier arrears first is equivalent to unloading old burdens and freeing up clean statements for new business integration; at the price level, the offer price is discounted by about 34.8% from the closing price before suspension, which not only re-determines the value of the original assets, but also helps control acquisition costs, screen out existing shareholders who are willing to withdraw, and reduce resistance to subsequent integration.
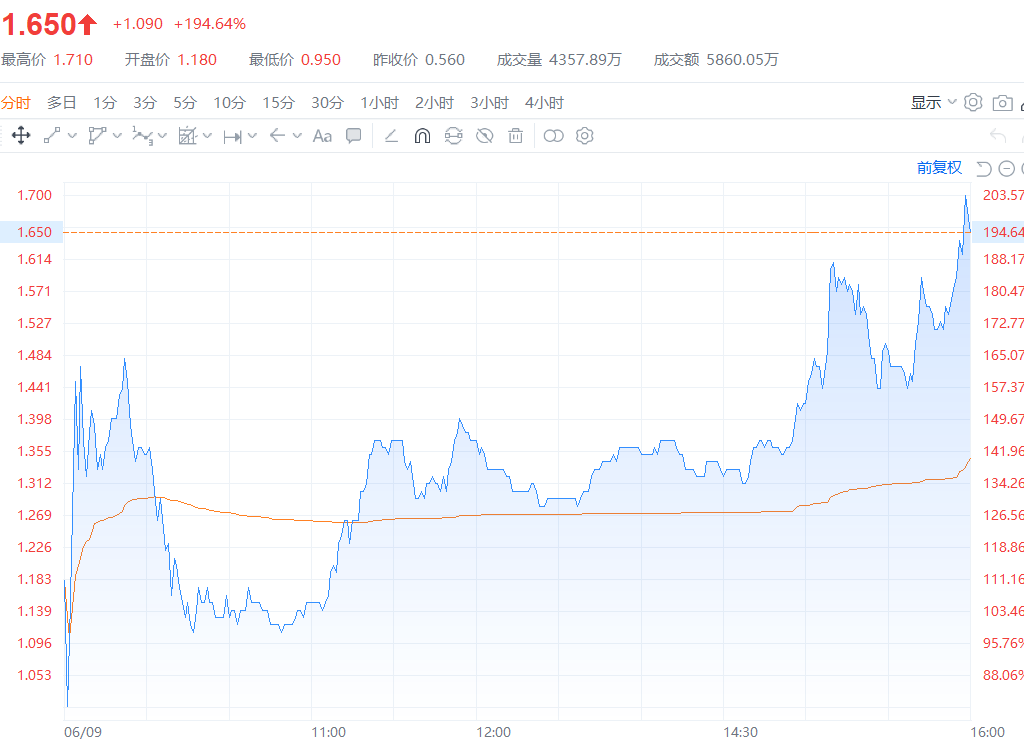
The immediate reaction of the market confirmed this logic. After resuming trading on June 9, Cantelon's stock price once opened more than 110% higher, and reached a maximum of HK$1.71, but the turnover did not form a huge amount at the same time. The closing volume was HK$586.05 million — this just shows that a large number of chips have been locked in advance and the circulation market is relatively manageable. The market is more expecting changes in control and the revaluation of the platform's value than Gamble's spot chips.
(Market source: Futu)
What supports this expectation is the value chassis of the Cantelon platform itself. Judging from operating data, Cantelon's fundamentals are not impressive: for the fiscal year ending March 31, 2026, revenue was $51.399 million, and the company owner should have accounted for a loss of HK$0.89 per share — limited revenue scale, continuous losses, weak hematopoietic capacity of the original business, making it difficult to get out of trouble with endogenous growth. However, it fully retains its listing qualifications, financing channels, and market identity, which is the core value of the Shell platform.
Of course, whether the value of the shell can be realized ultimately depends on who manages it. Looking through ZIIL's background, the answer is already at first sight — in fact, the controller Zhuang Hezhong has been deeply involved in the import and export, wholesale and retail fields of consumer electronics integrated circuits and semiconductor modules for many years, and has a solid industrial business foundation. This means that it is not simply held for the sake of holding, but lays the groundwork for the subsequent introduction of industrial resources into the platform and activation of stock value.
76.34% held control, 25.01% released liquidity
It is worth noting that once the chips and financing are in place, confirmation of authority becomes a critical step.
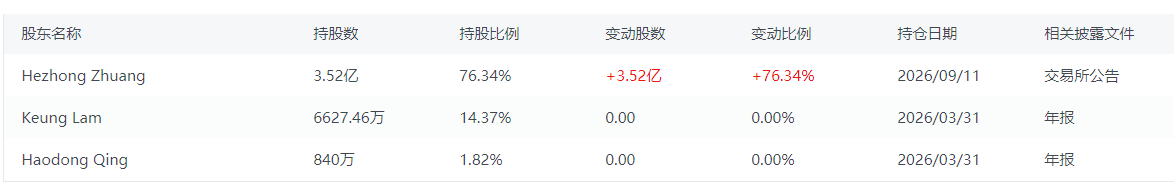
According to Zhitong Finance, the Cantelon offer ended at 4:00 p.m. on September 11, 2026. The offeror received 6 valid offers totaling 808.495 million shares, accounting for about 17.53% of the issued share capital, and the total cost of the offer was about HK$29.51 million. Immediately after the end of the offer, the offeror, its ultimate beneficial owners and those acting in concert held a total of approximately 352 million shares, accounting for about 76.34% of the total issued share capital.
(Image source: Futu)
76.34% is a figure worth perusing. It's high enough — high enough that control is firm and governance restructuring is enforceable; yet it deliberately doesn't push for an IPO-like structure with a “single major shareholder of 75% or more.” The function of an offer is not to be implemented in one step, but rather to concentrate chips, confirm control, and free up space for subsequent capital operations.
At the same time, when the controlling interest was implemented, Cantelon also simultaneously completed the management and blood exchange. Just when the joint announcement was issued, the five original directors, Lin Qiang, Zheng Yubi, Deng Kunlei, Chen Guoquan, and Li Wanxin, resigned, clearing the way for new shareholders to nominate personnel to join the board of directors. The collective change of directors is not only a change in personnel, but also a change in business ideas: let go of dependency on the original business path, so that new shareholders can evaluate assets, plan business, and promote subsequent industrial introduction at their own pace.
Judging from capital logic, it is difficult for a single offer to reach the ideal concentration range of 85% to 95% in one step. If we want to continue to move closer to a higher level of concentration, we can also continue to optimize the chip structure by relying on additional issuance, share supply, and targeted placement to consolidate control without touching the bottom line of public shareholding. In other words, the offer is a “phased confirmation”, not the end of the entire chip project.
After the authorization is confirmed, the circulation review guidelines determine whether the platform can continue. This also means that Cantelon can control the chips, and they also need to distribute them properly.
Therefore, after the end of the offer, the company applied for a phased exemption from the Stock Exchange under the listing rule that public shareholding was once less than 25%, leaving a time window for an orderly release. On November 5 and 6, the offeror sold a total of 6.2 million shares in batches in the market. After release, the public held 115 million shares, accounting for 25.01%. It just crossed the minimum threshold and completed the closed loop of compliance.
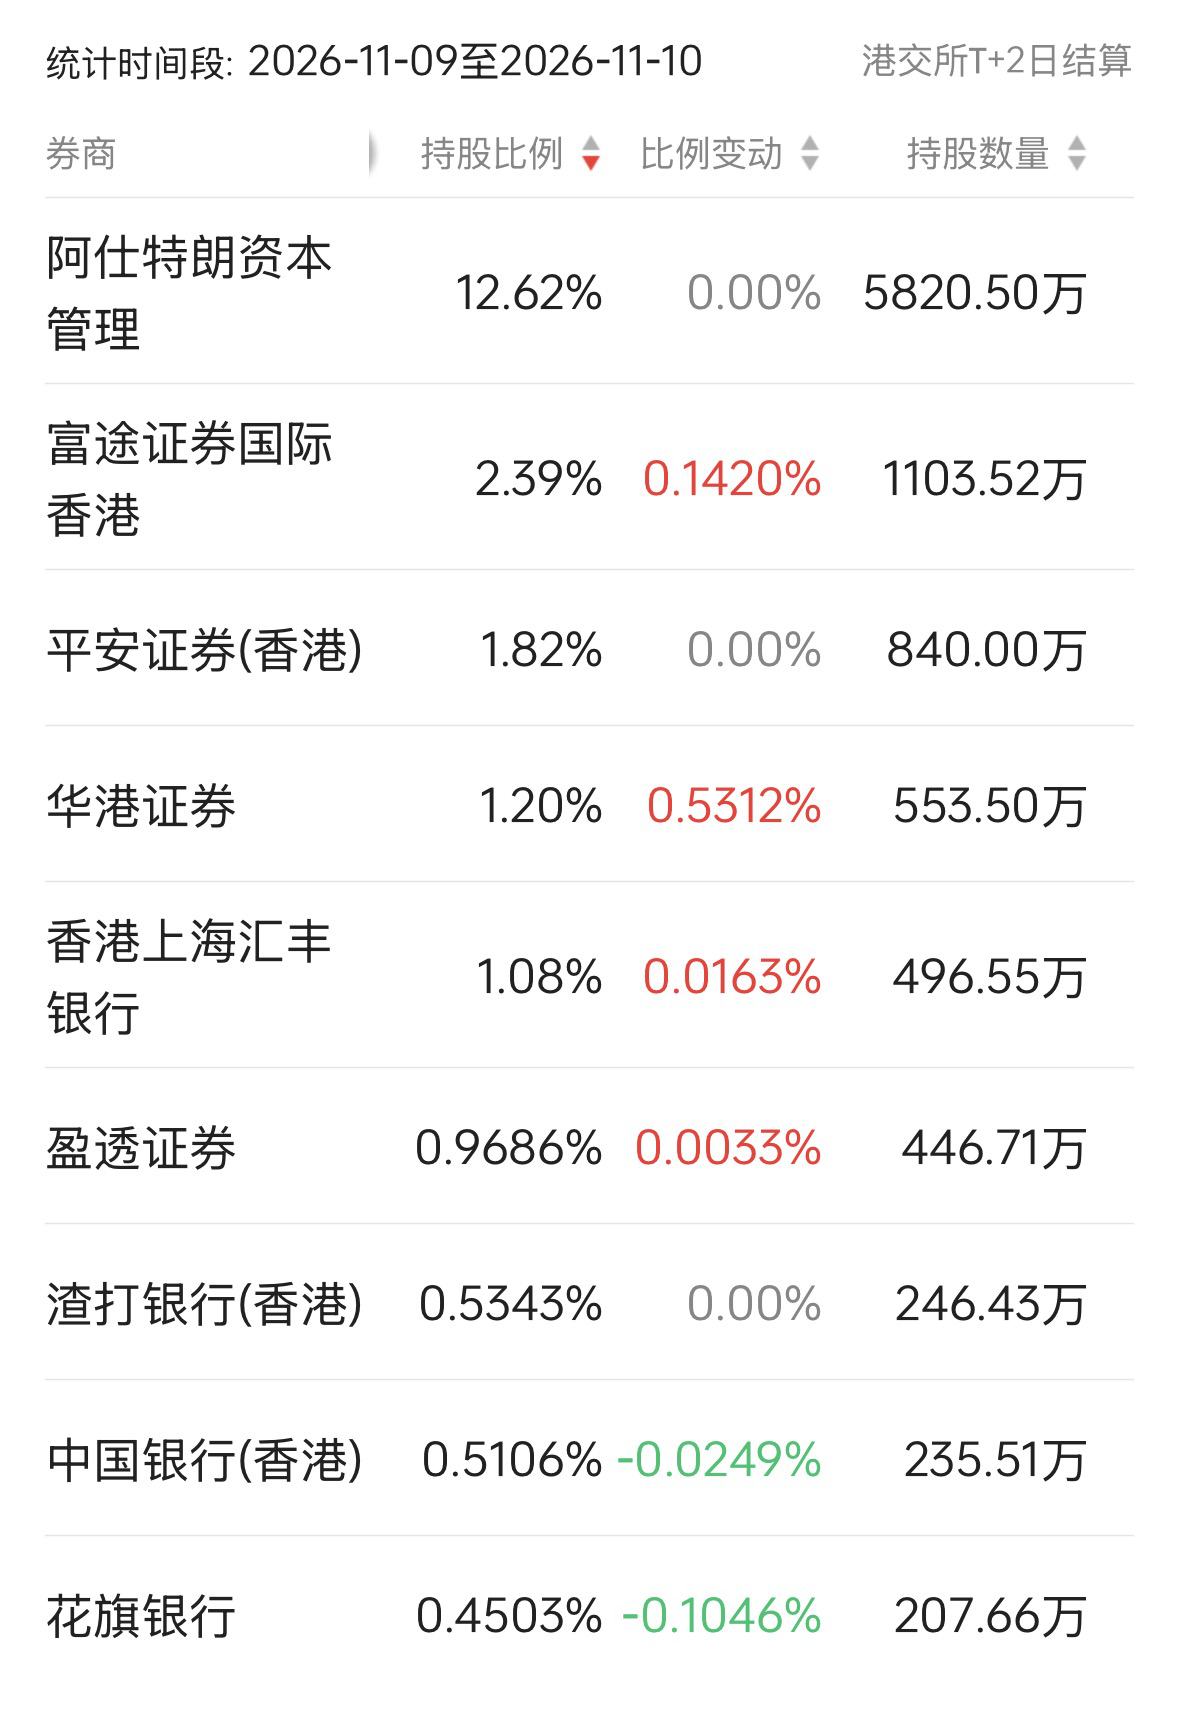
Cantelon's brokerage shareholding data also provided a market footnote for this “compliance calibration.” According to the Zhitong Finance and Brokerage Seat Search System, during the statistical period from November 9 to 10, Cantelon brokers held about 117 million shares, accounting for 25.43% of positions, which basically coincides with the red line of 25% of public shareholding. Among them, the top three brokerage firms, Astro, Futu Securities, and Ping An Securities held 12.62%, 2.39%, and 1.82% of the shares respectively.
(Data source: Zhitong Finance)
As a result, for Cantelon, the sale by the bidders on November 5 and 6 in batches was not a reduction in holdings, but rather a precise “compliance calibration”, which fully reflected the sense of proportion of the operation: too slow release faced survival risks; if too much was released, stock prices fluctuated and control was passively diluted. Selling in batches and meeting the standards not only preserves listing eligibility, but also retains sufficient control, so that the platform can once again have a reasonable liquidity base. Stock prices fluctuated during the recovery process, essentially an expected rebalance — the market gradually understood that the release of chips was not tantamount to relinquishing control, but rather brought compliance to the entire capital operation.
Summarize
In summary, it is easy to see that this round of operation by Cantelon showed the market a path of re-activation of an inventory listing platform with regulations: centralized storage locks the chassis, subscription and placement triggers an offer, public procedures are completed and confirmed, debts are cleared and unburdened, directors are changed to achieve governance handover, and then accurately release the circulation market to maintain the bottom line of compliance.
It is not a hype that deviates from the rules; it is a capital restructuring completed step by step under the Hong Kong stock listing rules and takeover rules. Its core value is not about how high the chips are piled up, but rather about exchanging time for space to turn an existing stock platform that is burdened by business and burdened with debt into a carrier that can carry the industry and continue financing.
This is also a revaluation paradigm worth exploring in the Hong Kong stock market. Hong Kong stock listings have never been a fixed operating carrier — when traditional main businesses continue to lose money, historical debt suppresses development, and the growth of the original system peaks, the greatest value of an enterprise is often not the profit contribution of old businesses, but rather scarce listing status, smooth capital channels, and reshapable equity structures. With debt clean-up, chip restructuring, and management iteration, companies can bypass the long review cycle of traditional IPOs, complete capital exchange and industry modernization in the most efficient manner, and achieve a second shift in platform value.
Next, the market's focus will not only be on whether the Cantelon chip structure meets the standards, but will shift to asset injection schedules, business integration progress, refinancing arrangements, and whether performance can be gradually repaired. When the circulation market is stable, governance is straightened, and debts are settled, whether this platform can actually complete the leap from a “closed loop of capital structure” to “implementation of industrial value” is the final answer to testing the failure of this round operation.