


EN
Evergy (EVRG) Could Be 4% Undervalued After Strong Results And Dividend Hike
Why Evergy’s latest earnings and dividend moves matter now
Evergy (EVRG) just posted third quarter and year to date results showing higher sales, net income, and earnings per share compared with 2025, while also lifting its regular quarterly dividend.
Evergy’s recent earnings release and dividend increase have landed after a strong run, with the share price up 20.88% year to date and a 1-year total shareholder return of 19.75% helping to extend an already very large 3-year total shareholder return of 98.35%. That kind of long term wealth creation signals that investors have been willing to pay up for the utility’s cash flows, while the latest quarter’s results and higher payout appear to be keeping sentiment supported rather than fading. At a current share price of $88.34, recent 30 day share price momentum of 7.56% and a 5.13% 90 day share price return suggest the market is still adjusting its view of Evergy’s risk and income profile in light of the new numbers.
Scan how Evergy’s mix of earnings momentum and income appeal compares with other regulated utilities by running your filters through our curated 42 power grid technology and infrastructure stocks for potential grid-focused opportunities.
Evergy’s sharp move on the back of stronger reported earnings and a richer dividend could reflect genuine business strength rather than just a mood shift in the market. How does that show up in the current valuation?
Most Popular Evergy Narrative: 3.5% Undervalued
Evergy’s last close of $88.34 sits a little below the analyst consensus Narrative fair value of $91.50, which uses a 7.236% discount rate and blends earnings forecasts with data center load assumptions from sector research in the analyst consensus Narrative on Simply Wall St.
Strong anticipated growth in electricity demand from large-scale data centers, advanced manufacturing such as Panasonic's EV battery plant, and other commercial users remains central to Evergy's outlook. Signed long-term agreements total about 3 GW of large-load demand and are expected to support future revenue and earnings as these customers ramp through 2030.
See why 16 investors see Evergy as 3% undervalued.
Result: Fair Value of $91.50 (UNDERVALUED)
Still, Evergy’s story can break if big data center and industrial customers use less of their contracted load, or if regulators push back harder on future rate increases.
Find out about the key risks to this Evergy narrative.
Another View on Evergy’s valuation
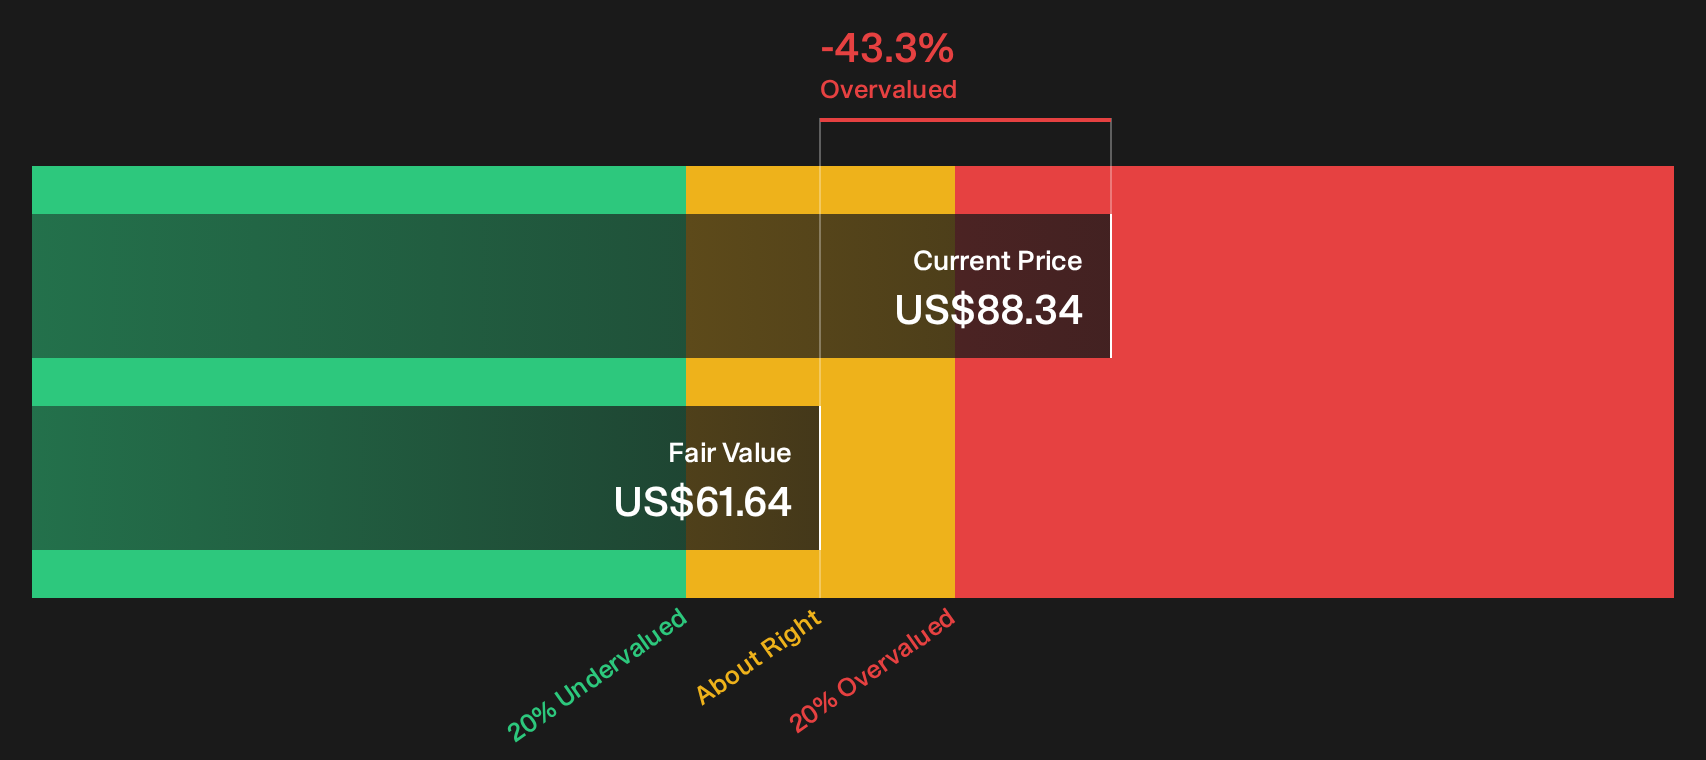
The analyst narrative frames Evergy as about 3.5% undervalued versus a fair value of $91.50. Step away from that storyline and the SWS DCF model paints a different picture. On future cash flows, Evergy’s estimated value is $61.64, so the current $88.34 price screens as expensive. Which lens do you trust more when the gap is this wide?
Our DCF approach relies on long term cash flow forecasts and a chosen discount rate rather than earnings multiples. It therefore reacts differently to assumptions about capital spending, funding mix, and long term returns on equity. Look into how the SWS DCF model arrives at its fair value.
Next Steps
That mix of optimism and concern around Evergy gives you a live debate to plug into. Act quickly. Review the underlying metrics and weigh both sides using the 2 key rewards and 2 important warning signs.
Looking for more Evergy-sized investment ideas?
If Evergy has sharpened your focus, do not stop with one ticker. Use this momentum and line up fresh ideas before the crowd moves on.
- Target resilient cash generators by scanning a 32 high quality undervalued stocks that already pair quality fundamentals with appealing prices.
- Prioritise capital protection and stability through a 30 resilient stocks with low risk scores that filter for businesses with more durable profiles.
- Uncover future candidates early by running a 19 high quality undiscovered gems that highlight quality companies still flying under most investors' radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com