


EN
Vertiv Holdings Co (VRT) Signs Infineon Supply Deal, Is A 54% Discount Real?
Vertiv Holdings Co (VRT) has put supply security for its AI focused power hardware in sharper focus after signing a three year agreement with Infineon Technologies for key power semiconductor components.
The new Infineon agreement lands after a volatile run for Vertiv Holdings Co, with the share price falling 28.06% over the past 90 days and 13.72% over the last month. Even so, the year to date share price return is 17.60% and the 3 year total shareholder return is roughly 4x, which points to strong longer term momentum that recent swings have not erased.
Scan how Vertiv Holdings Co fits into the broader AI buildout by comparing it with 53 AI infrastructure stocks powering next generation data centers and high demand compute projects.
Vertiv has already had a huge AI run, then dropped hard on sector worries, which leaves a simple fork in the road: Is most of the upside already in the rear-view mirror, or is the reset setting up better value now?
Most Popular Narrative: 54% Undervalued
Vertiv Holdings Co closed at $206.51, while the most followed community valuation pegs fair value near $450, which frames the recent pullback very differently.
This narrative, written by FundamentalFlow, an investor in the Simply Wall St Community, argues that Vertiv is less a typical industrial and more like a mission critical utility for AI data centers.
To understand how Vertiv really stands out from the crowd, you have to stop thinking of them as a "tech company" and start seeing them as a mission critical utility. Most of their competitors are stuck in the "component" mindset, selling a single power supply or a basic rack, but Vertiv has pivoted to become a full-service architect of the data center's nervous system.
See why 90 investors see Vertiv Holdings Co as 54% undervalued.
In that view, the $450 fair value comes from treating Vertiv as the infrastructure backbone for liquid cooling and high density power, not just another hardware vendor. A discount rate of 9.16% is applied to those future cash flows, which reflects a meaningful required return while still crediting the growth profile set out in the narrative.
With the current share price at $206.51, that framework implies Vertiv trades at a discount of roughly 54% to the fair value estimate. For readers comparing valuation anchors, this sits alongside Simply Wall St's own DCF output of $267.11 per share, which also points to the shares trading below an internally assessed cash flow value.
Result: Fair Value of $450 (UNDERVALUED)
Still, Vertiv Holdings Co faces pressure points if data center projects are delayed or if rising liquid cooling competition compresses margins and weakens the undervaluation thesis.
Find out about the key risks to this Vertiv Holdings Co narrative.
Another View On Vertiv Holdings Co: Earnings Multiple Sends A Different Signal
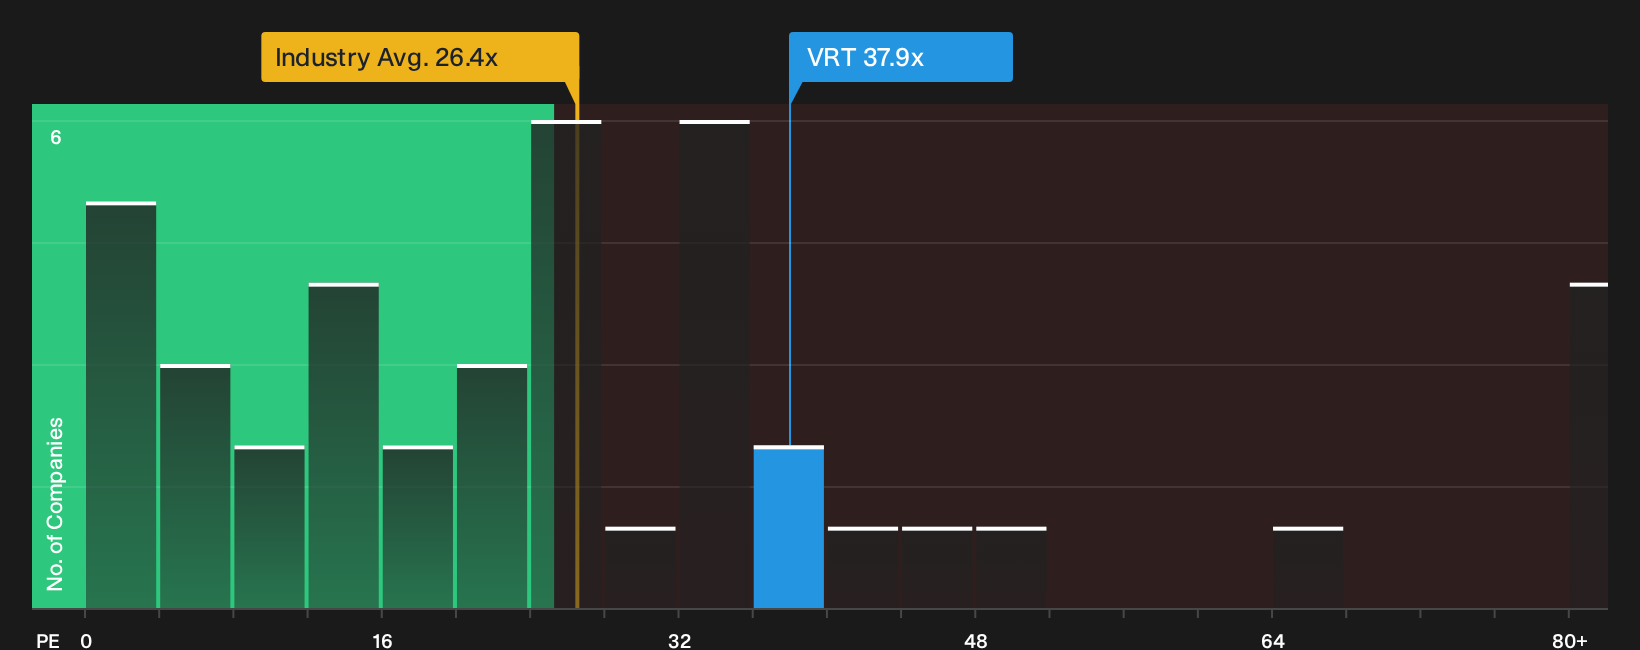
The narrative fair value of $450 paints Vertiv Holdings Co as deeply undervalued, yet the market is already paying a rich P/E of 37.9x. That is higher than the US Electrical industry at 26.4x and above the 33.9x peer average, which suggests a premium price tag rather than a clear bargain.
Against that, the fair ratio for Vertiv sits at 46.6x earnings. If investors eventually lean closer to that mark, today’s multiple could still leave room. It also raises a simple question for you as a shareholder or watcher: is this premium a cushion or a risk if growth cools?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the split tone of this Vertiv Holdings Co story has you torn, move quickly from headline takes to hard evidence. Start by weighing the mixed signals for yourself using the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Vertiv Holdings Co?
Do not stop your research with Vertiv Holdings Co. Broaden your watchlist with a few focused stock ideas that match the type of opportunities you care about most.
- Target potential mispricings and seek quality at a discount by scanning the 32 high quality undervalued stocks that meet strict fundamental checks and cash flow standards.
- Anchor your portfolio around stability and capital strength by filtering through a list of solid balance sheet and fundamentals (24 results) that can help support resilience when conditions get tougher.
- Spot early stage opportunities before they hit the mainstream by reviewing a curated pool of 19 high quality undiscovered gems backed by underlying business performance, not just hype.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com