


EN
Lumexa Imaging Holdings (LMRI) Jumped, So What Is Behind The Latest Attention?
Lumexa Imaging Holdings (LMRI) returned to profitability in its latest quarterly report, posting third quarter net income of US$7.18 million on US$271.97 million in revenue, and reiterating full year revenue guidance.
The earnings report on 10 November has been followed by a sharp reset in expectations, with Lumexa Imaging Holdings delivering a 1 day share price return of 14.58% and a 30 day share price return of 50.33%, even though the year to date share price return is still down 9.12% from earlier levels.
Scan how Lumexa Imaging Holdings compares with other healthcare operators showing strong momentum and solid balance sheets in the curated list of solid balance sheet and fundamentals (24 results)
Lumexa Imaging Holdings now has improving earnings and a sharply higher share price. The real task for investors is to determine whether this rebound still leaves enough value on the table.
Most Popular Narrative: 7.7% Undervalued
On the analyst consensus Narrative on Simply Wall St, Lumexa Imaging Holdings screens as modestly undervalued, with a fair value estimate of $17.29 compared to the latest close at $15.95. That view leans heavily on specific growth drivers and margin assumptions rather than sentiment.
Aging populations with complex conditions and higher use of advanced imaging such as MRI, CT and PET, together with new treatment paradigms that rely on imaging, support Lumexa’s focus on higher reimbursing modalities. This focus is aimed at lifting revenue per procedure and adjusted EBITDA margins over time.
See why 2 investors see Lumexa Imaging Holdings as 8% undervalued.
Result: Fair Value of $17.29 (UNDERVALUED)
Still, the Lumexa Imaging Holdings story can break if referral volumes slow for higher acuity scans or if new centers and AI tools do not ramp efficiently, which could drag on margins and cash generation.
Find out about the key risks to this Lumexa Imaging Holdings narrative.
Another View: Multiples Paint A Tougher Picture For Lumexa Imaging Holdings
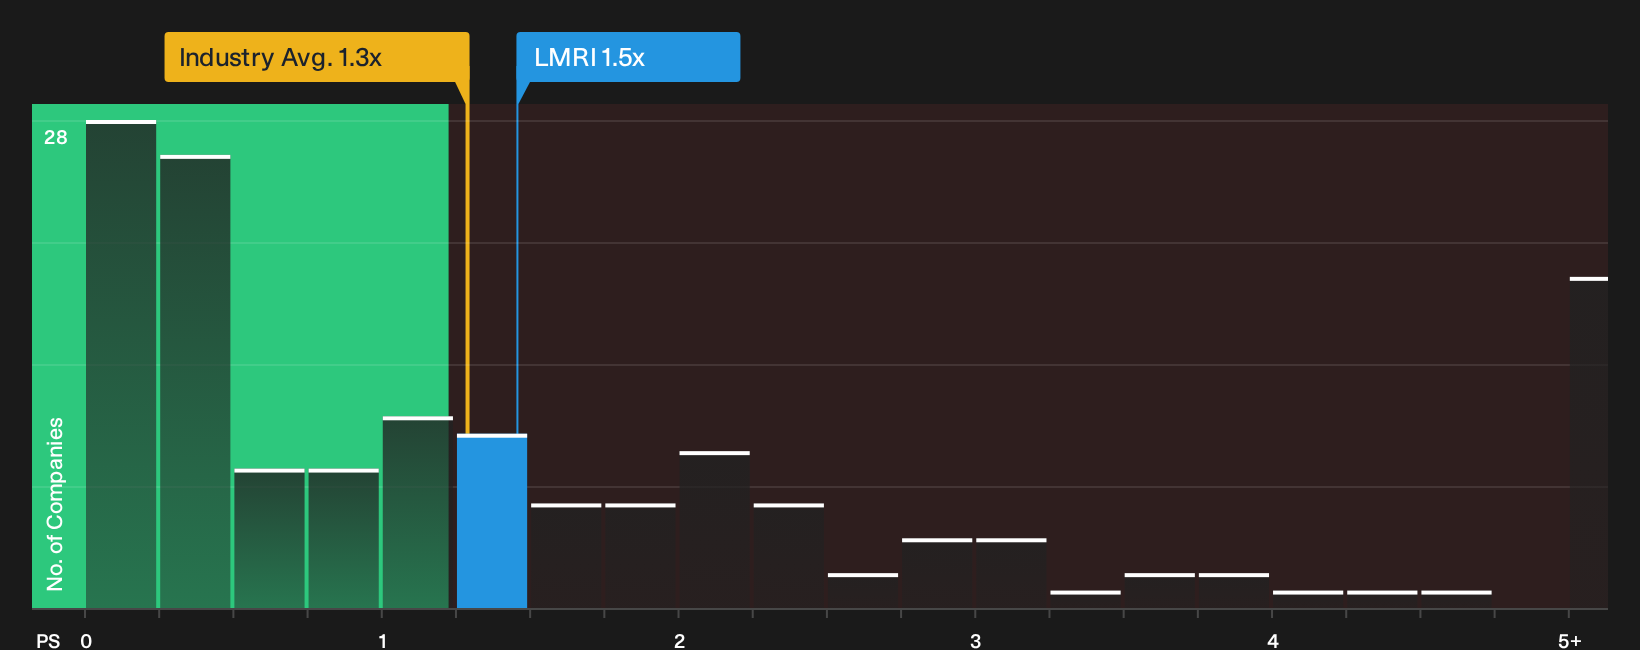
The analyst narrative and SWS DCF work point to upside for Lumexa Imaging Holdings. Market pricing on sales tells a harsher story. LMRI trades on a P/S of 1.5x, which is richer than both the US Healthcare sector at 1.3x and an SWS fair ratio of 0.5x. That gap suggests investors are already paying up for execution that still needs to be delivered. Is this a valuation cushion, or a margin for error that is already used up?
To see how this pricing gap lines up with the underlying numbers and risks, take a look at the See what the numbers say about this price — find out in our valuation breakdown..
For a visual sense of how LMRI’s current valuation compares with sector peers, review the
Next Steps
Sentiment looks cautiously optimistic around Lumexa Imaging Holdings, so it makes sense to review the full data set yourself and decide if the current pricing matches your expectations. To see what aspects of the story investors are most positive about, start with the 3 key rewards.
Looking for more investment ideas beyond Lumexa Imaging Holdings?
If Lumexa Imaging Holdings has sharpened your focus, use that momentum and widen your watchlist. Fresh ideas often come from scanning outside your usual comfort zone.
- Target cash-generative opportunities that still look overlooked by the market through the 32 high quality undervalued stocks.
- Build a portfolio that aims for resilience in tougher markets with the 30 resilient stocks with low risk scores.
- Spot earlier stage stories with strong underlying fundamentals before they gain wider attention by reviewing the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com