


EN
Are Strong Earnings Altering The Investment Case For Acadian Asset Management Stock?
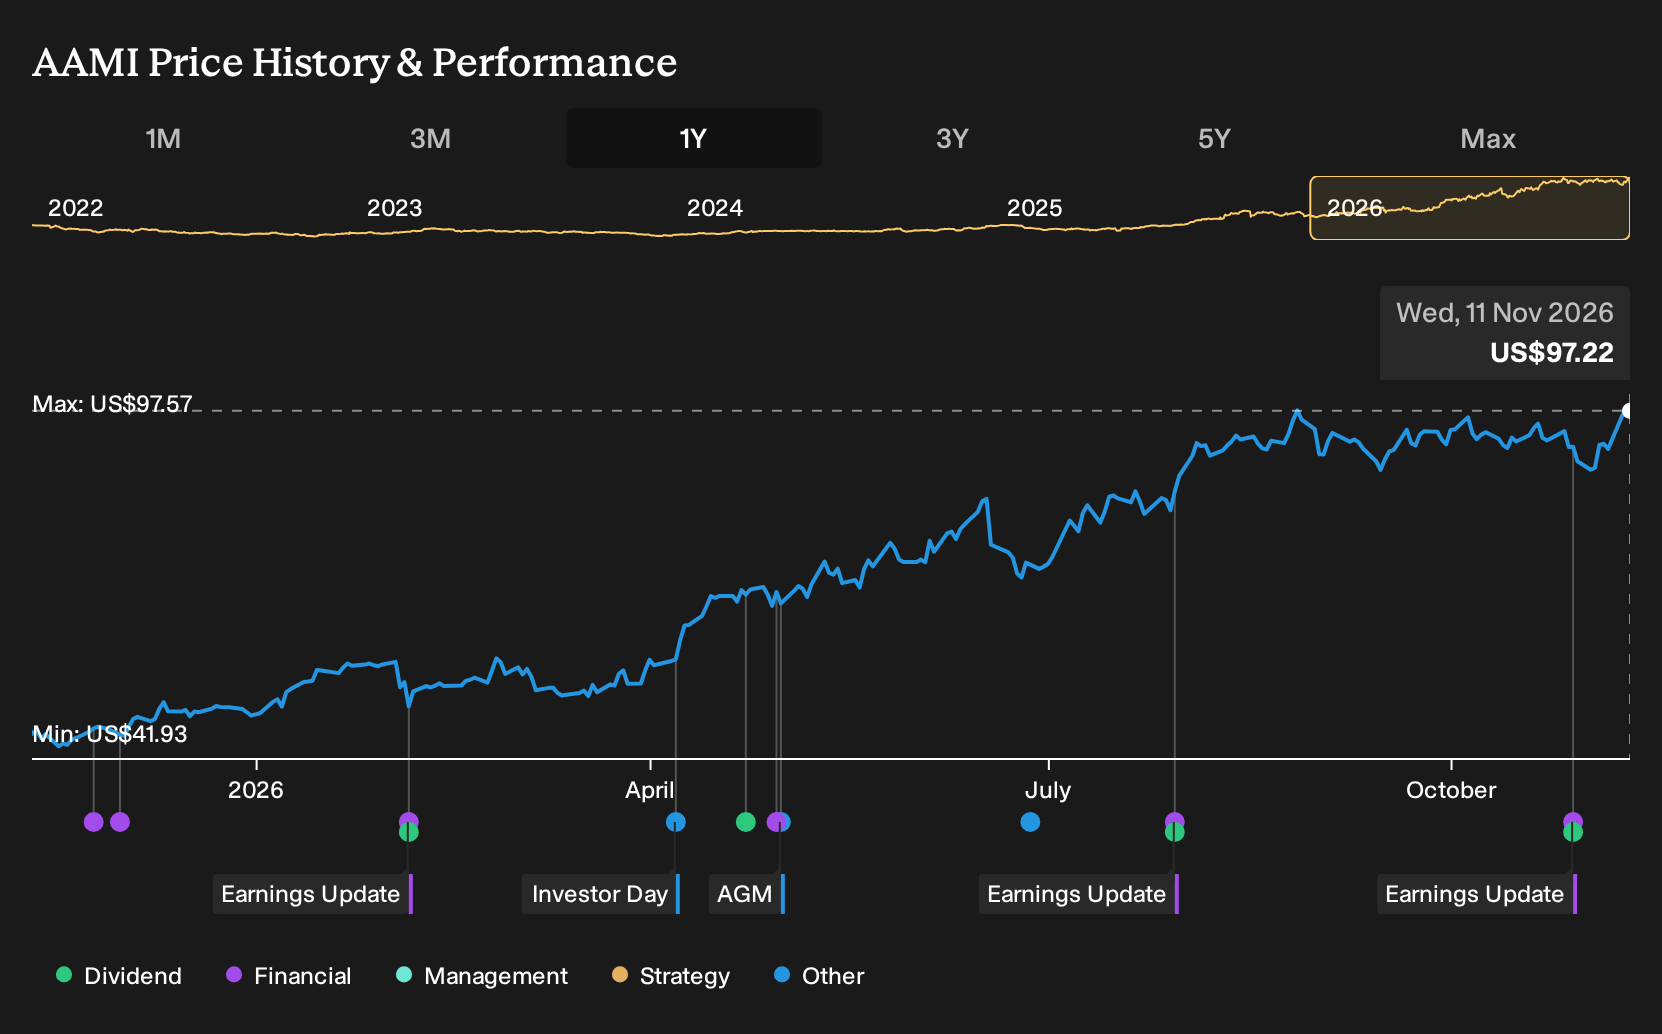
- Acadian Asset Management reported third quarter 2026 results with sales of US$2.1 million, revenue of US$191.2 million, net income of US$35.5 million, and basic earnings per share from continuing operations of US$1. The company also confirmed a previously approved US$0.10 per share quarterly dividend, payable on December 23, 2026, to holders of record on December 11, 2026.
- The combination of higher revenue and net income, together with a maintained cash dividend, highlights how Acadian Asset Management is balancing profitability, capital returns, and shareholder income priorities in the current reporting period.
- This sets the context for examining how Acadian Asset Management's stronger third quarter earnings may influence the investment narrative around its dividend policy.
What Is Acadian Asset Management's Investment Narrative?
The big picture with Acadian Asset Management is simple. You need to believe this is a fee based, relatively low capital intensity business that can keep turning solid revenue into high return on equity while managing the lumpiness that often comes with market linked earnings. The third quarter print, with US$191.2 million in revenue and US$35.5 million in net income, points to strong execution on its core quant and solutions franchise and a business model that is still converting top line into profits.
The reaffirmed US$0.10 quarterly dividend matters because it shows management is comfortable pairing that profitability with ongoing cash returns right now, rather than focusing only on growth. In the near term, key catalysts are likely to center on client flows, fee rates, and how much of current earnings quality is cash based, given the flagged high level of non cash items and a five year history of earnings decline. That places more emphasis on how you interpret this latest quarter in the broader Acadian Asset Management story than on the small discount to the current analyst price target.
Yet, set against this stronger quarter and steady dividend, one awkward thread still runs through the Acadian Asset Management equity story that...
There's only one way to know the right time to buy, sell or hold Acadian Asset Management. Head to Simply Wall St's company report for the latest analysis of Acadian Asset Management's Fair Value.
Reach Your Own Conclusion
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Acadian Asset Management research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Acadian Asset Management. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Acadian Asset Management's overall financial health at a glance.
Looking For More Investment Ideas Beyond Acadian Asset Management?
If you want to pressure test your view on Acadian Asset Management against a wider opportunity set, the Simply Wall St Screener can help you quickly surface other stocks that fit different income, quality, or risk profiles.
- If you care most about valuation and financial resilience, focus on companies that combine supportive cash flows with balance sheet strength by running a screen built around 32 high quality undervalued stocks.
- For investors who want income without ignoring financial footing, you can filter for payout strength and balance sheet quality through a curated 6 dividend fortresses.
- If capital preservation is front of mind, you can narrow your search to financially resilient businesses with steadier profiles by starting with a 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com