


EN
3 Dividend Stocks With Yields Over 3%
The recent closure of the Strait of Hormuz has put energy security and reliable cash flows back in the spotlight, as investors watch how essential infrastructure keeps running when supply chains are stressed. Regular income starts to look more attractive when headlines focus on disruption. That is where high yielding, well covered dividend payers come in. This article highlights three dividend heavyweights from our yield focused screener that aim to provide steady income.
The three stocks highlighted here offer a compelling starting point if you want exposure to higher yielding dividend payers with an emphasis on coverage and stability. However, if you want the standouts, these 6 dividend aristocrats stocks are the most outstanding.
BankUnited (BKU)
BankUnited fits the Dividend Powerhouses theme because its regular cash payouts are closely tied to deposit gathering and lending, giving you income backed by everyday banking activity rather than one off windfalls, according to the analyst consensus Narrative on Simply Wall St.
"Sustained net deposit growth driven by onboarding new client relationships has increasingly centered on commercial non interest bearing balances, with non interest bearing deposits of about US$9.935b representing 34.4% of total deposits by Q2 2026. Continued investment in fee-based and specialty deposit businesses such as title and HOA deposits, alongside capital markets activity, is widening non interest income sources and deepening commercial operating balances."
What happens to dividend comfort if a single key assumption about that funding mix or pricing power stops holding up?
If that comfort level matters to you, the full narrative for BankUnited shows how BankUnited’s funding mix, fee engines and dividend path could be decoupling from simple rate cycle headlines.

Brown-Forman (BF.B)
Brown-Forman brings the Dividend Powerhouses theme into the real world through a global portfolio of spirits that throws off cash from everyday consumption, and the bullish analyst Narrative on Simply Wall St focuses on how that engine could keep supporting a covered, growing payout.
"Expansion of smaller bottle sizes across Brown-Forman’s core premium brands, with these formats growing faster than larger bottles as value-conscious consumers downsize to stay with preferred labels, could support unit volumes while sustaining higher price points per litre and help protect gross margins."
What happens to dividend comfort if one quiet shift in how Brown-Forman funds and prioritises its growth starts to squeeze those margins?
Brown-Forman is a Louisville based producer of spirits and related beverages, anchored by Jack Daniel’s and other whiskey and tequila labels. It generates about US$3.9b from beverage alcohol consumer products and carries a market value near US$14.3b, which underpins its role in a 3%+ yield income screen.
That margin pressure question is exactly where the full narrative for Brown-Forman shows how Brown-Forman’s cash engine, capital choices and dividend ambitions could be quietly accelerating or stalling beneath the surface.
Bank OZK (OZK)
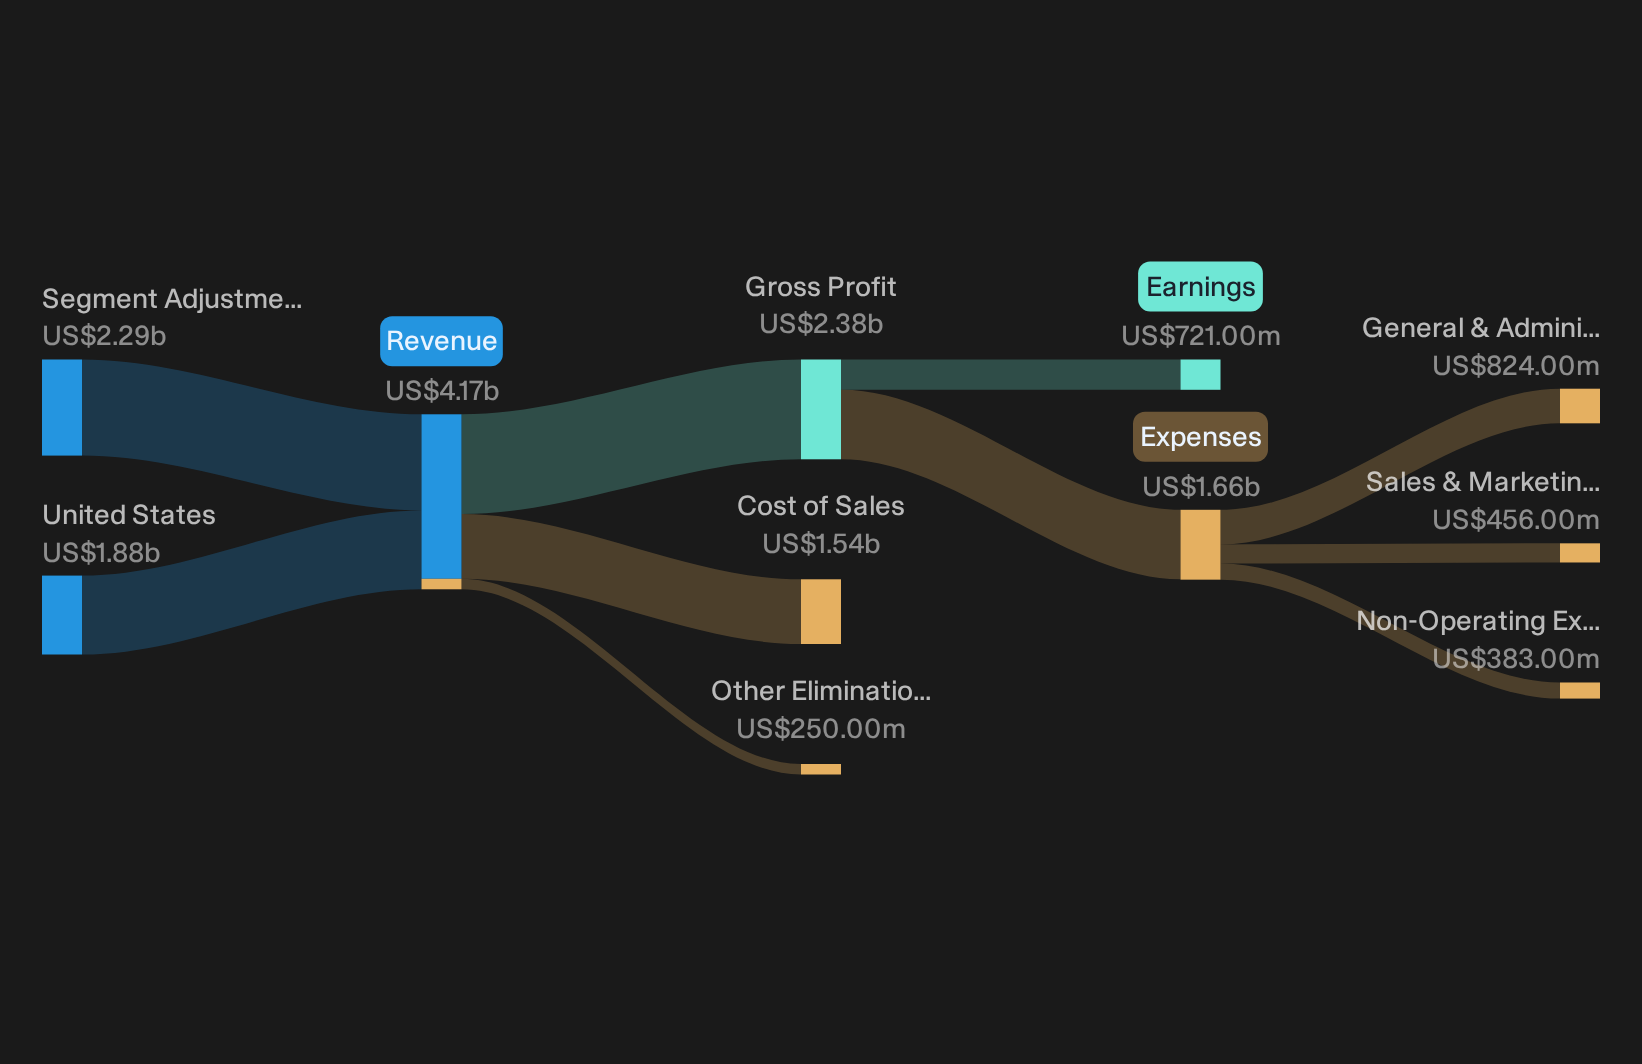
Bank OZK is a full service lender built around community banking, commercial real estate and consumer credit, where interest income and recurring fees help support a covered 3%+ yield. It generated about US$1.5b from community banking in the United States and carries a market value near US$5.5b.
For income focused investors, Bank OZK brings a mix of traditional community banking and a growing corporate platform, and the analyst consensus Narrative on Simply Wall St argues that this combination is central to how its dividend is supported over time.
"The accelerated buildout of the Corporate and Institutional Banking platform, which now spans more than seven lending verticals and over 42 industry niches and is expected to reach a portfolio size similar to RESG by 2027, is set to increase floating rate lending spreads and fee income from roles as administrative agent or joint lead on single lender and small club deals. This supports net interest margin and noninterest revenue."
What happens to that income story if one shift in where Bank OZK finds its next wave of fee based relationships plays out differently than expected?
If that shift in fee based relationships is on your mind, the full narrative for Bank OZK shows whether Bank OZK’s expanding platform is quietly accelerating or masking risk.

Seeking Alternatives Before Momentum Flies
Fresh ideas often move first when momentum builds and quiet winners can break out under the radar. Screen them before the crowd catches up and consider your options early.
- Explore resilient payout streams by scanning a curated 6 dividend fortresses while yields still reflect today’s prices rather than future headlines.
- Review potential structural demand shifts with a focused 42 power grid technology and infrastructure stocks before more capital targets the grid upgrade theme and valuations adjust.
- Evaluate opportunities ahead of a potential materials cycle by checking the hand picked 16 top copper producer stocks while supply developments are still being incorporated into prices.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com