


EN
Siltronic Stock Earnings Loss Widens Despite Higher Sales
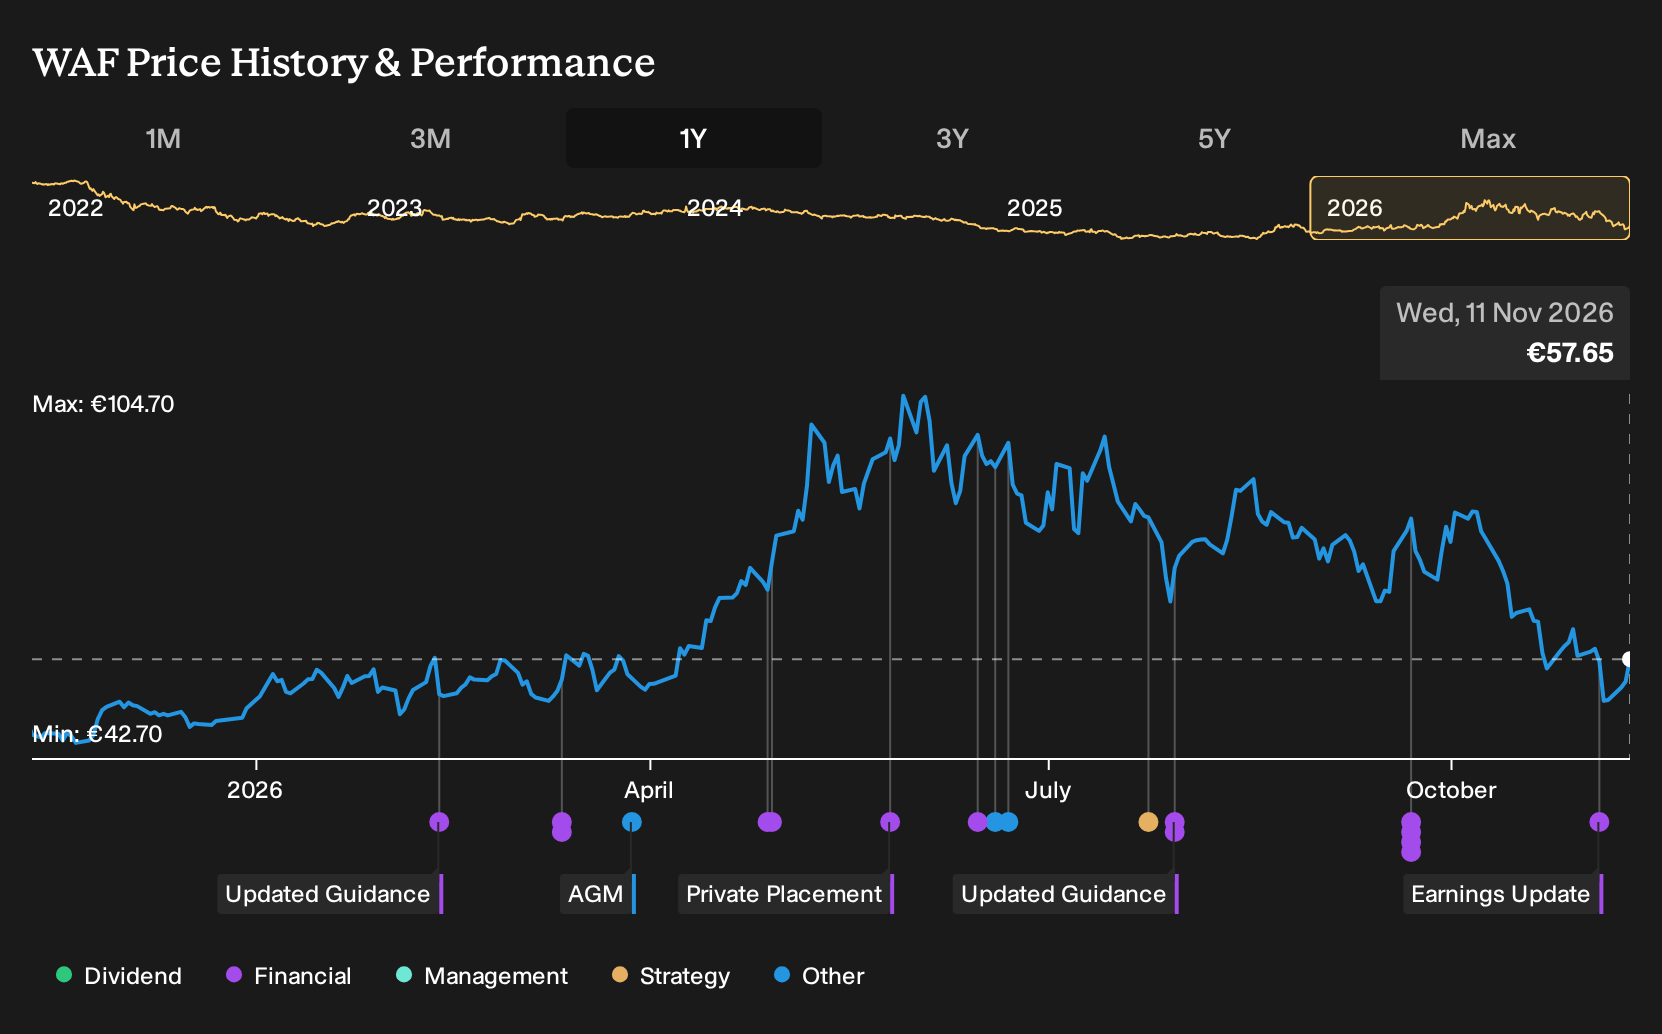
- Siltronic reported results for the third quarter and first nine months of 2026, with sales of €355.4 million and €983.5 million respectively, alongside net losses of €48.3 million and €158.1 million and higher basic loss per share in both periods compared with a year earlier.
- The combination of higher revenue and deeper losses suggests rising costs or margin pressure inside Siltronic's wafer business. This puts the focus on how efficiently the company is running its capacity and managing expenses during this phase of the semiconductor cycle.
- We will now look at how Siltronic's larger nine month loss, despite higher sales, could reshape the broader investment narrative.
Scan beyond Siltronic's deeper losses to see how other wafer and chip suppliers stack up on quality and resilience with the 208 resilient stocks with low risk scores.
Siltronic Investment Narrative Recap
To own Siltronic, you need to believe that a concentrated wafer supplier with high fixed costs can benefit when volumes and pricing improve. According to European_Hidden_Gem_Stocks, a Simply Wall St Community investor who wrote the Narrative, the key levers are wafer pricing, Singapore utilisation and long term contract terms. The latest quarter, with deeper losses alongside higher sales, keeps the focus squarely on cost discipline and how quickly new capacity can earn its keep.
The most important short term catalyst remains better utilisation of FabNext and existing 300mm lines, which could lift earnings power if pricing and volumes hold up. The biggest risk right now is that wafer demand or pricing does not firm enough to cover the heavy depreciation and interest burden, extending the period of reported losses. This earnings update reinforces that risk but does not radically change it.
European_Hidden_Gem_Stocks argues that Siltronic sits in an oligopolistic wafer market where recent investment in Singapore is already largely spent and depreciation now runs ahead of current cash outflows. The third quarter figures, with €355.4 million of sales but a €48.3 million net loss, make that income statement and cash flow gap very visible. For you, the question is whether that accounting drag is a temporary phase or a sign of structurally weaker returns.
With no fresh corporate announcements alongside these results, the most relevant reference point is the existing guidance framework cited in the Narrative, including expected 2026 EBITDA of €260 million to €320 million and depreciation of €490 million to €520 million. The nine month loss of €158.1 million underlines how dependent the story is on getting FabNext utilisation and wafer pricing to levels that support those medium term margin ambitions and reduce the risk of prolonged losses.
European_Hidden_Gem_Stocks reaches a fair value of €138.26 per share for Siltronic by applying a discounted cash flow style framework that assumes revenue rising 10.0% a year and a future profit margin stabilising at 16.8% once FabNext and the wider wafer cycle are running closer to their intended economics.
Uncover why Siltronic's fair value indicates a 140% potential upside to its current price and a discount that could close faster than you expect.
Exploring Other Perspectives
One alternate take on Siltronic leans hard into pricing risk. The lowest analysts were already working with about 9.5% annualised revenue growth to roughly €1.7b and earnings of €271.6 million by 2029 before this earnings release. That is still framed as a constrained recovery, which shows how far views can diverge. You can use those more cautious assumptions as a reference point and then decide where your own expectations sit after this latest loss update.
Explore 6 other Siltronic fair value estimates, including one that suggests it could be worth just €60.62.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Siltronic research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Siltronic. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Siltronic's overall financial health at a glance.
Looking for more Siltronic-sized investment ideas?
If this Siltronic update has sharpened your thinking on risk, reward and balance sheets, you can use that same lens across the wider market with the Simply Wall St Screener.
- For investors who care most about downside protection, start with companies that score well on resilience and risk, using the 208 resilient stocks with low risk scores.
- If value is your main filter, focus on businesses that combine quality fundamentals with prices that look undemanding through the 196 high quality undervalued stocks.
- To round out your watchlist with lesser known ideas, search for underfollowed companies that still have solid financial footing via the 562 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com