


EN
How Raised Guidance Will Impact Covista Stock Investors
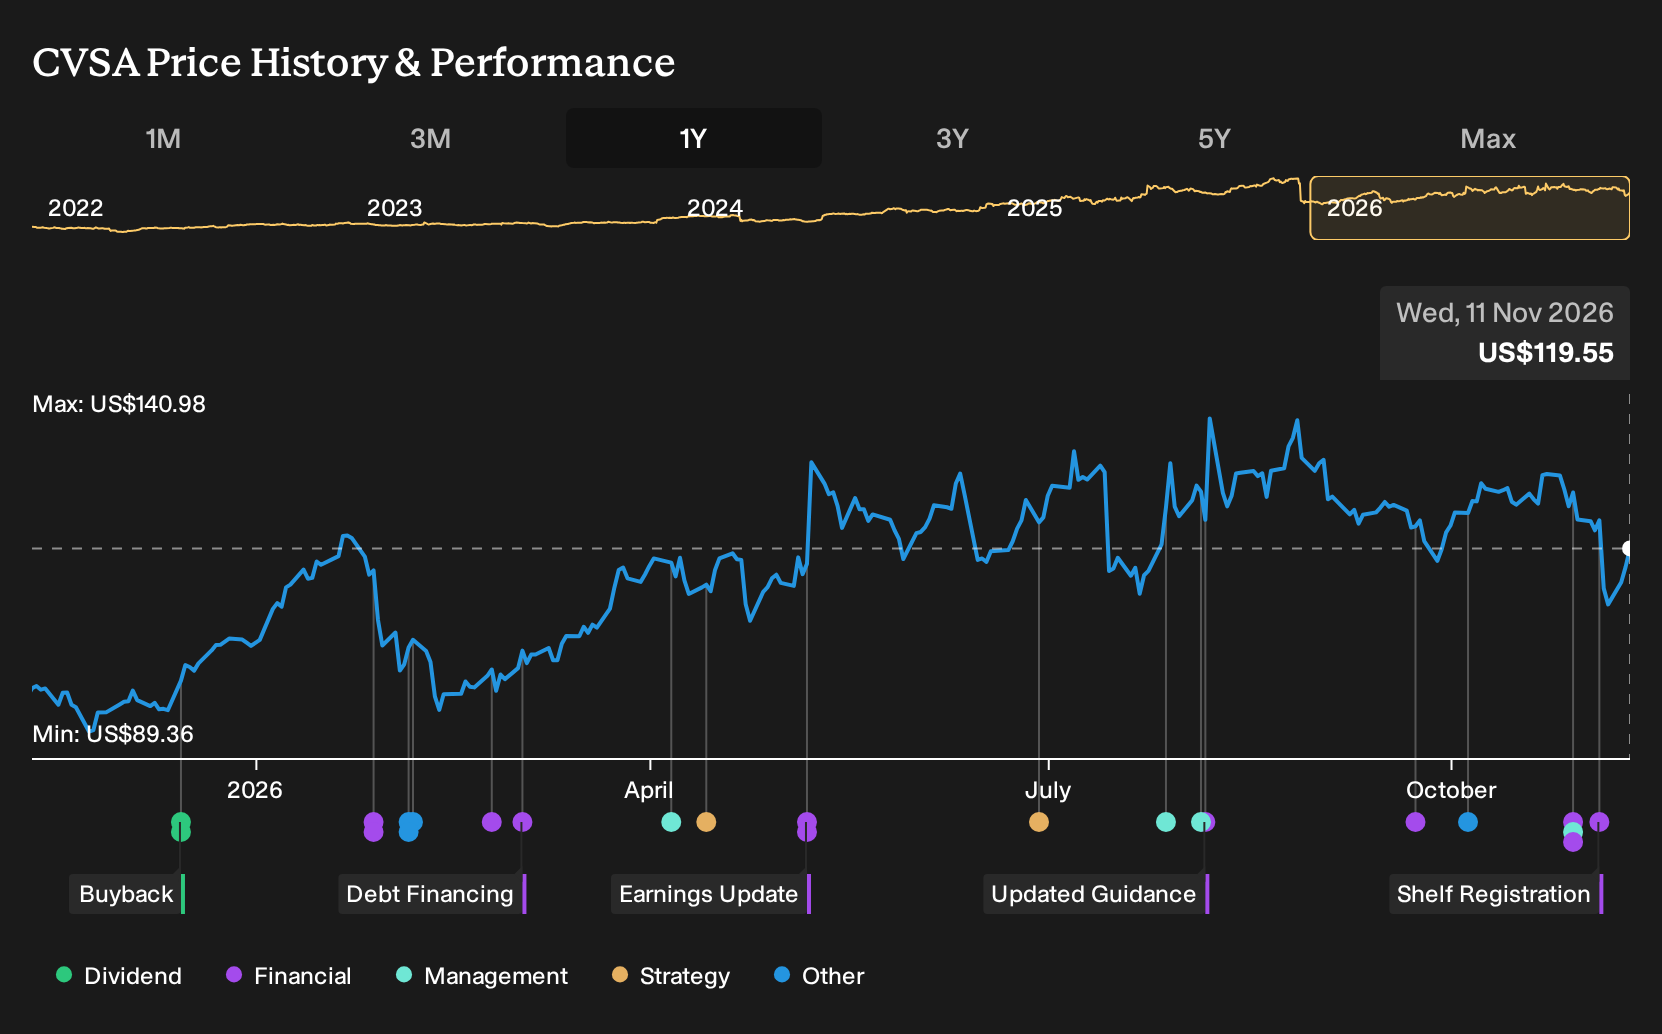
- Covista reported first quarter sales of US$511.53 million and net income of US$67.43 million, raised 2027 revenue guidance to a range of US$2,060 million to US$2,095 million, filed a US$257.313 million shelf registration for 2,100,000 common shares related to its ESOP, and confirmed a planned CFO retirement.
- The combination of higher earnings guidance and ESOP linked capital flexibility, together with ongoing share repurchases totaling 1,528,378 shares for US$172.18 million, highlights how Covista is actively managing both growth investment and its share count.
- The next step is an assessment of how Covista's updated revenue outlook could interact with the existing investment narrative built around health care education demand.
Scan how Covista's capital moves compare to peers by jumping into a curated list of companies with disciplined balance sheets and fundamentals through the list of solid balance sheet and fundamentals (24 results).
Covista Investment Narrative Recap
To own Covista, you need to believe that demand for healthcare education and flexible online programs stays resilient and that capacity investments in Chamberlain, Walden and Med/Vet eventually support steadier enrollment and margins. The raised 2027 revenue guidance and solid first quarter earnings suggest the operating plan remains intact, so the near term catalyst still sits in sustained enrollment conversion rather than this guidance tweak.
The biggest operational risk right now remains any slowdown in student demand tied to funding, student loan regulation or pressure at Chamberlain, where management has flagged softer total enrollment and margin strain from support spending. The ESOP linked shelf and ongoing buybacks matter more for per share math than for day to day operating performance, so they are secondary to execution on student growth.
The most relevant update for the current thesis is the higher 2027 revenue range of US$2,060 million to US$2,095 million. That change is modest versus the prior US$2,050 million to US$2,090 million band. It also lines up with the analyst consensus Narrative on Simply Wall St, which already leaned on steady mid single digit top line expansion supported by healthcare workforce needs and digital learning adoption.
For you as a shareholder, the key question is how this increment in guidance interacts with the existing catalysts around capacity expansion, online scale and enrollment funnel work at Chamberlain and Walden. If those initiatives translate into stable cash generation, Covista’s ability to keep funding campus build outs and technology, while having already retired 1,528,378 shares for US$172.18 million, stays intact and supports the long term execution story.
Covista's narrative projects US$2.4b revenue and US$362.8 million earnings by 2029. This assumes 7.4% yearly revenue growth and an earnings increase of about US$95 million from current earnings of US$267.4 million.
Uncover why Covista's fair value indicates a 33% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view on Covista leans into margin risk rather than revenue upside. The most cautious analysts were already penciling in 2029 earnings of about US$353.2 million on roughly US$2.4b revenue before this guidance and ESOP shelf news. That lower earnings path implies tighter profitability and shows how far opinions can stretch. Use it as a prompt to compare several narratives and decide which assumptions you find more reasonable, knowing both sets of forecasts pre date the latest updates.
Explore 2 other Covista fair value estimates, including one that suggests it could be worth just $159.00!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Covista research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Covista. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Covista's overall financial health at a glance.
Looking For More Investment Ideas Beyond Covista?
If Covista has sharpened your thinking about what you want in a business, use that same filter to scan a broader opportunity set. The Simply Wall St Screener lets you jump straight into groups of companies that match specific traits, so you can compare Covista side by side with other candidates instead of looking at it in isolation.
- For investors who want potential mispricing with quality in mind, start with a focused list built around 32 high quality undervalued stocks and see which businesses meet a higher fundamental bar.
- If resilience matters more than excitement, steer toward companies that have steadier finances and risk characteristics through the 30 resilient stocks with low risk scores to round out your watchlist.
- If you prefer to hunt for opportunities that are not already crowded, use the 19 high quality undiscovered gems and look for solid fundamentals where attention has been slower to catch up.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com