


EN
Bank of Montreal (TSX:BMO) Rolls Out AI Agent Assist On A Narrative Of Modest Undervaluation
Bank of Montreal (TSX:BMO) has rolled out its AI Agent Assist tool inside its Virtual Connect contact centre, targeting faster credit card inquiry handling and more consistent service for Canadian clients.
Against this backdrop of AI rollouts and credit card product tweaks, Bank of Montreal’s shares trade at CA$247.75, with a 1 month share price return of 6.74% and a year to date share price gain of 36.42%. The 1 year total shareholder return of 44.45% and 3 year total shareholder return above 150% point to strong existing momentum that recent AI and funding moves may be reinforcing rather than creating from scratch.
Scan how Bank of Montreal’s AI push compares with other financials leaning into automation by reviewing the hand picked 53 AI infrastructure stocks that is shaping the next wave of banking efficiency.
For Bank of Montreal, the recent AI and funding news could be a mirror of real business strength or just a surge in enthusiasm around the story. The valuation section tests which explanation fits better.
Most Popular Narrative: 2.9% Undervalued
Against Bank of Montreal’s last close at CA$247.75, the analyst consensus Narrative on Simply Wall St anchors fair value at about CA$255. This small gap presents the AI and U.S. expansion story as a modest undervaluation rather than a deep discount.
Bank of Montreal’s portfolio optimization and capital recycling, including 2026 sales of non core U.S. branches, transportation and vendor finance businesses and its Moneris stake that are expected to add about 50 bps to CET1, create scope for higher return capital deployment and share repurchases, which can support ROE, EPS and valuation.
See why 102 investors see Bank of Montreal as 3% undervalued.
Result: Fair Value of CA$255.07 (UNDERVALUED)
Still, the current narrative on Bank of Montreal could be challenged if credit costs rise faster than expected, or if technology spending weighs on efficiency for longer than analysts anticipate.
Find out about the key risks to this Bank of Montreal narrative.
Another View: Bank of Montreal Through Earnings Multiples
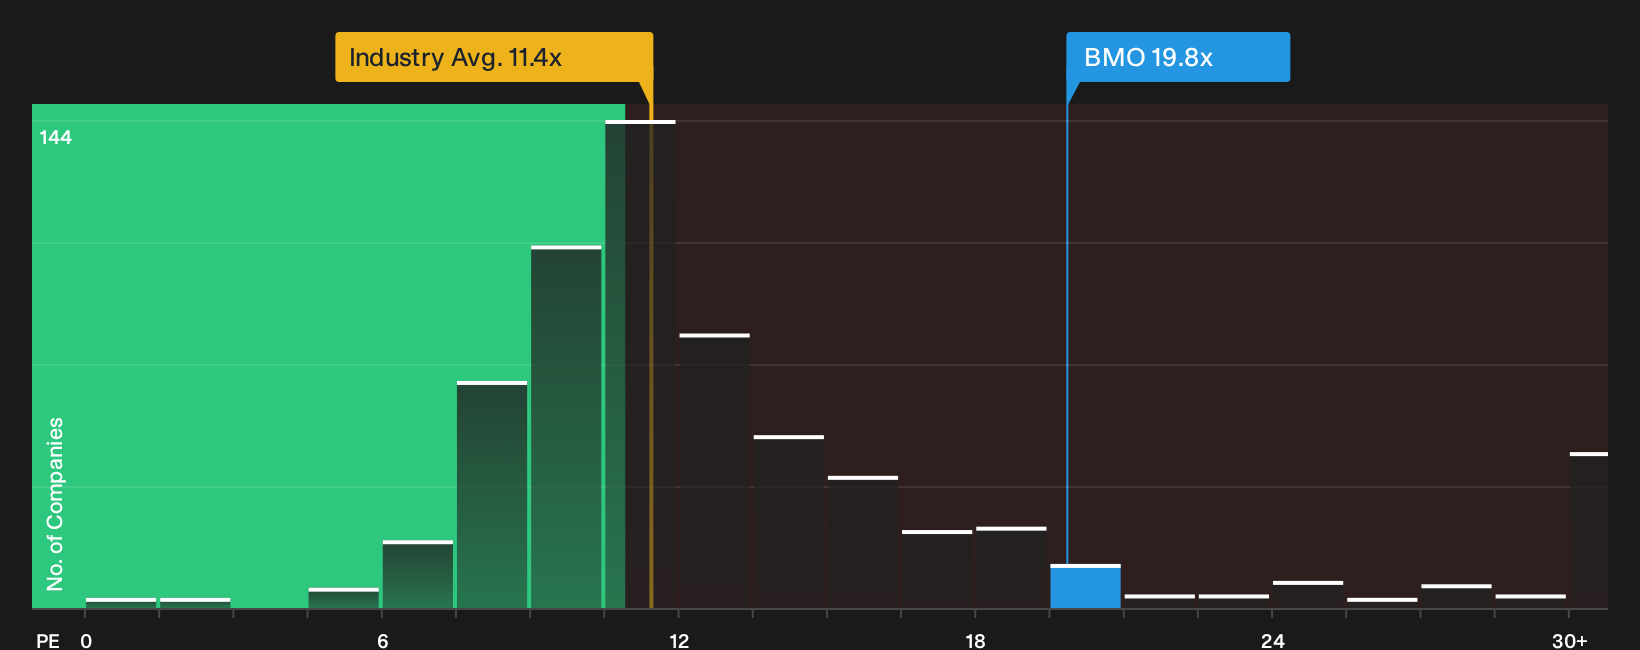
On simple earnings math, Bank of Montreal screens as expensive. The current P/E of 19.8x sits well above the North American banks group at 11.4x, the peer pack at 17.2x, and even above its own fair ratio of 18.8x. This raises the risk that sentiment, not fundamentals, is doing more of the heavy lifting than DCF suggests.
For investors weighing that gap between story and numbers, the question is whether today’s richer multiple represents a cushion of confidence or a margin of error if expectations ease.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Bank of Montreal so far. If you want to move quickly and form your own view, you can review the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Bank of Montreal?
If you want to cast the net wider than Bank of Montreal, use these hand picked screeners to spot opportunities that might suit your style before others catch on.
- Target resilient potential by scanning a 9 resilient stocks with low risk scores that can help you focus on businesses with steadier profiles when markets feel unpredictable.
- Hunt for value by reviewing a 5 high quality undervalued stocks that combines quality fundamentals with prices that may not fully reflect the underlying strengths.
- Build income focused watchlists through a 3 dividend fortresses that highlights companies offering higher yield while still aiming to keep payouts supported.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com