


EN
Credo Technology Group Holding (CRDO) Could Be 34% Below Fair Value Following AI Rally
Credo Technology Group Holding (CRDO) has moved back into focus after a sector wide rally in AI infrastructure suppliers, sparked by CoreWeave’s raised outlook and substantial backlog for data center buildouts.
For investors watching Credo Technology Group Holding over more than a single session, the picture is mixed. The 1-day share price return of 8.98% and 7-day gain of 3.63% suggest momentum has picked up again, even though the 30-day and 90-day share price returns declined 29.57% and 46.82% respectively as enthusiasm around AI infrastructure cooled earlier in the year. Despite that reset, the year to date share price move is only down 1.23%, and the total shareholder return over three years is about 7x. This indicates that the latest rally tied to CoreWeave’s outlook and Credo’s own AI related wins is being judged against a long track record of strong wealth creation and recent questions about how durable that earlier surge was.
Scan the AI connectivity trade beyond Credo Technology Group Holding by reviewing our hand picked list of 53 AI infrastructure stocks that are powering the same buildout theme.
The recent jump in Credo Technology Group Holding after months of sharp share price declines sets up a harder question: Does the current valuation still compensate you for AI demand risk and execution swings, or has the easy upside already been taken?
Most Popular Narrative: 34% Undervalued
On the narrative view, Credo Technology Group Holding is assessed with a fair value of $215 per share, compared with the latest close at $141.46, which puts valuation firmly in focus for anyone tracking the AI connectivity theme. According to Womble, an investor in the Simply Wall St Community who set out a detailed thesis on Credo, the key question is whether the business can keep converting AI infrastructure demand into sustained growth while justifying a high valuation.
Credo Technology Group is a high-growth semiconductor connectivity company benefiting from the expansion of AI infrastructure, data centres and high-speed optical and electrical networking. Q1 FY2027 revenue increased 114.7% year over year to $479.0 million, while Q2 revenue guidance of $525 to $535 million implies another approximately 9.6% to 11.7% sequential increase. The thesis depends on Credo converting AI-related demand into sustained growth, maintaining high margins, broadening its customer base and continuing to develop its optical, cable, retimer, DSP and PCIe product portfolio.
See why 26 investors see Credo Technology Group Holding as 34% undervalued.
Result: Fair Value of $215 (UNDERVALUED)
Still, the bullish Credo Technology Group Holding narrative leans heavily on AI infrastructure demand remaining intact, while any drop in revenue growth or margins could quickly challenge it.
Find out about the key risks to this Credo Technology Group Holding narrative.
Another View: Credo Technology Group Holding Through The P/E Lens
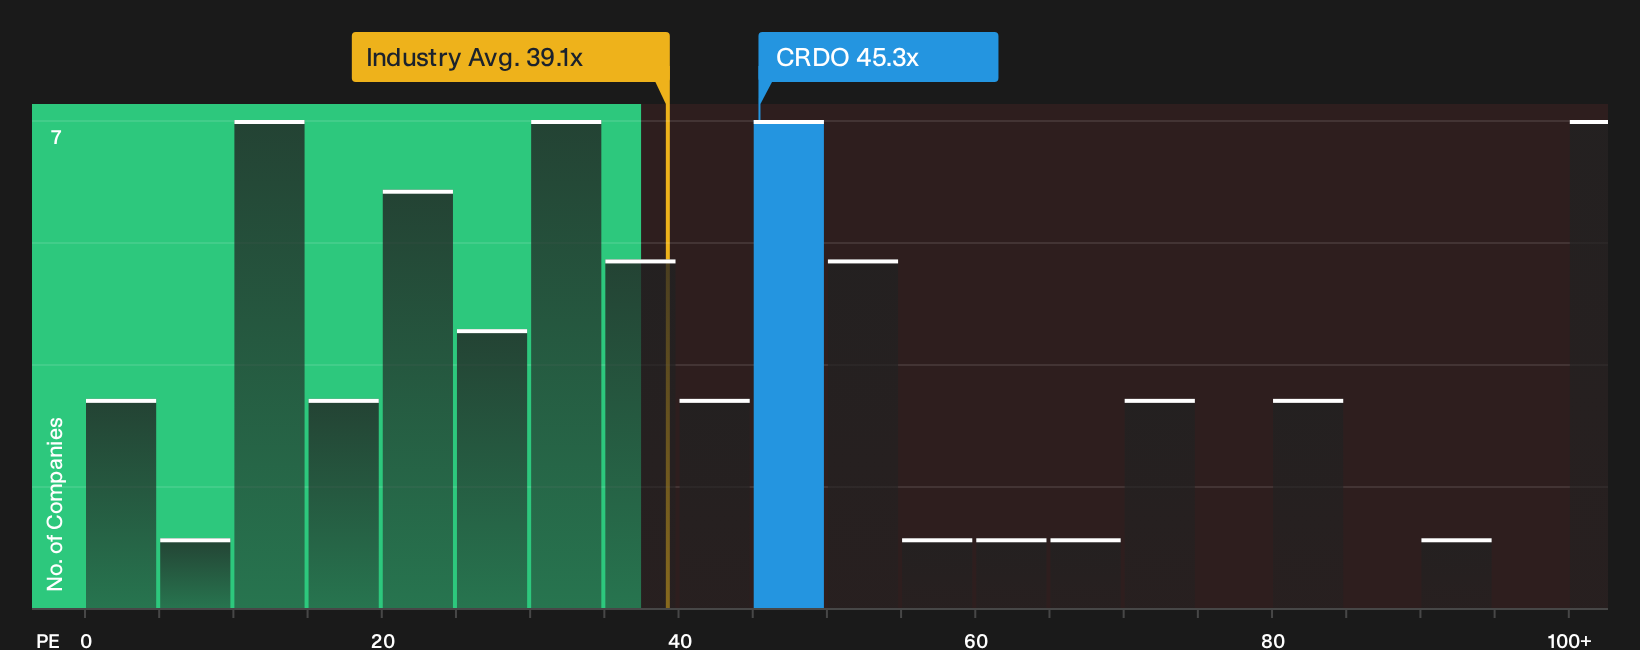
Credo Technology Group Holding may look cheap against a $215 fair value narrative, yet the P/E story is less relaxed. The stock trades at 45.3x earnings, above the US Semiconductor average of 39.1x and slightly ahead of a 44.8x fair ratio. That kind of premium can reward patience if execution stays exceptional, but it raises the question of how comfortable investors are paying up when the market could drift back toward that fair ratio.
To see what the numbers say about this valuation gap, and how it could close in either direction, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Credo Technology Group Holding is clearly split, with both strong AI optimism and meaningful execution questions in play, so move fast and stress test the data for yourself while this setup is still fresh. To weigh those positives against the issues investors are flagging, start with a clean snapshot of 4 key rewards and 2 important warning signs.
Looking for more ideas beyond Credo Technology Group Holding?
If you stop with Credo, you risk missing other opportunities setting up right now. Use the Simply Wall Street Screener to turn today’s curiosity into a broader watchlist of potential investments that actually fit your style and risk tolerance.
- Target potential mispricings by reviewing our hand picked list of 36 high quality undervalued stocks that could offer more compelling entry points than the headlines suggest.
- Build a more resilient portfolio by scanning a list of solid balance sheet and fundamentals (24 results) that can help you focus on businesses with the financial strength to handle tougher conditions.
- Spot early stage potential by checking out a 20 high quality undiscovered gems that many investors may not be watching yet but still show solid fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com