


EN
Is Chefs' Warehouse (CHEF) Pricey After Raising Guidance And Posting Strong Third Quarter Results?
Chefs' Warehouse (CHEF) is back in focus after the distributor lifted its full year 2026 earnings outlook and paired that update with fresh third quarter results showing higher sales and net income versus last year.
Chefs' Warehouse shares traded at US$108.18 after the update, with a 7 day share price return of 7.16%. This follows a year to date share price gain of 73.39% and a 5 year total shareholder return of 225.16%, suggesting momentum has been building over a longer stretch, even though the 30 day share price return declined 5.37%.
Scan for other food distribution and consumer staples stocks showing similar earnings strength to Chefs' Warehouse by running the curated list of solid balance sheet and fundamentals (24 results).
Bulls see Chefs' Warehouse earning its premium after the guidance lift and strong quarter. Skeptics see a hot stock pricing in too much. The valuation work shows which side current numbers support.
Most Popular Narrative: 11% Undervalued
Chefs' Warehouse is priced at $108.18, while the analyst consensus Narrative on Simply Wall St assigns a fair value of $122 using a 7.28% discount rate. This frames the current setup as roughly 11% undervalued on that model.
The main thing that has to go right is continued execution on scaling the specialty broadline distribution model in underpenetrated markets like Texas and Florida while maintaining discipline on capital allocation. The goal is for rising route density and maturing sales teams to support the higher long-term revenue and EBITDA margin targets.
See why 6 investors see Chefs' Warehouse as 11% undervalued.
Result: Fair Value of $122 (UNDERVALUED)
Still, the Chefs' Warehouse story can break if cost inflation squeezes that 25.1% gross margin or if supply chain rerouting continues to weigh on profitability.
Find out about the key risks to this Chefs' Warehouse narrative.
Another View: Multiples Paint A Richer Price Tag For Chefs' Warehouse
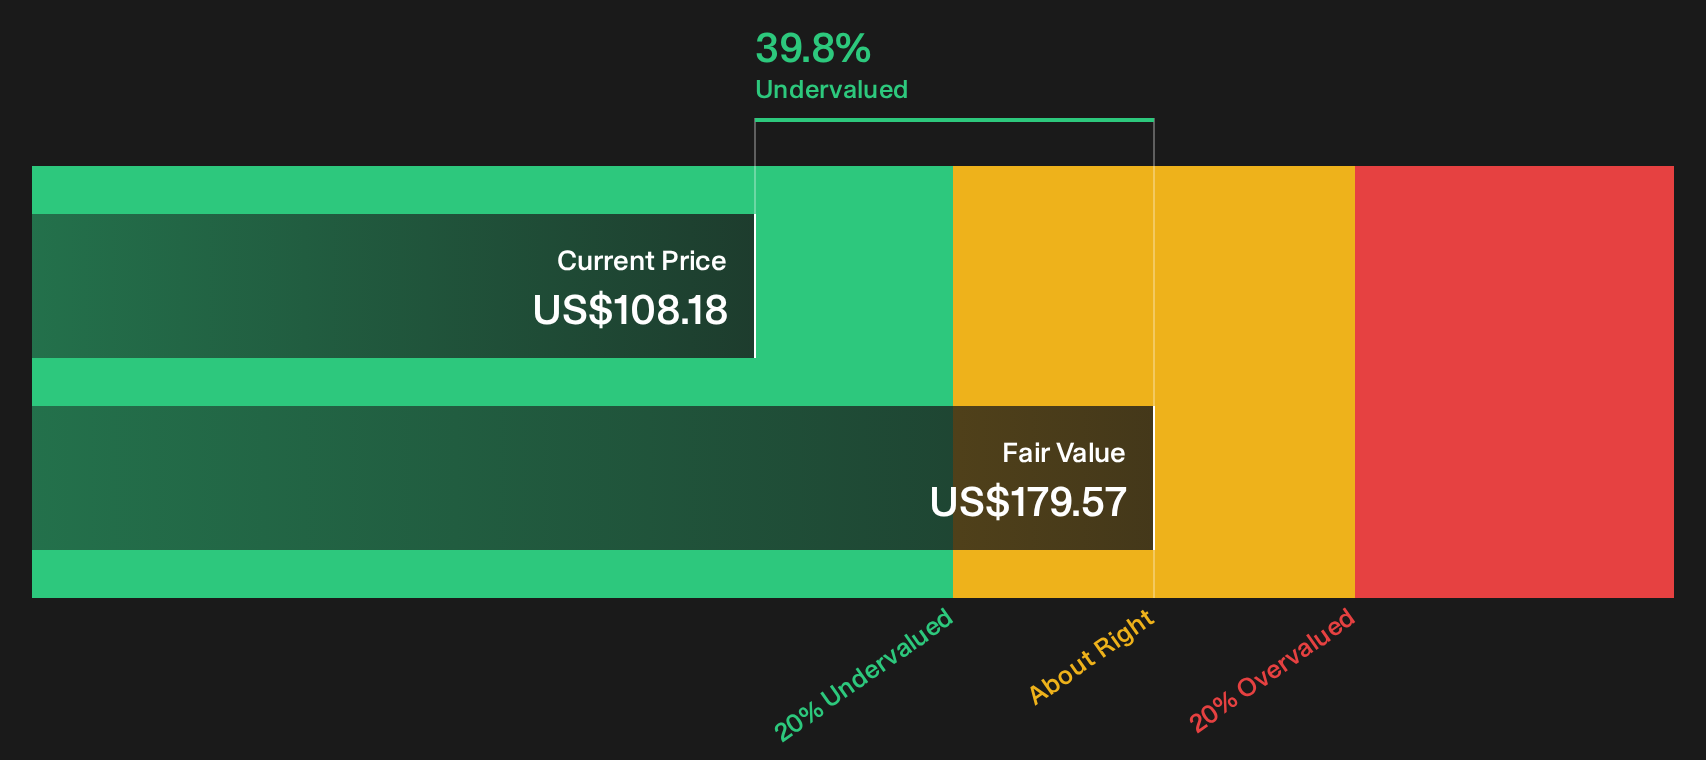
The DCF work points to Chefs' Warehouse trading at roughly a 39.8% discount to an estimated future cash flow value of $179.57, which suggests upside on that lens. Yet the P/E ratio of 45.9x sits far above the US Consumer Retailing average of 18.3x and the peer average of 29.2x, and it exceeds a fair ratio of 23.1x. That gap implies investors are already paying a high premium for execution, so the key consideration is whether the current trajectory justifies keeping that multiple elevated.
For readers who want to see how this cash flow based result is built line by line, the SWS DCF model for Chefs' Warehouse is laid out in full detail in the Look into how the SWS DCF model arrives at its fair value.
Next Steps
Wondering whether the mix of optimism and concern around Chefs' Warehouse lines up with your own view of the risk reward trade off? Weigh the potential upside and the possible downside for yourself by checking the 3 key rewards and 2 important warning signs.
Looking for more ideas beyond Chefs' Warehouse?
If Chefs' Warehouse is on your radar after this update, do not stop here. Broader context across other opportunities often sharpens conviction and reveals better fits.
- Spot potential upside in quality names trading below their implied worth by sizing up the 35 high quality undervalued stocks that match your risk tolerance.
- Lock in steadier cash flows by scanning income-focused candidates with the help of the 5 dividend fortresses tailored for yield hunters.
- Guard against unpleasant surprises by filtering for financially resilient businesses through the 30 resilient stocks with low risk scores that keep balance sheet strength front and center.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com