


EN
Energy Transfer (ET) Stock Still Looks Undervalued After Recent Expansion Moves
Energy Transfer has delivered a powerful 221.8% total return over the past 5 years, which puts a spotlight on a different question today: whether the current unit price still lines up with the partnership’s earnings profile. Recent pipeline approvals, acquisitions and fresh debt financing mean investors are not just looking at a historical chart; they are weighing how this build out interacts with the profits that ultimately support the valuation.
- A 221.8% gain over 5 years raises the stakes on whether Energy Transfer’s current earnings justify the market value placed on its cash generating assets.
- The approved South Mississippi Pipeline, the planned Vaquero Midstream acquisition and the new senior notes offering can reshape future earnings by affecting growth opportunities, capital intensity and interest costs.
- Your read on Energy Transfer is one view; the desks covering it have another. See what analysts think Energy Transfer's shares could be worth.
The issue now is whether Energy Transfer’s present price is supported by its earnings when set against the Fair Ratio benchmark.
If you want to balance Energy Transfer’s earnings story with other ideas built on solid financial footing, a focused stock screen of solid balance sheet and fundamentals stocks screener (24 results) is a practical next step.
Is Energy Transfer Still Cheap on Earnings?
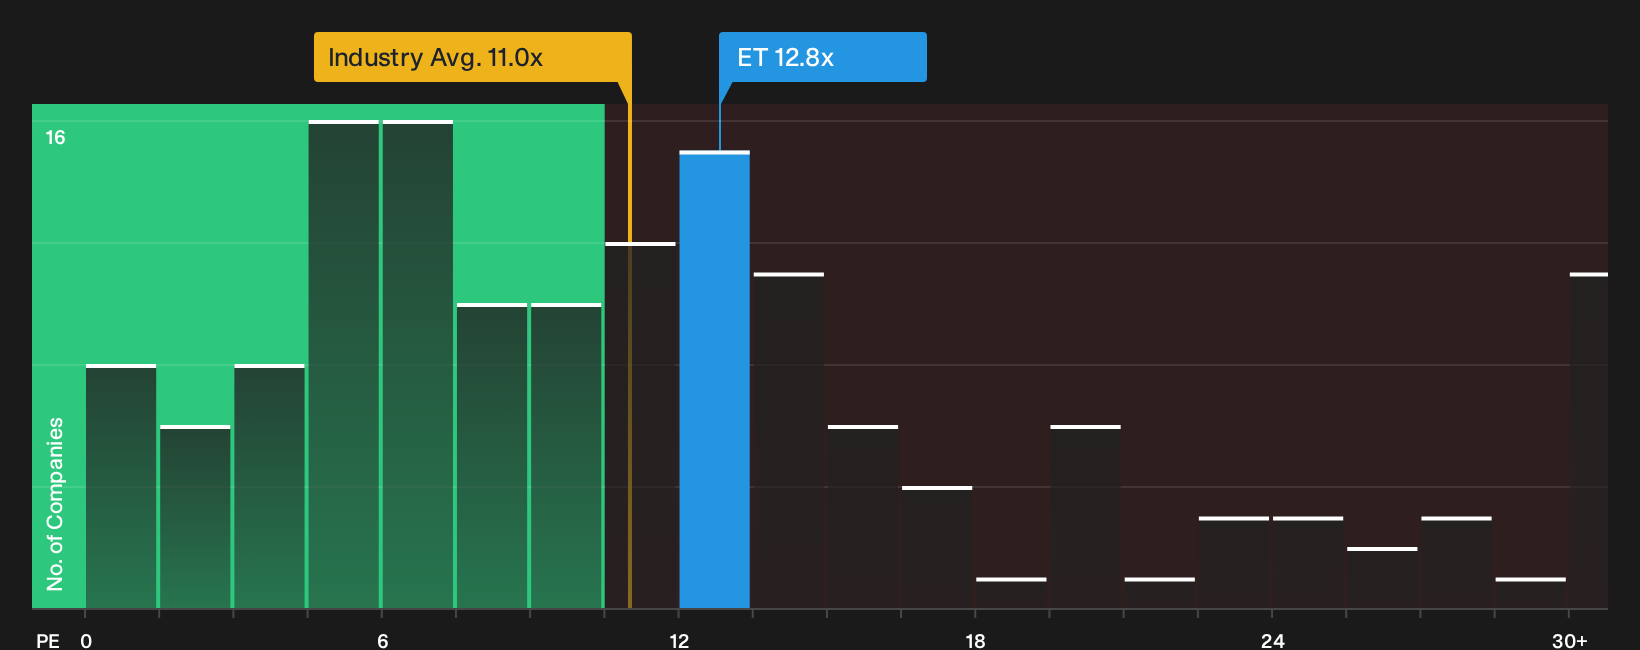
P/E suits Energy Transfer because earnings are a core yardstick for a mature pipeline partnership that already throws off meaningful cash. The units trade on a P/E of 12.8x, which is below the Oil and Gas industry average of 11.0x and sits at a wider discount compared with the broader peer group on roughly 21.1x. In that peer context, the stock is priced more like a traditional midstream utility rather than a higher growth pipeline platform.
The Fair Ratio, which reflects what investors might expect to pay given Energy Transfer’s risk profile, margins and scale, points to a richer multiple than the current 12.8x, so the units appear undervalued on this framework. Because the South Mississippi Pipeline approval and the Vaquero Midstream deal anchor long term contracts and volumes, the market is valuing that project pipeline at a discount to the earnings multiple implied by this tailored benchmark. Explore the numbers behind Energy Transfer's P/E valuation.
The Energy Transfer Narrative: What Would Justify Today's Price?
Narratives for Energy Transfer pick up where the valuation puzzle stops by spelling out which future paths for growth, margins and earnings would need to hold for the units to be worth materially more or less than today’s price. They sit on Simply Wall St’s Community page and turn a single ratio or model output into a clear set of underlying expectations, so you can see the future those numbers assume and watch how reality lines up over time.
One of the top narratives on Energy Transfer: 21% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"Recent long term customer commitments on multi billion dollar projects are now supported by more than 6 Bcf/d of contracted pipeline capacity with demand pull customers…"
Discover why this Narrative puts Energy Transfer at 21% undervalued.
The missing piece in Energy Transfer's story
Valuation shows what Energy Transfer looks like today, yet analyst models sketch where earnings, cash flow and balance sheet strength might head over the next few years. That forward map is the next thing to weigh. Explore where analysts expect Energy Transfer to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com