


EN
GEO Group (GEO) Could Be 22% Undervalued On ICE Contracts And Higher Guidance
GEO Group (GEO) is back in focus after securing fresh long term ICE contracts, an S&P Global Ratings upgrade, and higher earnings guidance that together are reshaping how investors view its operations and balance sheet.
GEO Group’s recent catalysts appear to be feeding straight into momentum, with the share price up 5.97% over the last day and a 7 day share price return of 13.79% pushing the stock to $31.94. The year to date share price return of 100.50% and a 1 year total shareholder return of 115.23% point to a powerful rerating that aligns with fresh ICE contracts, the shelf registration, and higher guidance.
Scan other detention and contracted government service plays that are showing strong contract momentum and balance sheet repair through our hand picked 30 resilient stocks with low risk scores while GEO Group heats up.
After a rapid move that already reflects fresh ICE contracts, a higher rating from S&P, and richer guidance, the key question is how much of GEO Group’s potential the current valuation already captures.
Most Popular Narrative: 22% Undervalued
Against a last close of $31.94, the analyst consensus Narrative on Simply Wall St anchors GEO Group’s fair value at $40.94. This implies a material gap that investors are now weighing against policy, contract, and balance sheet risks.
The federal funding package that provides ICE with multi year access to US$45b for detention expenditures and US$38.5b of broader funding is supporting ICE plans to increase total detention capacity toward 100,000 or more beds. This could allow GEO Group to activate additional contracted and idle facilities and lift revenue and adjusted EBITDA if its share of beds continues to rise.
See why 30 investors see GEO Group as 22% undervalued.
Result: Fair Value of $40.94 (UNDERVALUED)
Still, GEO Group’s reliance on large federal detention budgets, along with ongoing political and legal scrutiny around private facilities, could easily unsettle that undervaluation narrative.
Find out about the key risks to this GEO Group narrative.
Another View: GEO Group Through The P/E Lens
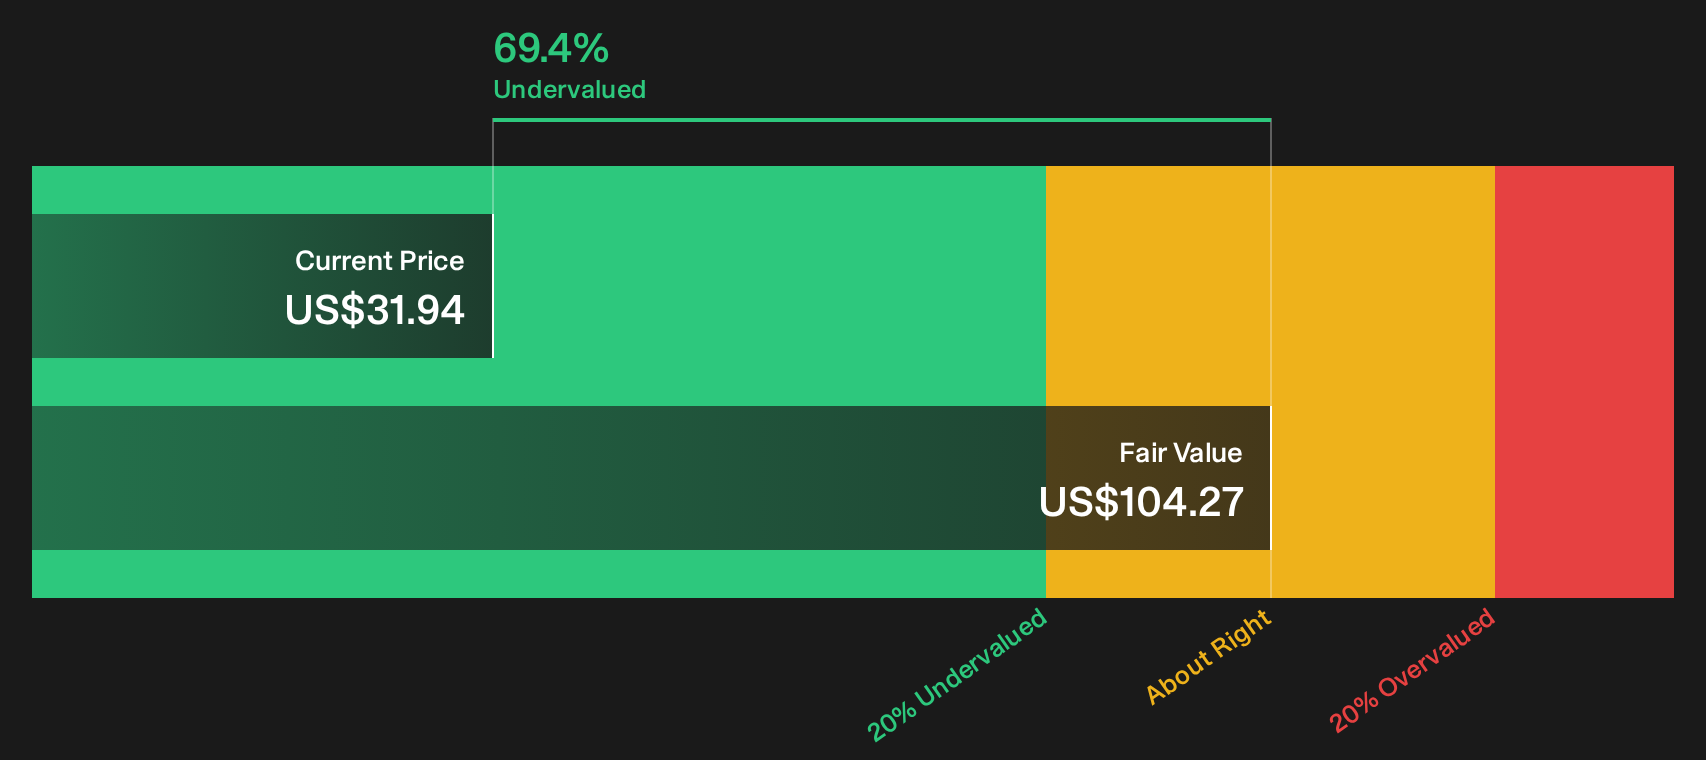
The SWS DCF model points to GEO Group trading 69.4% below an estimated future cash flow value of $104.27, which suggests a very different picture from a simple P/E snapshot. With that kind of spread, how comfortable are you with the assumptions baked into long range cash flow forecasts?
For a closer look at how those cash flows are modeled and what would need to hold for that gap to make sense, Look into how the SWS DCF model arrives at its fair value..
Next Steps
If this mix of contract momentum, balance sheet repair, and valuation signals around GEO Group feels both exciting and uneasy, that is exactly the point. Move quickly to review the hard numbers, weigh the trade offs, and decide where you land on its 3 key rewards and 3 important warning signs.
Looking For More Ideas Beyond GEO Group?
Do not stop with GEO Group when there are other opportunities that could fit your goals just as well, or even better over time.
- Spot potential value plays early by scanning a focused list of attractively priced companies through the 35 high quality undervalued stocks.
- Strengthen your downside protection by filtering for businesses with robust finances using the list of solid balance sheet and fundamentals (24 results).
- Hunt for off-the-radar opportunities with strong fundamentals by checking the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com