


EN
Is Seria (TSE:2782) Undervalued As Higher Dividend And FY2027 Guidance Lift Confidence?
Seria (TSE:2782) has put fresh numbers on the table by lifting its second quarter dividend to ¥40 per share and issuing detailed earnings guidance through March 2027, giving investors new inputs to weigh.
Seria’s higher payout and multi year guidance have landed against a backdrop where the share price has climbed 19.91% year to date. The 1 year total shareholder return of 38.89% and 3 year total shareholder return of 113.42% point to momentum that long term holders will already recognise.
Scan how Seria compares with other potential compounders by reviewing a curated list of retailers and consumer stocks with strong fundamentals in the 72 high quality undiscovered gems.
Bulls see Seria’s richer dividend and detailed profit roadmap as proof the valuation gap is closing fast. Bears argue the recent run already prices that in. Which side do the numbers lean toward next in the valuation work up?
Preferred Price-to-Earnings of 15.4x: Is it justified?
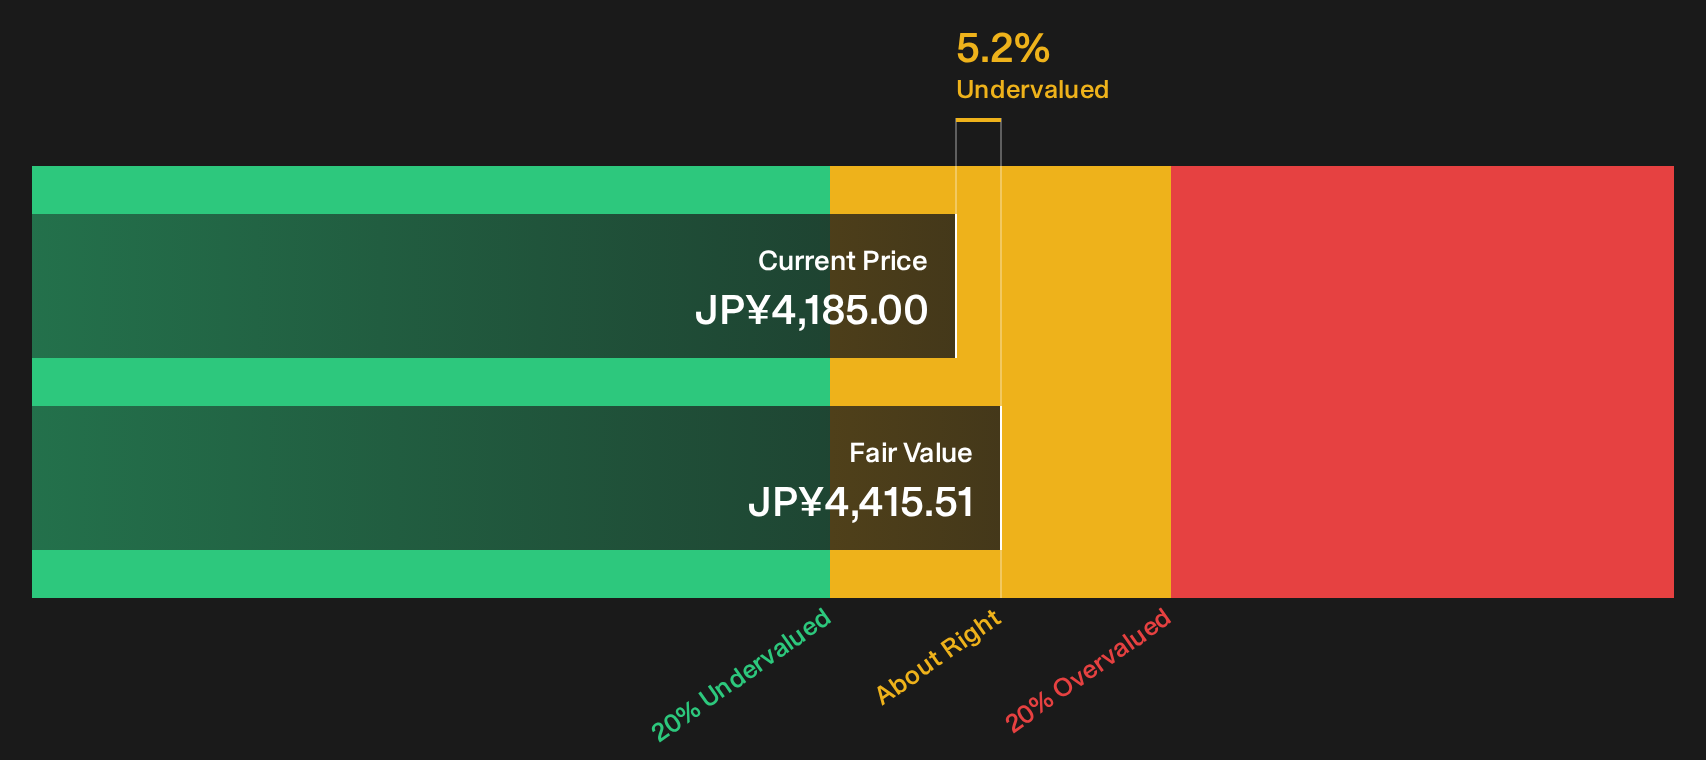
Seria closed at ¥4,185, and on the latest figures that equates to a P/E of 15.4x, which screens as mixed value. The stock trades 5.2% below an SWS DCF model estimate of future cash flow value of ¥4,415.51, yet the current earnings multiple sits above an internal fair P/E of 14.1x.
The P/E ratio compares what investors are paying today for each unit of current earnings. For a retailer like Seria, which generated revenue of ¥272,942 and net income of ¥17,063, this measure helps you assess how much the market is charging for its profit stream relative to both history and peers.
Seria’s P/E of 15.4x is described as good value compared to the JP Multiline Retail industry average of 16.3x and the peer average of 22.1x. At the same time, it is labelled expensive versus the estimated fair P/E of 14.1x, which suggests the valuation could move closer to that lower level if sentiment or expectations soften.
Explore the SWS fair ratio for Seria.
Result: Price-to-Earnings of 15.4x (ABOUT RIGHT)
Still, the Seria story could be knocked off course if consumer demand softens or if higher costs pressure that ¥17,063 net income base.
Find out about the key risks to this Seria narrative.
Another view on Seria’s value
Consider Seria through the SWS DCF model rather than an earnings multiple, and the picture tilts slightly in the other direction. At ¥4,185 the shares are about 5.2% below an estimated future cash flow value of ¥4,415.51, which frames the same price as modestly undervalued instead of slightly expensive.
This kind of gap is small in absolute terms, yet for investors it raises a simple question: does the market lean too much on near-term earnings optics and too little on the cash that Seria is projected to generate over time, or is the DCF assuming more than you are comfortable with?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Seria for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 23 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Positive signals around Seria’s value and dividend are clear, yet the decision is still yours. Move quickly to test the upside and pressure points yourself and weigh those against the 3 key rewards
Looking for more investment ideas beyond Seria?
If Seria has sharpened your focus on quality, do not stop there. Put a wider watchlist together so you are ready when the next setup appears.
- Target resilience first and scan a 19 resilient stocks with low risk scores that highlights businesses with sturdier profiles when conditions turn choppy.
- Zero in on financial strength by running through a list of solid balance sheet and fundamentals (23 results) that keeps weak capital structures off your radar.
- Hunt for income opportunities with a 29 dividend fortresses that focuses on higher yielding payers with the numbers to support ongoing distributions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com