


EN
Corning (GLW) Stock Still Looks Undervalued After a 320% Run
Corning has delivered a very large 3 year return while its share price has recently pulled back, which raises a straightforward question for investors who care about cash flow. Do the company’s current cash flows, and what it may reasonably earn from them, line up with where the stock trades today.
- Over the past 3 years the stock has gained about 320%, putting a lot of long term value creation assumptions into the cash flow story that underpins the current valuation.
- Recent reports on cell harvesting and 3D cell culture highlight Corning’s role in automation and advanced lab tools, which can influence how quickly and reliably those activities turn into cash that supports the share price.
- If you'd rather focus on earnings, this one's for you. See why Corning's 44.9x P/E tells a different valuation story.
The issue now is whether Corning’s present share price is appropriately supported by the cash flows that a Discounted Cash Flow (DCF) approach attributes to the business.
If you want a broader watchlist while you assess whether Corning’s recent run and pullback line up with its cash flows, a focused screen of solid balance sheet and fundamentals stocks screener (24 results) may be useful.
Is Corning a Bargain on Cash Flow?
The Discounted Cash Flow (DCF) approach here projects the cash that Corning could return to shareholders over time and then discounts it back into today’s dollars. Corning generated about $2.7b of free cash flow over the last twelve months, and the 2 Stage Free Cash Flow to Equity model assumes that this figure continues to grow from that base rather than shrink.
Analyst inputs and model extensions both point to expanding free cash flows over the coming decade. This is what drives the DCF outcome to sit substantially above the current share price of $112.13. The role Corning plays in automation for cell harvesting and 3D cell culture helps explain why the market is willing to price in stronger long term cash generation, even if the DCF still suggests more value than the quote reflects. Find out what Corning could be worth using our Discounted Cash Flow (DCF) estimate.
The Corning Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Corning pick up where this valuation puzzle leaves off and set out the specific growth, margin and earnings paths that would need to hold for the stock to end up worth materially more or less than today's share price, using frameworks that live on the Community page. Each narrative treats Corning's implied fair value as a thesis about the business that can be revisited over time, rather than a static snapshot that never gets checked against what actually happens.
One of the top narratives on Corning: 39% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"The main thing that has to go right is that Corning converts its large optical and solar order book, customer prepayments and long duration supply agreements into the Springboard 20 30 40 plan outcomes…"
Discover why this Narrative puts Corning at 39% undervalued.
One more piece of the Corning story to check
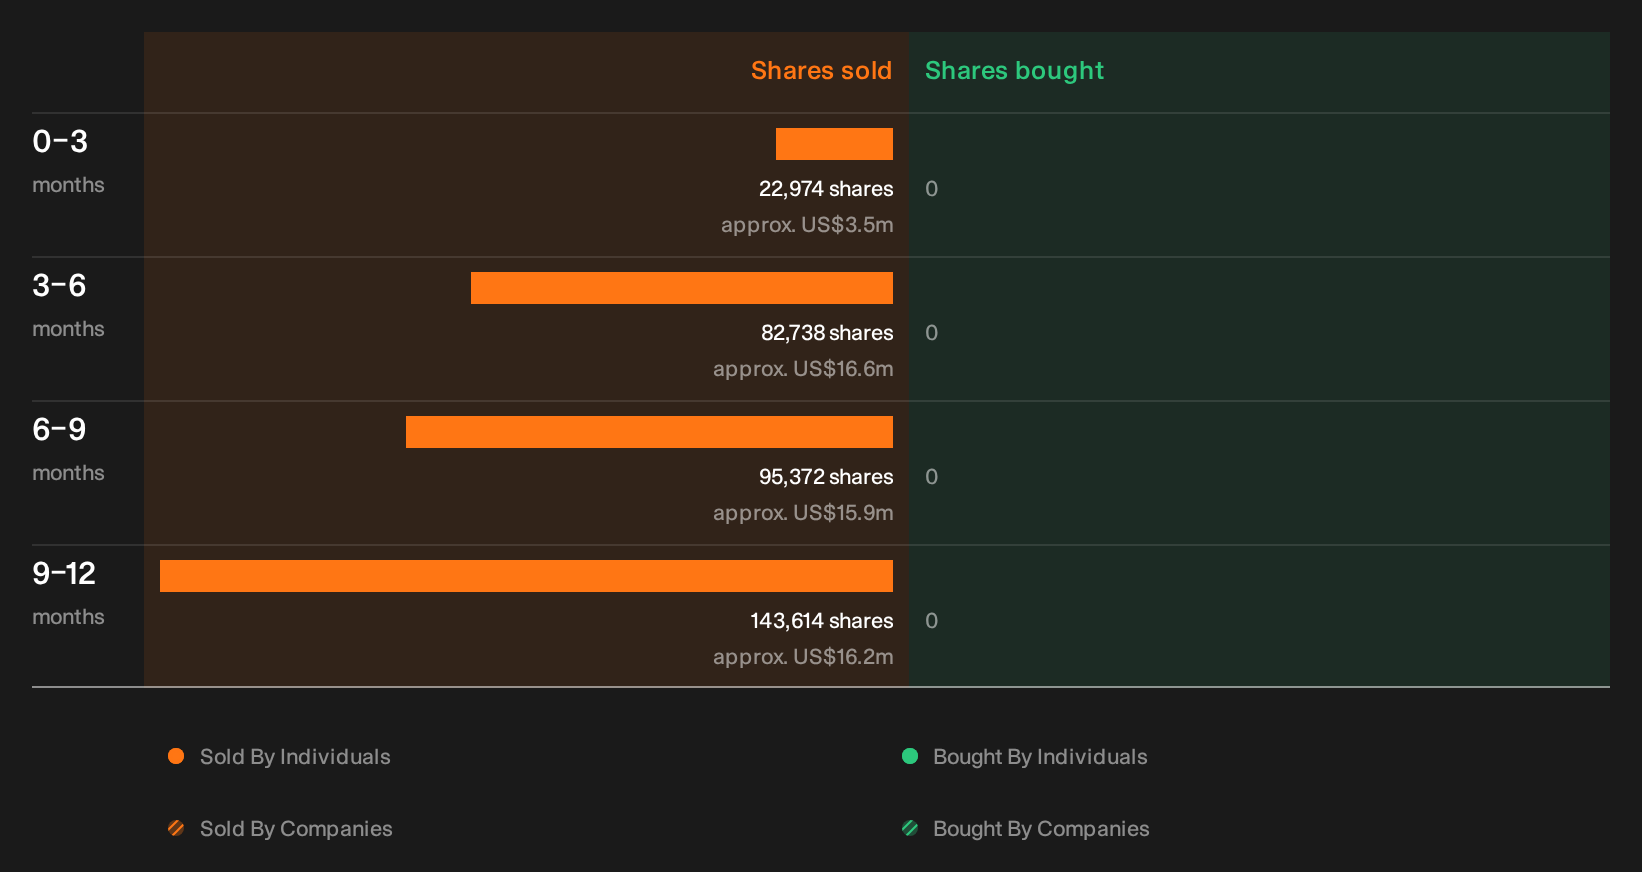
There is one thread that has not been explored yet, because recent disclosures point to insider share sales where the individuals, size and possible interpretation are still for you to examine. See the recent insider selling flagged for Corning.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com