


EN
Electronic components & manufacturing stocks Q3 recap: benchmarking TTM Technologies (NASDAQ:TTMI)
Looking back on electronic components & manufacturing stocks’ Q3 earnings, we examine this quarter’s best and worst performers, including TTM Technologies (NASDAQ:TTMI) and its peers.
The sector could see higher demand as the prevalence of advanced electronics increases in industries such as automotive, healthcare, aerospace, and computing. The high-performance components and contract manufacturing expertise required for autonomous vehicles and cloud computing datacenters, for instance, will benefit companies in the space. However, headwinds include geopolitical risks, particularly U.S.-China trade tensions that could disrupt component sourcing and production as the Trump administration takes an increasingly antagonizing stance on foreign relations. Additionally, stringent environmental regulations on e-waste and emissions could force the industry to pivot in potentially costly ways.
The 10 electronic components & manufacturing stocks we track reported a very strong Q3. As a group, revenues beat analysts’ consensus estimates by 4.9% while next quarter’s revenue guidance was 4.1% above.
Amidst this news, share prices of the companies have had a rough stretch. On average, they are down 6.1% since the latest earnings results.
Weakest Q3: TTM Technologies (NASDAQ:TTMI)
As one of the world's largest printed circuit board manufacturers with facilities spanning North America and Asia, TTM Technologies (NASDAQ:TTMI) manufactures printed circuit boards (PCBs) and radio frequency (RF) components for aerospace, defense, automotive, and telecommunications industries.
TTM Technologies reported revenues of $1.20 billion, up 59.9% year on year. This print exceeded analysts’ expectations by 7.3%. Overall, it was a favorable quarter for the company with a beat of analysts’ EPS estimates and revenue guidance for next quarter meeting analysts’ expectations.
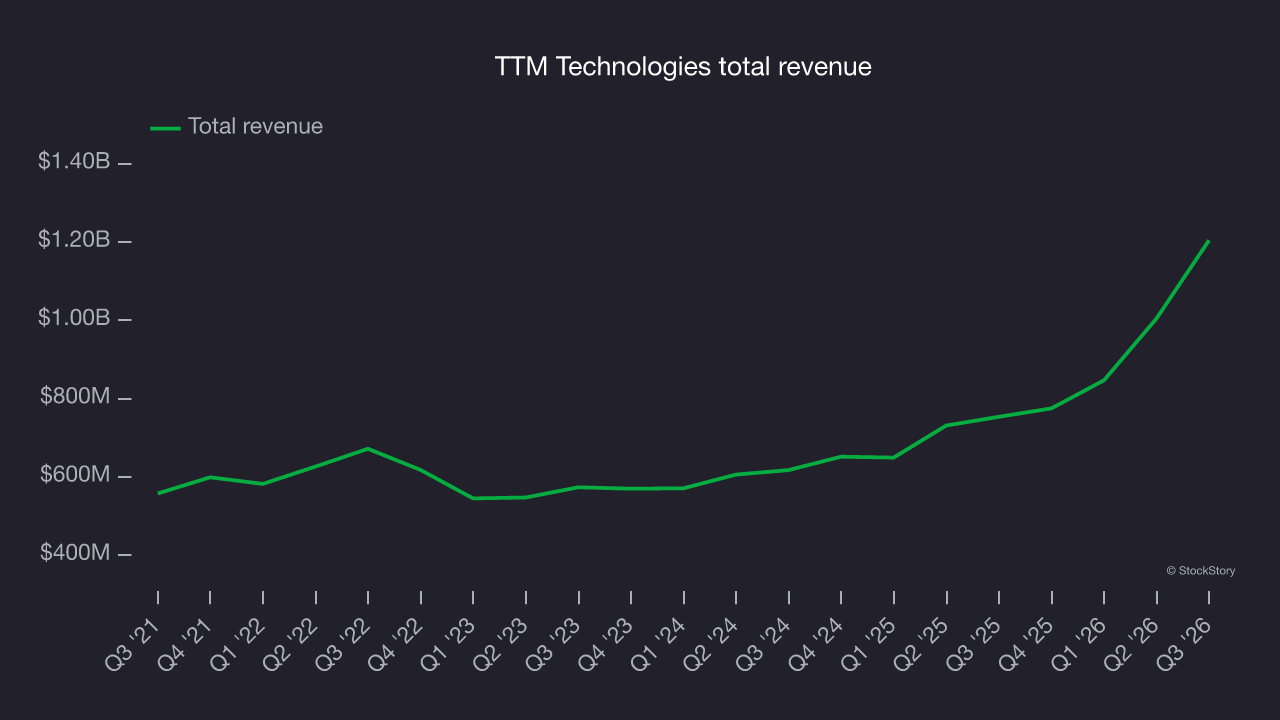
TTM Technologies delivered the weakest guidance update of the whole group. Investor expectations, however, were likely higher than Wall Street’s published projections, leaving some wishing for even better results (analysts’ consensus estimates are those published by big banks and advisory firms, not the investors who make buy and sell decisions). The stock is down 28.4% since reporting and currently trades at $73.12.
Is now the time to buy TTM Technologies? Access our full analysis of the earnings results here, it’s free.
Best Q3: Plexus (NASDAQ:PLXS)
With over 20,000 team members across 26 global facilities, Plexus (NASDAQ:PLXS) designs, manufactures, and services complex electronic products for companies in aerospace/defense, healthcare, and industrial sectors.
Plexus reported revenues of $1.43 billion, up 34.8% year on year, outperforming analysts’ expectations by 4.9%. The business had an impressive quarter with a solid beat of analysts’ EPS guidance for next quarter estimates and revenue guidance for next quarter exceeding analysts’ expectations.
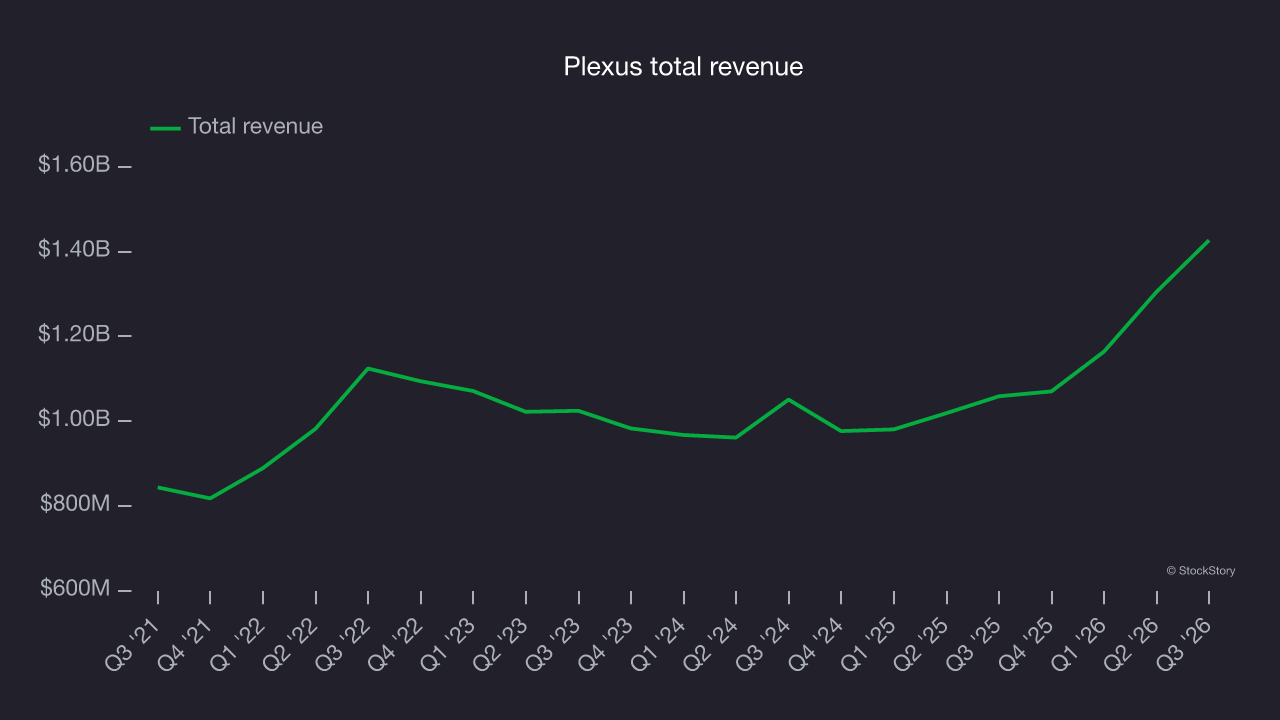
Although it had a fine quarter compared to its peers, the market seems unhappy with the results as the stock is down 14.3% since reporting. It currently trades at $205.11.
Is now the time to buy Plexus? Access our full analysis of the earnings results here, it’s free.
Rogers (NYSE:ROG)
With roots dating back to 1832, making it one of America's oldest continuously operating companies, Rogers (NYSE:ROG) designs and manufactures specialized engineered materials and components used in electric vehicles, telecommunications, renewable energy, and other high-performance applications.
Rogers reported revenues of $236.1 million, up 9.3% year on year, falling short of analysts’ expectations by 0.8%. Still, its results were good as it locked in a beat of analysts’ EPS estimates and a solid beat of analysts’ EPS guidance for next quarter estimates.
Rogers delivered the weakest performance against analyst estimates among its peers. As expected, the stock is down 4.3% since the results and currently trades at $128.29.
Read our full analysis of Rogers’s results here.
Flex (NASDAQ:FLEX)
Originally known as Flextronics until its 2016 rebranding, Flex (NASDAQ:FLEX) is a global manufacturing partner that designs, engineers, and builds products for companies across industries from medical devices to solar trackers.
Flex reported revenues of $8.49 billion, up 24.8% year on year. This number beat analysts’ expectations by 4.2%. Overall, it was a favorable quarter as it also produced a solid beat of analysts’ full-year EPS guidance estimates and a beat of analysts’ EPS estimates.
Flex had the weakest full-year guidance update in the group. The stock is down 7.3% since reporting and currently trades at $77.27.
Read our full, actionable report on Flex here, it’s free.
Coherent (NYSE:COHR)
Created through the 2022 rebranding of II-VI Incorporated, a company with roots dating back to 1971, Coherent (NYSE:COHR) develops and manufactures advanced materials, lasers, and optical components for applications ranging from telecommunications to industrial manufacturing.
Coherent reported revenues of $2.37 billion, up 49.9% year on year. This result surpassed analysts’ expectations by 2.5%. It was a very strong quarter as it also logged a solid beat of analysts’ EPS guidance for next quarter estimates and revenue guidance for next quarter exceeding analysts’ expectations.
The stock is up 13.1% since reporting and currently trades at $220.63.
Read our full, actionable report on Coherent here, it’s free.
Market update
Over the past year, investors have been forced to repeatedly answer the same question: what is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our Top 5 Quality Compounder Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.