


EN
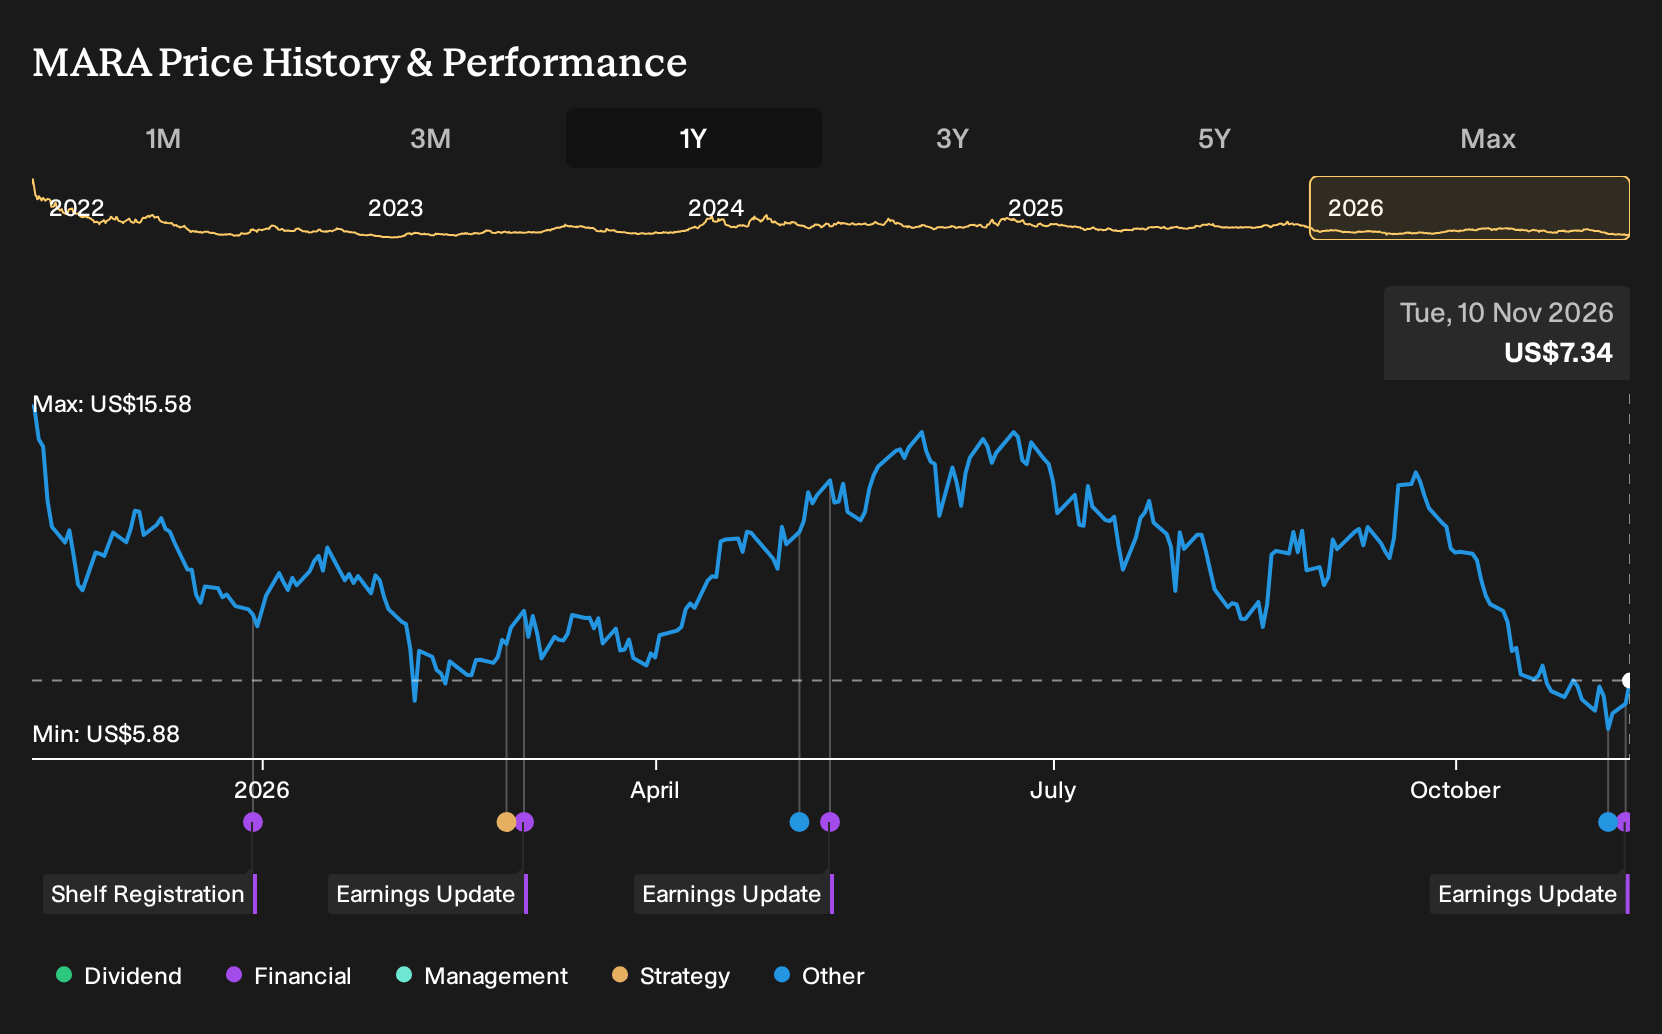
MARA Holdings Stock Gains On Bitcoin Driven Profit and AI Expansion
- MARA Holdings reported Q3 2026 sales of US$164.23 million, a net income of US$634.36 million, and basic EPS from continuing operations of US$1.64. Results were driven largely by gains on Bitcoin holdings despite softer top line performance.
- The group used extensive Bitcoin sales and US$1.1 billion of proceeds to repay Bitcoin-backed debt, authorize up to US$500 million in share repurchases, and invest further in AI and high performance computing infrastructure. This signals a pivot in how it monetizes its 4.8 GW power portfolio.
- The focus now shifts to how MARA Holdings' Bitcoin-driven profit spike and AI pivot reshape its investment narrative around power-backed assets.
Scan how MARA Holdings' AI and power ambitions compare by reviewing handpicked 53 AI infrastructure stocks that are riding similar demand for compute and grid access.
MARA Holdings Investment Narrative Recap
To own MARA Holdings, you need to believe the business can turn its large power footprint and digital platforms into recurring AI and high performance computing cash flows while managing the swing factor of Bitcoin. The Q3 print underlines that tension. Sales fell year on year, yet net income for the quarter was heavily tied to Bitcoin linked gains.
The near term catalyst is still whether MARA can sign and ramp credible AI or compute leases against that roughly 4.8 GW portfolio highlighted in the analyst consensus Narrative on Simply Wall St. The biggest immediate risk is that mining pressure, revenue volatility, and less than one year of cash runway collide with slow progress on contracting those AI sites.
The FERC approval for the Long Ridge Energy & Power acquisition feels central to this Q3 story. Management is not just buying a 505 MW gas plant. It is adding land, grid access, and infrastructure that can underpin the first 200 MW AI and high performance computing build that analysts have flagged as a key project in that Narrative.
For shareholders, Long Ridge matters because it provides contracted power generation cash flows that sit alongside more volatile Bitcoin linked results. Execution risk now shifts to actually building out and leasing that campus. Any delay or weaker than expected tenant demand would make the AI pivot slower to show up in reported revenue and earnings.
MARA Holdings' narrative projects US$858.9 million in revenue and US$106.1 million in earnings by 2029. This projection is based on 2.2% yearly revenue growth and an earnings increase of about US$3.6b from a current earnings loss of US$3.5b.
Uncover why MARA Holdings' fair value indicates a 141% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One bearish twist in the alternate MARA Holdings story is construction risk at Long Ridge. You can see how sharp that contrast is. The most cautious analysts were pencilling in revenue of about US$374.0 million and earnings of roughly US$45.0 million by 2029, which is far lower than consensus. Those forecasts came before this Q3 report and FERC approval, so opinions may shift as fresh data lands. It is worth exploring both narratives before deciding what feels realistic to you.
Explore 6 other MARA Holdings fair value estimates, including one that suggests it could be worth just $10.00!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your MARA Holdings research is our analysis highlighting 3 important warning signs that could impact your investment decision.
- See our latest analysis for MARA Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate MARA Holdings' overall financial health at a glance.
Looking For More Ideas Beyond MARA Holdings?
If MARA Holdings' mix of Bitcoin exposure, AI build out, and power assets has you rethinking where you want risk in your portfolio, it can help to line it up against other listed businesses with very different drivers.
The Simply Wall St screener lets you filter for the kind of balance sheet strength, income profile, or upside potential that matches your own playbook rather than someone else's.
- If capital preservation comes first for you, start with companies that screen well on resilience and financial risk through the 30 resilient stocks with low risk scores.
- If predictable income matters more than headline growth, check out potential cash generators with the 5 dividend fortresses.
- If you want to hunt for less crowded opportunities, broaden your watchlist with the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com