


EN
Does Riot Platforms (RIOT) Trade At A Premium After AI Leases?
Riot Platforms has swung sharply in recent years, helped by headline AI data center deals and a volatile crypto backdrop, which puts a spotlight on a basic question for investors who care about numbers. At a US$18.08 closing price, the issue is whether the current value of the stock lines up with what its sales can reasonably support.
- Riot Platforms has delivered an 85.8% share price gain over the past 3 years, which raises the question of how much of that move is backed by its revenue base rather than shifting sentiment around crypto and AI.
- The long term powered land leases tied to Anthropic, including the US$28b Corsicana agreement and the US$9.1b Rockdale contract, may support a different mix of sales and cash flow timing compared with Riot's earlier focus on Bitcoin mining alone.
- Your read on Riot Platforms is one view; the desks covering it have another. See what analysts think Riot Platforms's shares could be worth.
The stock's next move may depend on whether Riot Platforms' current market price looks well aligned with the sales it is generating and aiming for through these AI data center commitments.
If you want a broader starting point before forming a view on Riot Platforms, a focused stock screen built around 53 AI infrastructure stocks may be useful.
Does Riot Platforms Look Pricey on Sales?
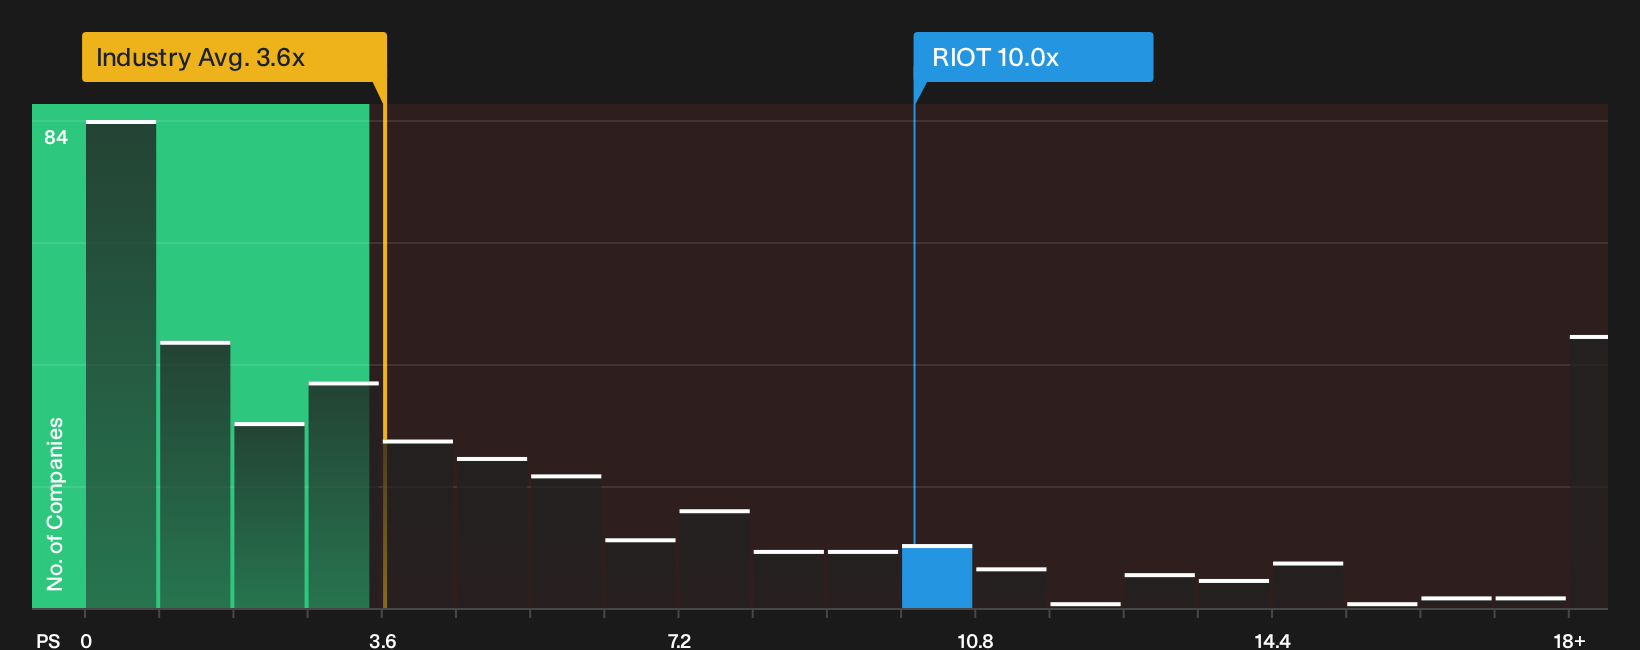
P/S makes sense for Riot Platforms because the business is still loss making on free cash flow and shifting its model toward long term AI infrastructure leases. At a P/S ratio of 10.0x, the stock trades well above the broader software industry average of 3.6x and below the 16.4x peer group average supplied for this framework.
The tailored fair multiple used here, which blends factors like Riot Platforms' margins, risk profile and scale, points to a lower P/S level than where the shares trade today. As a result, the model reads the current valuation as overvalued on sales. Despite the huge Anthropic lease headlines and the excitement around AI data center capacity, the current P/S still embeds a rich price tag relative to what this framework suggests is supported by the revenue base. Explore the numbers behind Riot Platforms's P/S valuation.
The Riot Platforms Narrative: What Would Justify Today's Price?
Riot Platforms' valuation puzzle sets up the role of Simply Wall St Narratives, which explain what kind of future path for growth, margins and earnings would need to occur for the stock to be worth meaningfully more or less than today's price on the Community page.
Each Narrative links its number to a specific view on how Riot Platforms' revenue mix, profitability and risk profile could evolve, allowing you to revisit those assumptions as fresh information emerges.
Bulls and bears on Riot Platforms are looking at the same AI data center pivot and drawing very different conclusions about how much risk the price reflects.
Bull case: 36% undervalued
The analyst consensus Narrative on Simply Wall St focuses on the contracted AI leases as the key upside swing factor.
"Riot’s capital recycling model, which uses Bitcoin sales and cash for initial builds then adds non recourse project debt at around 80% to 90% loan to cost…"
Discover why this Narrative puts Riot Platforms at 36% undervalued.
Bear case: 20% overvalued
The bearish analyst Narrative on Simply Wall St leans on funding strain and earnings quality as the main constraints.
"Despite plans to finance up to 80 to 90% of the 191 MW Rockdale build cost with project debt, reliance on high loan to cost structures introduces interest and refinancing exposure…"
Explore why this Narrative puts Riot Platforms at 20% overvalued.
Riot Platforms has one more piece of the puzzle investors should check
Before you lean too hard on any valuation framework for Riot Platforms, it is worth knowing that Simply Wall St's broader checks have flagged specific concerns that could change how you view the whole picture. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com