


EN
Should Strong Earnings Results Require Action From Tutor Perini (TPC) Investors?
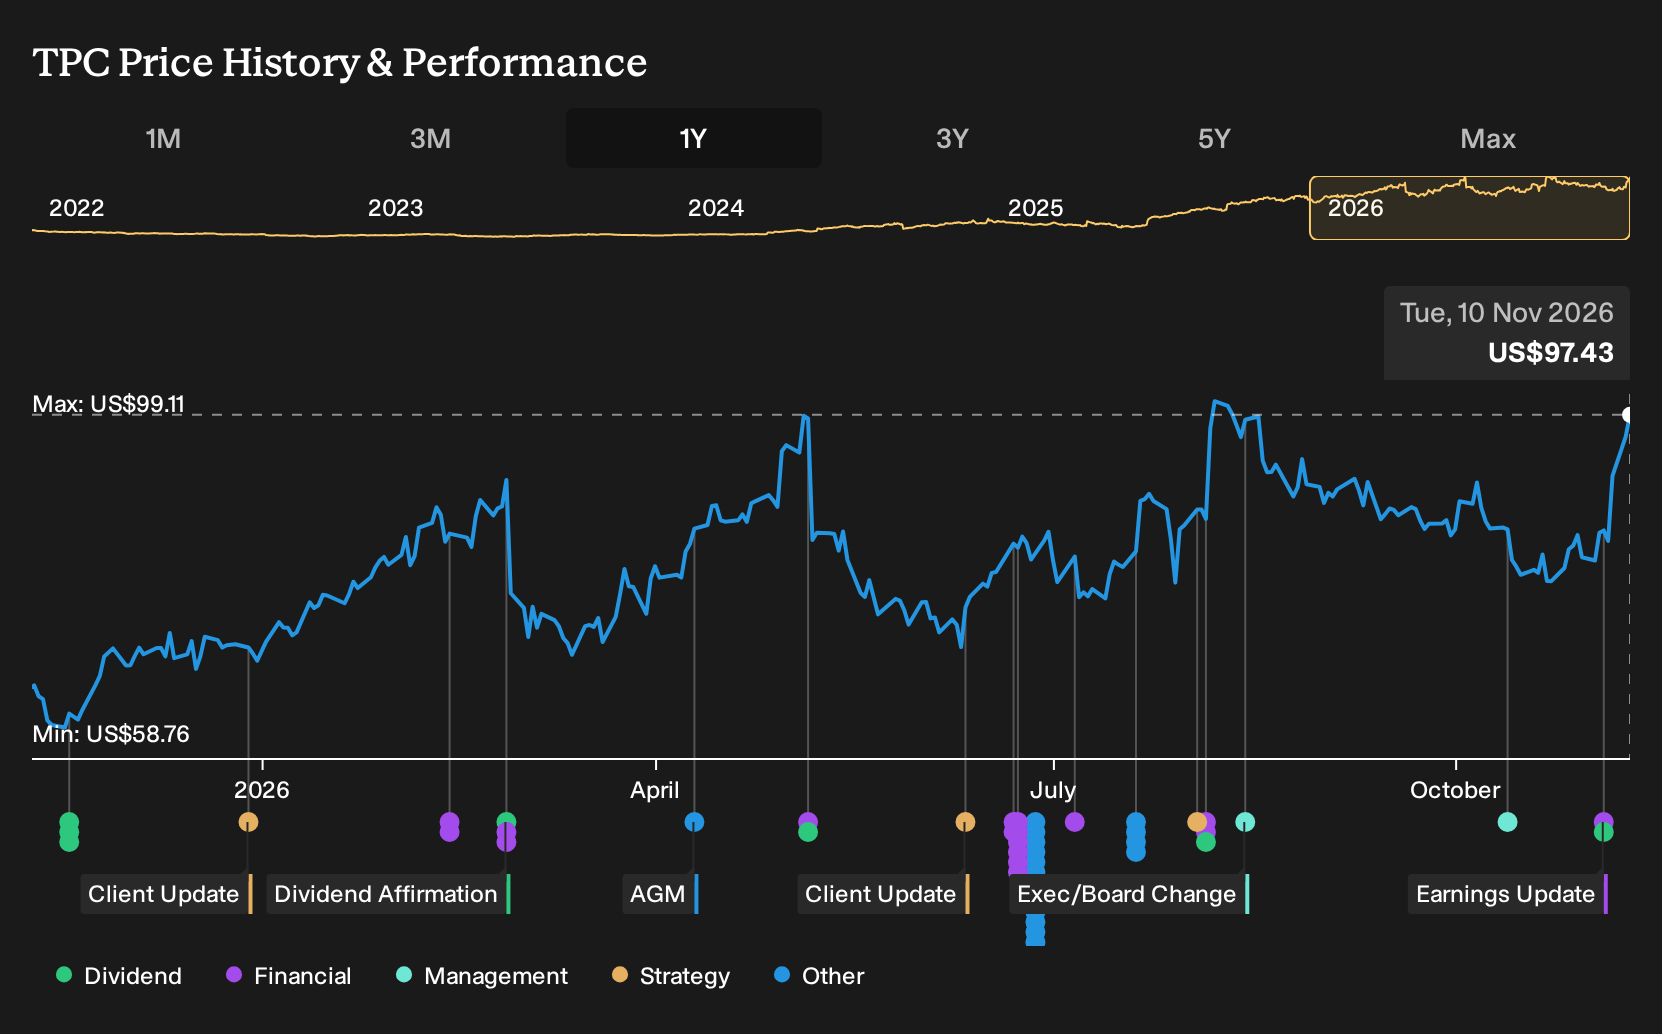
- Tutor Perini reported third quarter 2026 sales of US$1,720.26m and net income of US$20.7m, with nine month sales of US$4,746.76m and profit of US$112.14m from continuing operations.
- Alongside these results, the Board affirmed a quarterly US$0.09 dividend. Analysts highlighted Tutor Perini’s value ratios and improving earnings expectations as supporting the construction contractor’s current positioning.
- We will now look at how Tutor Perini's stronger year to date earnings performance may influence the broader investment narrative.
Tutor Perini Investment Narrative Recap
To own Tutor Perini, you need to believe the construction group can keep turning its near record US$20.4b backlog and large project pipeline into disciplined, higher margin work. The latest quarter shows that, for now, execution is lining up with that thesis, with higher sales and net income and stronger year to date earnings from continuing operations.
The key short term swing factor remains how cleanly that backlog converts into cash and profit, given legacy legal exposures and past one off items in results. The recent earnings beat helps sentiment but does not materially change those underlying risks, so contract mix, dispute outcomes and cash generation still matter most.
The most tangible new data point is the third quarter 2026 result itself. Tutor Perini reported US$1,720.26m of sales and US$20.7m of net income for the period, with nine month revenue of US$4,746.76m and profit of US$112.14m from continuing operations. That operational print sits alongside record operating cash flow and a net cash position already highlighted in the analyst consensus Narrative on Simply Wall St.
That combination of reported earnings, prior refinancing of high coupon notes and a thicker backlog gives management more room to focus on execution of mega projects and on resolving disputes that could otherwise absorb cash. The reaffirmed US$0.09 quarterly dividend signals a steady capital return stream, although the headline payout does not change the core catalysts around margin quality, working capital release and legal outcomes.
Tutor Perini's current narrative is built on analysts expecting revenue to grow by 10.1% per year, with earnings rising from US$141.0m today to US$615.0m by 2029. On those assumptions, the forecasts imply about a 4.4x increase in profit and require revenues to reach US$8.4b in the same year.
Uncover why Tutor Perini's fair value indicates a 19% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts frame Tutor Perini’s Indo Pacific and data center work as the real swing factor. Before this earnings release, the bullish camp was pencilling in about 12.0% annual revenue growth and earnings of roughly US$612.3m by 2029. You can compare that view with other forecasts and decide which assumptions feel more realistic after these results.
Explore 3 other Tutor Perini fair value estimates, including one that suggests as much as 21% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Tutor Perini research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Tutor Perini. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Tutor Perini's overall financial health at a glance.
Looking for more investment ideas beyond Tutor Perini?
If Tutor Perini has sharpened your thinking about risk, cash flow and project quality, it can be useful to line those ideas up against a wider watchlist. The Simply Wall St Screener lets you scan for other businesses that match the kind of financial profile you want to focus on next.
- For investors who care most about balance sheet strength and resilient fundamentals, filter the market with a list of solid balance sheet and fundamentals (24 results) and see which companies meet your quality bar.
- If you prefer opportunities where the risk profile looks more measured, use the screener to surface 30 resilient stocks with low risk scores that may better match a steadier approach.
- When you want to broaden your horizons and spot less crowded ideas, run a search for 20 high quality undiscovered gems and build a watchlist of potential next candidates.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com