


EN
What Terex Doubters Overlooked
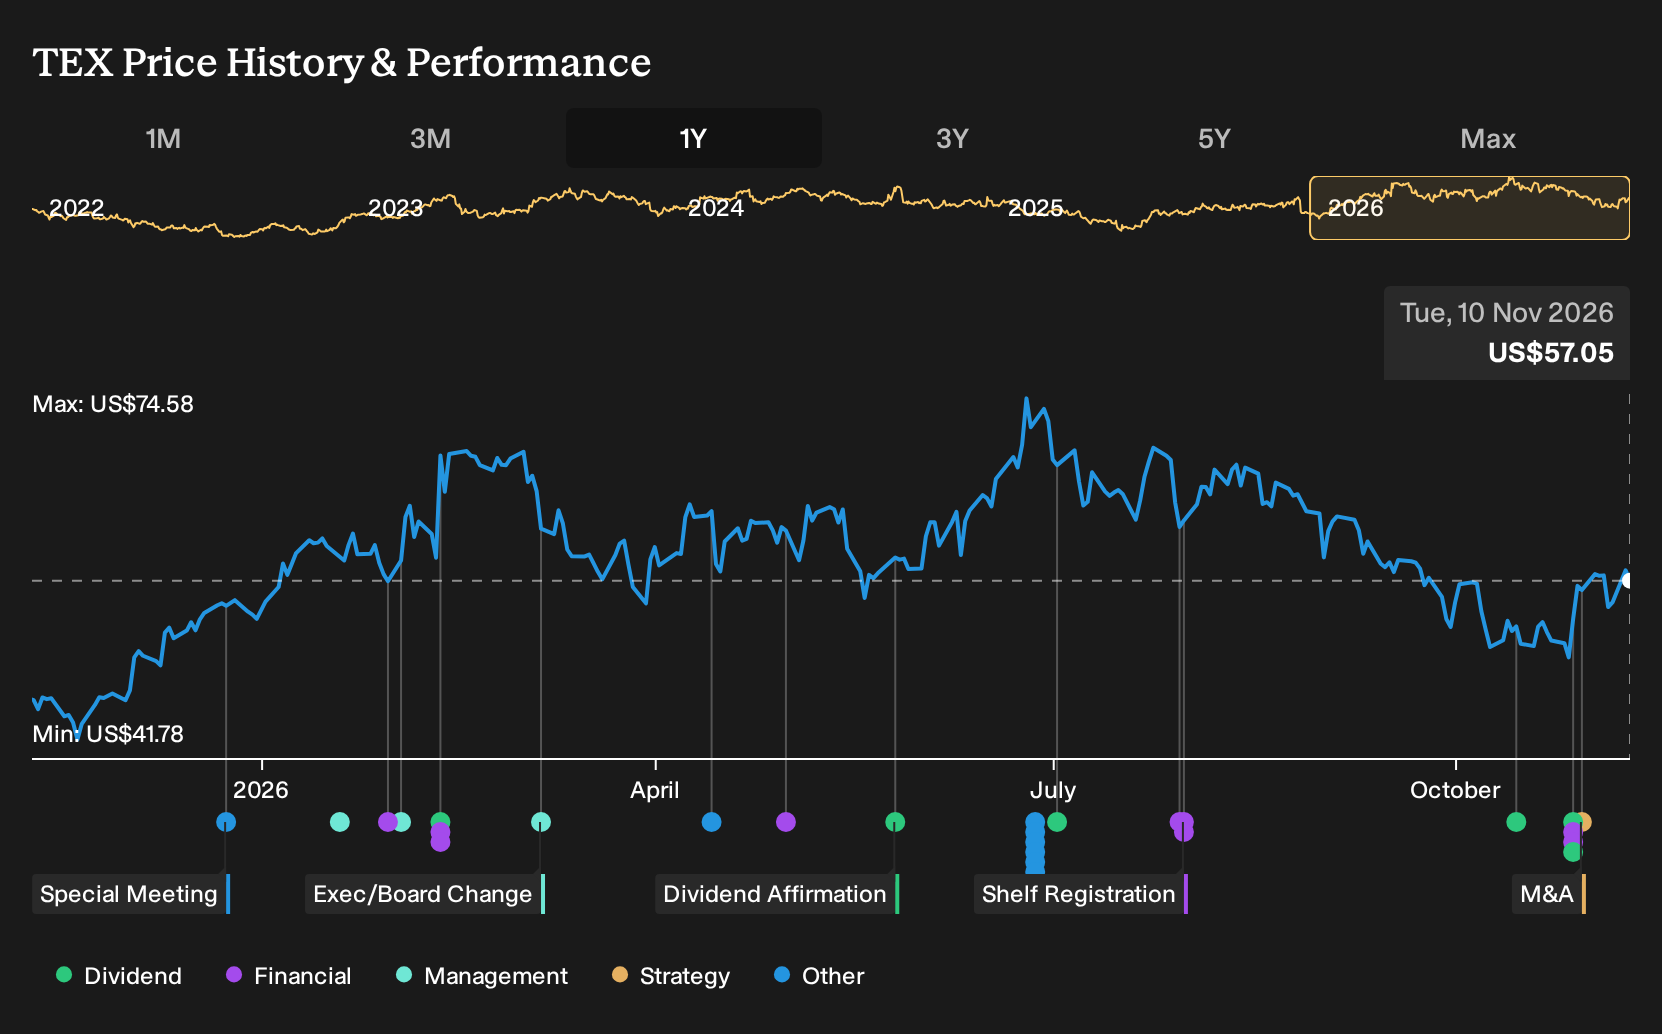
If you had put money into Terex on 10 November 2025 and simply sat tight, you might be looking at the result very differently today. Holding Terex over the past year would have returned 29.0%, including dividends. That outcome sits against a backdrop of analysts split between a higher fair value and a much lower bearish target. If you were deciding back then, how would you have weighed strong infrastructure demand against warnings about automation, tariffs, and margin pressure?
This theme extends beyond Terex. See which of 91 robotics and automation stocks may still merit a closer look.
The Two Terex Stories Investors Had To Weigh
The shares cost US$45.56 at the start of the period, so anyone looking at Terex then was really choosing between two very different stories.
The optimistic view pointed to a Fair Value of US$55.2, a rough guide to what the bull camp thought the stock could be worth if Terex achieved 6.0% annual revenue growth and an 8.5% profit margin over three years.
The cautious narrative worked off a Fair Value of US$35.5 and focused on the risk that tighter environmental rules and rising automation would make Terex's diesel heavy portfolio more costly to update and less competitive.
What The Results Changed For The Terex Debate
The clearest development for Terex was the Q3 2026 report, where revenue reached US$2.2b and net income was US$114m, with net margin at 5.2% versus 4.7% a year earlier. That margin outcome pointed toward the optimistic case that assumed improving profitability, while tariff driven compression flagged in news reports kept the cautious story alive. Overall, the evidence cut both ways.
The key lesson is simple. When a thesis leans on margin improvement, track the reported net margin quarter by quarter and compare it with the original assumption, rather than focusing only on the revenue line or share price.
What Terex's Recent Run Already Prices In
Terex now trades at US$57.05, with the analyst consensus Narrative on Simply Wall St suggesting its Fair Value sits above that level based on current assumptions. The argument leans heavily on backlog, raised guidance and the Terex mix toward North America focused specialty equipment.
For that higher Fair Value to be reached, a buyer today would need to believe Terex can keep strengthening margins while integrating Environmental Solutions and Specialty Vehicles under ongoing tariff and mix pressure.
"The main thing that has to go right is that Terex continues to improve and hold margins through tariff headwinds, mix shifts, and integration of Environmental Solutions and Specialty Vehicles while capturing the remaining synergies now built into guidance."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Looking One Step Beyond Terex
Terex keeps you focused on concrete, steel, and job sites. One step away, another kind of infrastructure quietly determines whether AI can keep running.
Those racks of processors do not just need power. They must stay within tight temperature limits or the computing work stalls.
Specialist engineers now design liquid cooling systems that move heat more efficiently than air. Their hardware and software help data centres keep dense equipment operating safely.
As AI projects spread and workloads increase, that thermal bottleneck only gets tougher. The company solving it could shift from background supplier to essential infrastructure provider.
That argument has a Narrative and a number behind it. → See the company one Narrative values 110% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com