


EN
PDD Holdings (PDD) Stock Still Looks Cheap Following A 42% Slide
PDD Holdings has seen its share price fall sharply over the past year, and that kind of drawdown naturally raises a simple question for investors who care about numbers. Is the current valuation still in step with what the company is earning, or has the stock price moved out of line with its underlying profitability?
- PDD Holdings has declined 42.1% over the past year, which puts the focus squarely on whether that price reset has brought the earnings based valuation case into a different place than before.
- Morgan Stanley’s cut to its rating and US$90 price target highlights concerns about the Chinese e commerce sector and PDD Holdings’ use of its cash pile, which can shape how investors think about the durability and timing of future profit streams.
- There is a second opinion on PDD Holdings worth weighing. See what analysts think PDD Holdings's shares could be worth.
The issue now is whether today’s share price for PDD Holdings is adequately supported by its earnings when set against the Fair Ratio benchmark.
If you want to test the same earnings based question across a wider field, compare PDD Holdings with 35 high quality undervalued stocks.
Does PDD Holdings Look Undervalued on Earnings?
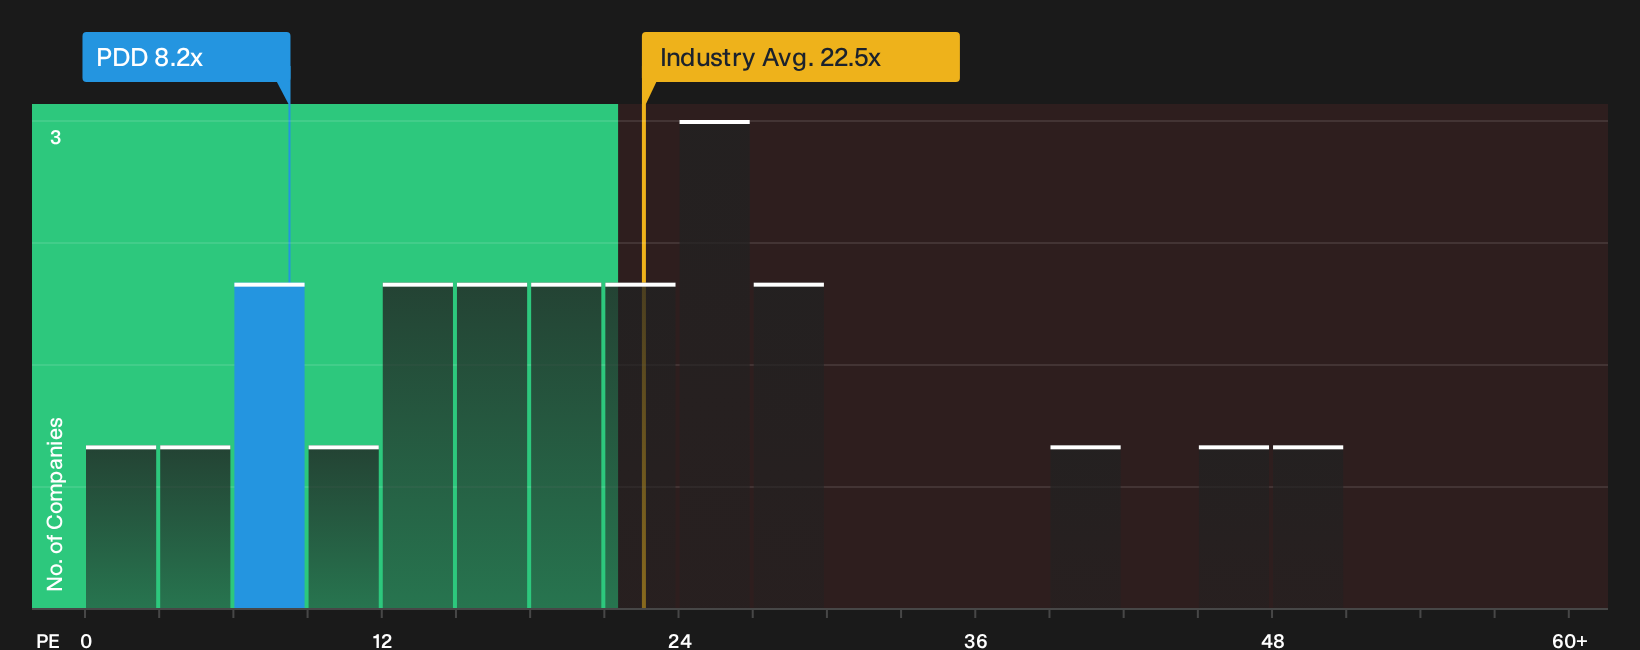
The P/E ratio is a useful lens for PDD Holdings because earnings are a central focus for investors trying to anchor the recent share price slide to fundamentals. On this measure, the stock trades on roughly 8.2x earnings, which is well below the Multiline Retail industry average of about 20.0x and also below the peer group on roughly 28.9x.
The Fair Ratio model, which adjusts for factors like margins, scale and risk, points to a higher earnings multiple than where PDD Holdings trades today, so the shares screen undervalued on this framework. Despite Morgan Stanley’s downgrade and concern about how effectively the business deploys its cash, the current P/E still prices PDD Holdings at a discount to both sector norms and similar companies. Explore the numbers behind PDD Holdings's P/E valuation.
The PDD Holdings Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St’s Community page pick up where the PDD Holdings valuation puzzle leaves off by spelling out which combinations of future growth, profitability and earnings would need to play out for the stock to be worth materially more or materially less than today’s price. Each scenario ties its number to a concrete view of how PDD Holdings' revenue trajectory, margin profile and risk picture might change, giving you a set of assumptions you can come back to as fresh information lands.
One of the top community narratives on PDD Holdings: 52% undervalued
According to LemonHunter, an investor in the Simply Wall St Community, PDD Holdings hinges on how its cash balance and international ambitions interact.
"The investment case therefore depends on three conditions, PDD’s large cash balance remains available to shareholders or supports productive investment…"
Discover why this Narrative puts PDD Holdings at 52% undervalued.
One more PDD Holdings signal investors often check before making a move
Valuation tells you what the market is paying today, while professional earnings projections show how some analysts currently frame the next few years for PDD Holdings. Explore where analysts expect PDD Holdings to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com