


EN
Sanmina (SANM) Stock May Still Look Like A Bargain After AI Guidance
Sanmina has treated long term holders to a powerful run over the past few years, which now meets a much rougher patch on the chart. The key issue is whether the current share price still lines up with what its earnings can reasonably support.
- Over the past 5 years the stock has returned about 292.5%. This puts a lot of past optimism and current expectations on trial against the company’s earnings power today.
- Recent news highlights rapid revenue and earnings per share growth linked to cloud and AI infrastructure work. This can feed directly into how durable investors think Sanmina’s profit stream may be.
- Your read on Sanmina is one view; the desks covering it have another. See what analysts think Sanmina's shares could be worth.
The stock's next move may depend on whether that recent price, after such a strong multi year run and a sharp pullback, is fully supported by Sanmina's earnings profile.
If you are weighing Sanmina against other AI infrastructure opportunities, a focused stock screen can be a useful second lens. You can start with 53 AI infrastructure stocks.
Is Sanmina a Bargain on Earnings?
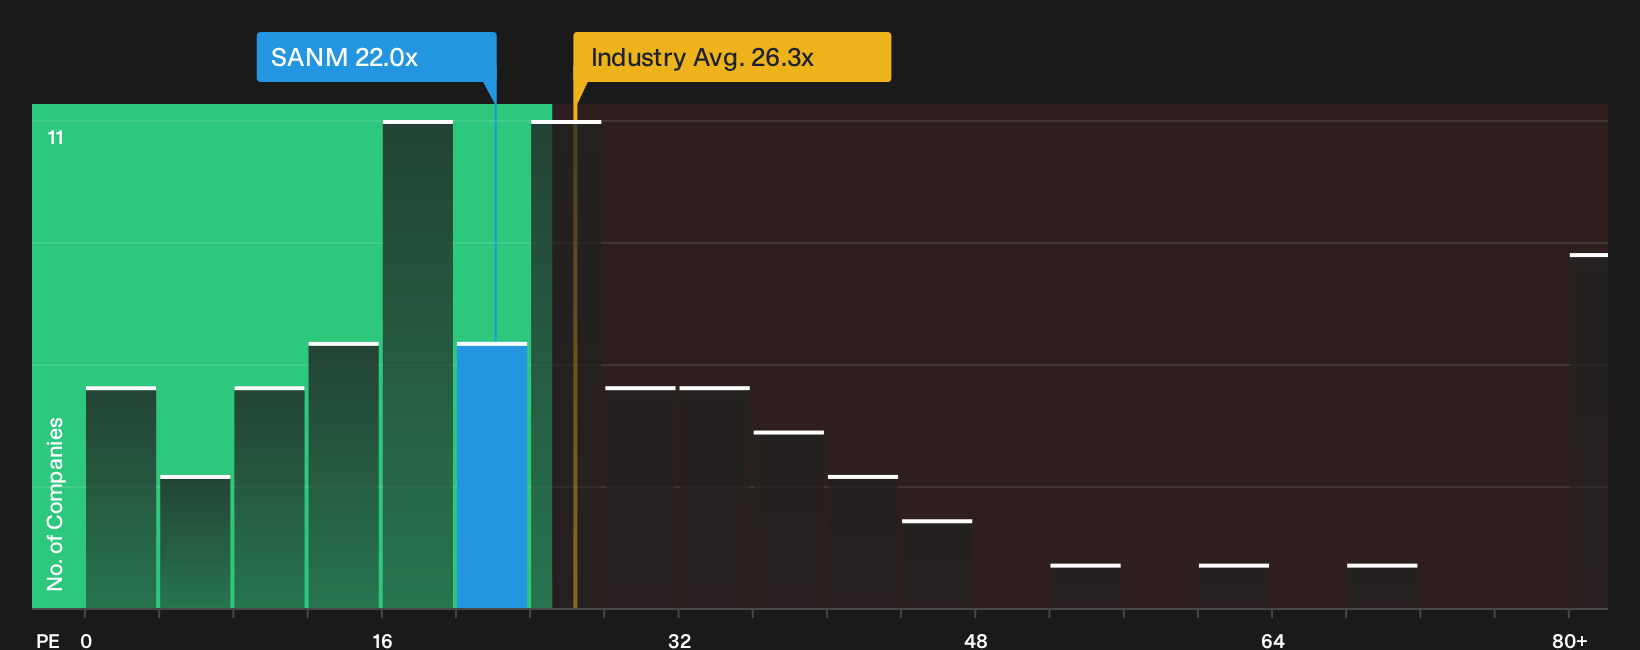
The P/E ratio fits Sanmina because earnings are the key lens investors use for a mature manufacturing specialist tied to AI and cloud demand. Right now the stock trades on about 22.0x earnings, compared with roughly 26.3x for the wider electronic industry and about 38.6x for its direct peers. That places Sanmina at a clear discount to both groups.
The fair multiple implied by its profile, which blends factors such as growth, margins, scale and risk, sits above the current P/E. As a result, the shares screen as undervalued on this yardstick. Because the latest results showed strong Q4 and fiscal 2026 earnings tied to cloud and AI work, that gap suggests the recent pullback has not fully closed the valuation discount relative to what the model infers from those fundamentals. Explore the numbers behind Sanmina's P/E valuation.
The Sanmina Narrative: What Would Justify Today's Price?
Sanmina's valuation story only really makes sense once you explain which future paths justify today's earnings multiple and which do not. Simply Wall St Narratives sets out those paths in plain language, linking each implied number to a clear view on how Sanmina's growth, profitability and risk profile could evolve. This helps you revisit the reasoning when fresh results or new contract data come through.
One of the top narratives on Sanmina: 38% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"Sanmina is expanding vertical integration in areas such as metal fabrication for AI racks, high technology PCBs, transformers and liquid cooling and test capabilities…"
Discover why this Narrative puts Sanmina at 38% undervalued.
One more Sanmina check that sits beside the share price
Before you stop at Sanmina's valuation and growth story, it is worth asking who is steering the ship, how they are rewarded, and whether those incentives really line up with your interests. See who runs Sanmina and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com