


EN
Applied Optoelectronics Stock Jumps Into Focus After Profit Turn And New Credit Facility
- Applied Optoelectronics reported third quarter 2026 sales of US$269.88 million compared with US$118.63 million a year ago, moving from a loss to net income of US$6.3 million and delivering US$0.07 in basic and diluted earnings per share from continuing operations.
- The business paired this profitability milestone with a new US$200 million credit facility and full year 2026 revenue guidance of US$385 million to US$420 million. This provides more room to fund capacity expansion even as cash burn remains a central risk metric.
- The focus now turns to how Applied Optoelectronics' investment narrative develops as heavy cash burn intersects with increased credit capacity and updated guidance.
What Is Applied Optoelectronics' Investment Narrative?
The simple belief you need with Applied Optoelectronics is that heavy spending today on next generation transceivers and manufacturing capacity eventually turns into durable cash generation, not just a one quarter profit print. The third quarter move to US$6.3 million in net income and US$0.07 per share from continuing operations, alongside nine month losses and ongoing cash burn, underlines how fine that balance still is. Management has paired strong recent sales with 2026 revenue guidance of US$385 million to US$420 million and a fresh US$200 million credit facility. As a result, near term catalysts now sit around execution on backed orders, pricing discipline with key customers, and whether production ramps can happen without eroding that new profitability.
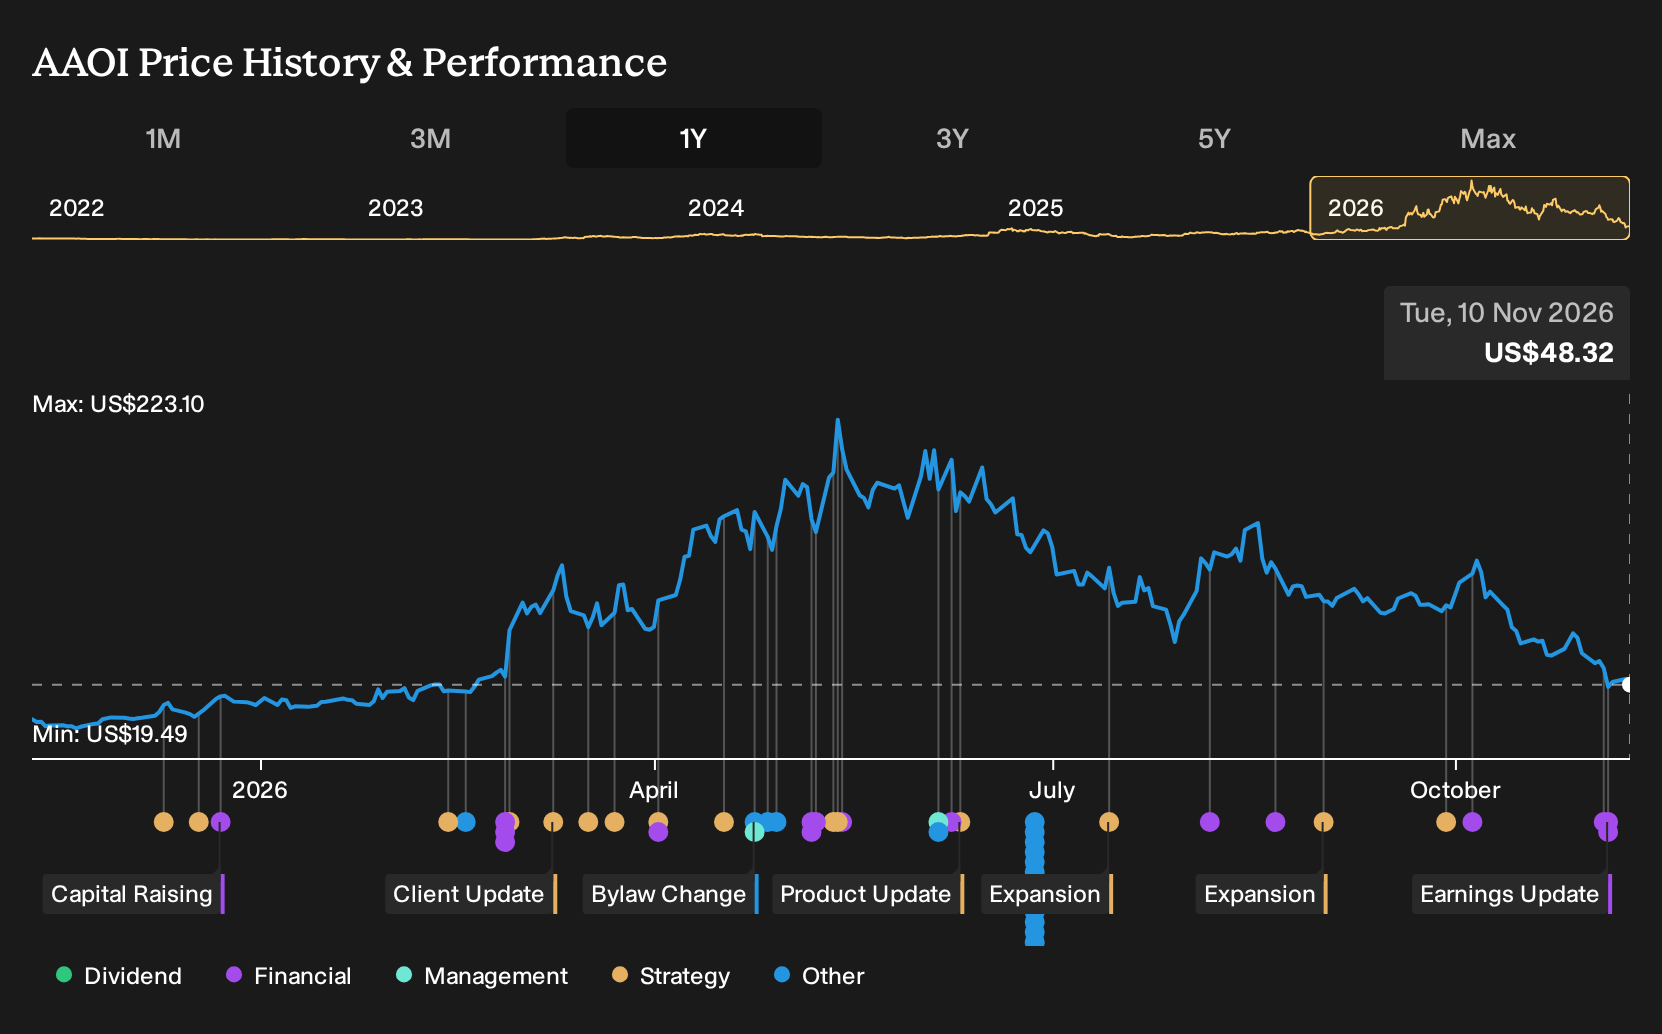
In the short term, the story is less about headline revenue and more about the quality of those dollars. Investors are watching whether Applied Optoelectronics can keep absorption high enough in its factories and avoid further heavy equity dilution while using a largely higher risk funding mix that leans on external borrowing. The credit agreement gives room to finance equipment and working capital. However, it also tightens the focus on covenants and leverage as the share price has been highly volatile and down more than 50% over the past month.
That said, there is a single pressure point in this whole setup that could quickly change how comfortable you feel about AAOI if ...
There's only one way to know the right time to buy, sell or hold Applied Optoelectronics. Head to Simply Wall St's company report for the latest analysis of Applied Optoelectronics's Fair Value.
Exploring Other Perspectives
One alternative view on Applied Optoelectronics focuses on customer concentration risk rather than cash burn. The lowest analysts were modeling roughly US$6.0b of revenue and US$1.5b of earnings by about 2029, which already looked punchy. Those forecasts came before this quarter's results and fresh guidance, so expectations on both sides of the debate may shift.
Explore 8 other Applied Optoelectronics fair value estimates, including one that suggests as much as 95% downside from the current price!
Reach Your Own Conclusion
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research based on your instincts.
- A great starting point for your Applied Optoelectronics research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Applied Optoelectronics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Applied Optoelectronics' overall financial health at a glance.
Looking For More Investment Ideas Beyond Applied Optoelectronics?
If the recent Applied Optoelectronics update has sharpened your thinking, it can be useful to widen the lens and compare this situation with other businesses that share similar traits or offer very different risk profiles. The Simply Wall St Screener lets you quickly filter for companies that match your preferences on quality, valuation, balance sheet strength, or income potential so you can pressure test your thesis rather than bet on a single story.
- If you want to concentrate on steadier balance sheets and fewer financial surprises, start with companies that pass a 30 resilient stocks with low risk scores filter and see how they stack up against AAOI's profile.
- For readers who prefer hunting for potential mispricings, scan through a curated set of 36 high quality undervalued stocks and compare their fundamentals to what you see at Applied Optoelectronics.
- If income is your priority, you can focus your research on businesses that have consistently paid shareholders by reviewing a group of 5 dividend fortresses and weighing that cash return against AAOI's reinvestment heavy story.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com