


EN
Is Permian Basin Royalty Trust (PBT) Fully Priced After Weaker Third Quarter Results?
Permian Basin Royalty Trust (PBT) reported third quarter 2026 results with lower revenue and profit than a year earlier, putting fresh attention on how this royalty-focused stock responds to shifts in underlying oil and gas activity.
Despite the weaker third quarter, Permian Basin Royalty Trust shares have been volatile recently, with a 9.67% 7 day share price return following a 12.13% decline over 30 days. However, the year to date share price return of 74.13% and 5 year total shareholder return of 329.13% suggest momentum has been strong over longer periods as investors reassess both income potential and risk around its royalty stream.
Spot check Permian Basin Royalty Trust against other oil and gas royalty plays by scanning our hand picked 33 elite gold producer stocks for potential peers with different risk and income profiles.Permian Basin Royalty Trust looks like a robust royalty vehicle on recent multiyear returns, yet the latest earnings softness and sharp share price swing raise a sharper question. Is that quality stream already fully reflected in today’s valuation?
Preferred Price-to-Earnings of 108.5x: Is it justified?
On Simply Wall St’s checks, Permian Basin Royalty Trust trades on a P/E of 108.5x, far richer than many oil and gas royalty peers despite a last close of $30.63. That gap between the share price and earnings base is front and center when you compare PBT with both its sector and its own recent profit trends.
The P/E ratio compares what investors pay for each dollar of earnings. For a royalty trust like Permian Basin Royalty Trust, which distributes income from oil and gas interests rather than reinvesting heavily, P/E becomes a quick shorthand for how much the market is willing to pay for that cash stream today.
PBT is described as expensive on this metric, with its 108.5x P/E far above the US Oil and Gas industry average of 10.5x and also above the peer average of 14.4x. That very large premium suggests buyers are paying a steep price relative to current earnings, especially given that earnings have declined by 9.1% per year over the past 5 years and fell 13.9% over the past year, while net profit margins eased from 88.5% to 85.5%.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 108.5x (OVERVALUED)
Still, the story around Permian Basin Royalty Trust can shift quickly if oil and gas production on its underlying acreage softens further, or if earnings keep trailing the current P/E premium.
Find out about the key risks to this Permian Basin Royalty Trust narrative.
Another View on Permian Basin Royalty Trust: What the DCF Says
That lofty P/E suggests investors are paying up for Permian Basin Royalty Trust. The SWS DCF model presents an estimated future cash flow value of $7.98 per unit versus the current $30.63 price, which screens as overvalued on this framework.
For readers who want to see how this cash flow view is built line by line, Look into how the SWS DCF model arrives at its fair value.
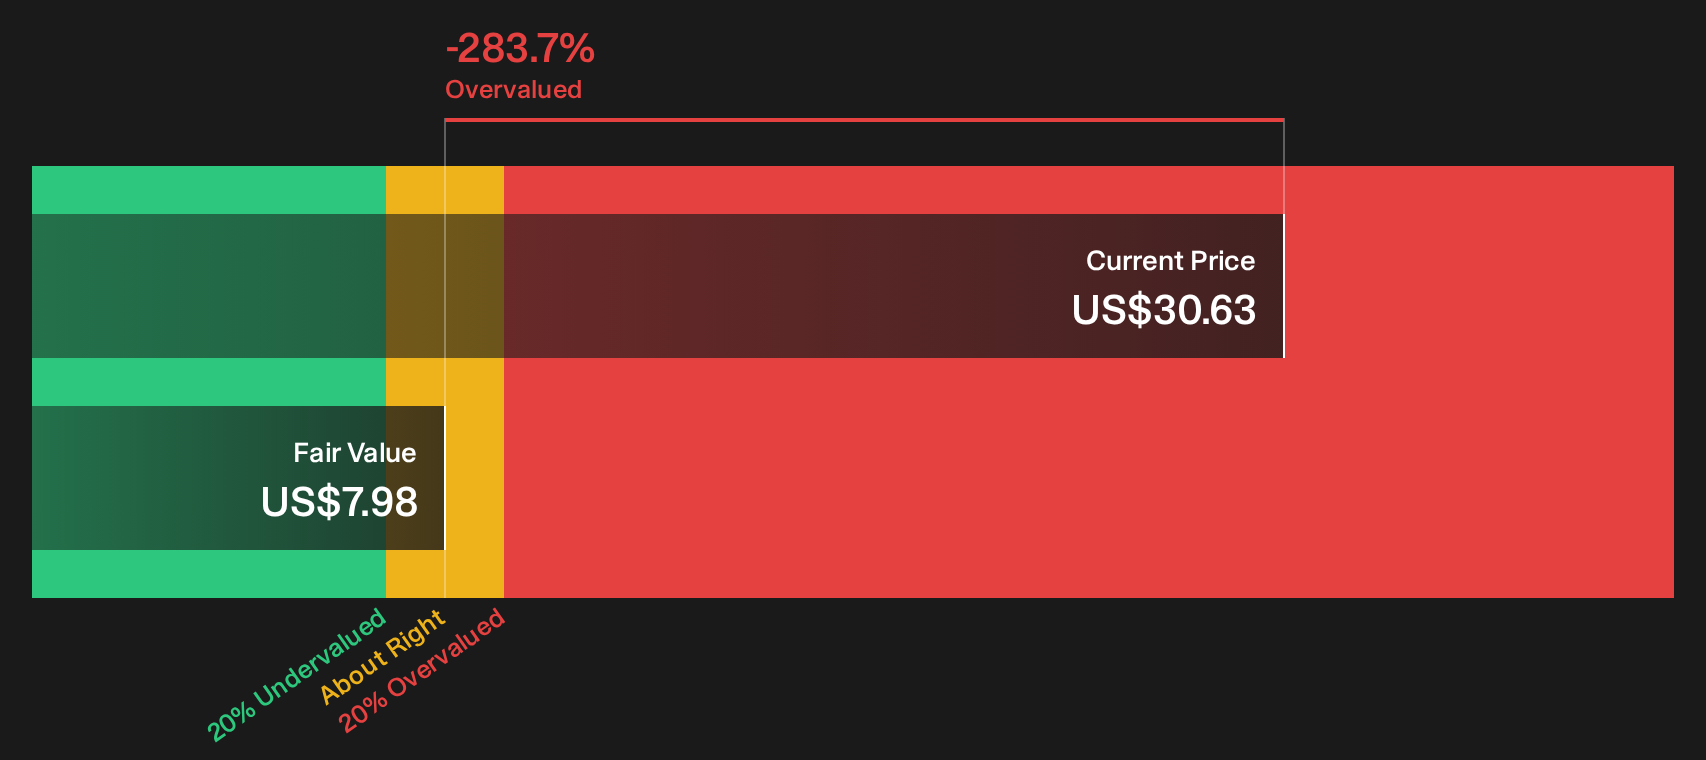
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Permian Basin Royalty Trust for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 36 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If you are concerned about how stretched Permian Basin Royalty Trust appears based on these checks, or if you interpret the numbers differently, consider acting promptly. Review the detailed risk flags and start with the 1 important warning sign
Looking for more investment ideas beyond Permian Basin Royalty Trust?
Do not stop at Permian Basin Royalty Trust. Broaden your watchlist with focused stock ideas filtered by quality, income potential, and balance sheet strength using the Simply Wall St screener.
- Target potential value opportunities by scanning a curated set of companies that screen as both high quality and attractively priced through the 36 high quality undervalued stocks.
- Strengthen your income focus by reviewing a group of higher yielding payers that aim for consistency through the 5 dividend fortresses.
- Prioritize resilience by filtering for businesses with sturdy finances and fundamentals using the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com