


EN
Should Earnings Beat Require Action From Viavi Solutions (VIAV) Investors?
- Viavi Solutions reported first quarter fiscal 2027 sales of US$469.3 million and net income of US$76 million, alongside new second quarter revenue guidance of US$505 million to US$515 million and a fresh US$500 million share repurchase authorization.
- The business paired that financial update with AI-focused testing upgrades in its NITRO AI portfolio and continued execution on prior buybacks, indicating active capital deployment and product development across both its test platforms and Network Digital Twin offerings.
- We will now see how Viavi Solutions' investment narrative could be influenced following this quarter’s earnings profile.
Scan beyond Viavi Solutions and explore other AI and network infrastructure plays on your radar by reviewing our hand picked 53 AI infrastructure stocks.
Viavi Solutions Investment Narrative Recap
To own Viavi Solutions, you need to believe the test and monitoring franchises can turn today’s optical and fiber demand into durable earnings, while acquisitions and new AI tools keep the portfolio relevant. The latest quarter, with US$469.3 million in sales and US$76 million in net income, reinforces that the business is currently executing from an earnings standpoint.
The key short term swing factor is still demand from data center, fiber and carrier customers. The analyst consensus Narrative on Simply Wall St treats this demand as part of multi year upgrade cycles. The biggest risk remains weaker or delayed spending in wireless and service provider markets, which could offset progress elsewhere, so this print does not remove that concern.
The new US$500 million share repurchase authorization sits alongside fresh guidance of US$505 million to US$515 million in second quarter revenue. For you as a shareholder, the practical question is whether core cash generation and balance sheet capacity comfortably support both ongoing buybacks and the acquisition and integration agenda already in motion.
That repurchase plan also interacts with risks flagged for Viavi Solutions around integration of prior deals and higher debt. If earnings growth or synergy delivery were to stall, an aggressive reduction in share count could constrain financial flexibility. The catalyst to watch is whether upcoming quarters show consistent profitability and cash flow that make these capital allocation choices look measured rather than stretched.
Viavi Solutions' current earnings are US$67.0 million, with analysts expecting revenue to grow at 18.0% a year and earnings to reach US$692.2 million by 2029, which implies an increase of about 10x from today. In this narrative, the business would be generating US$2.8b of revenue and US$692.2 million of earnings by 2029 if those assumptions play out.
Uncover how Viavi Solutions' fair value indicates an 87% potential upside to its current price before the market closes the gap.
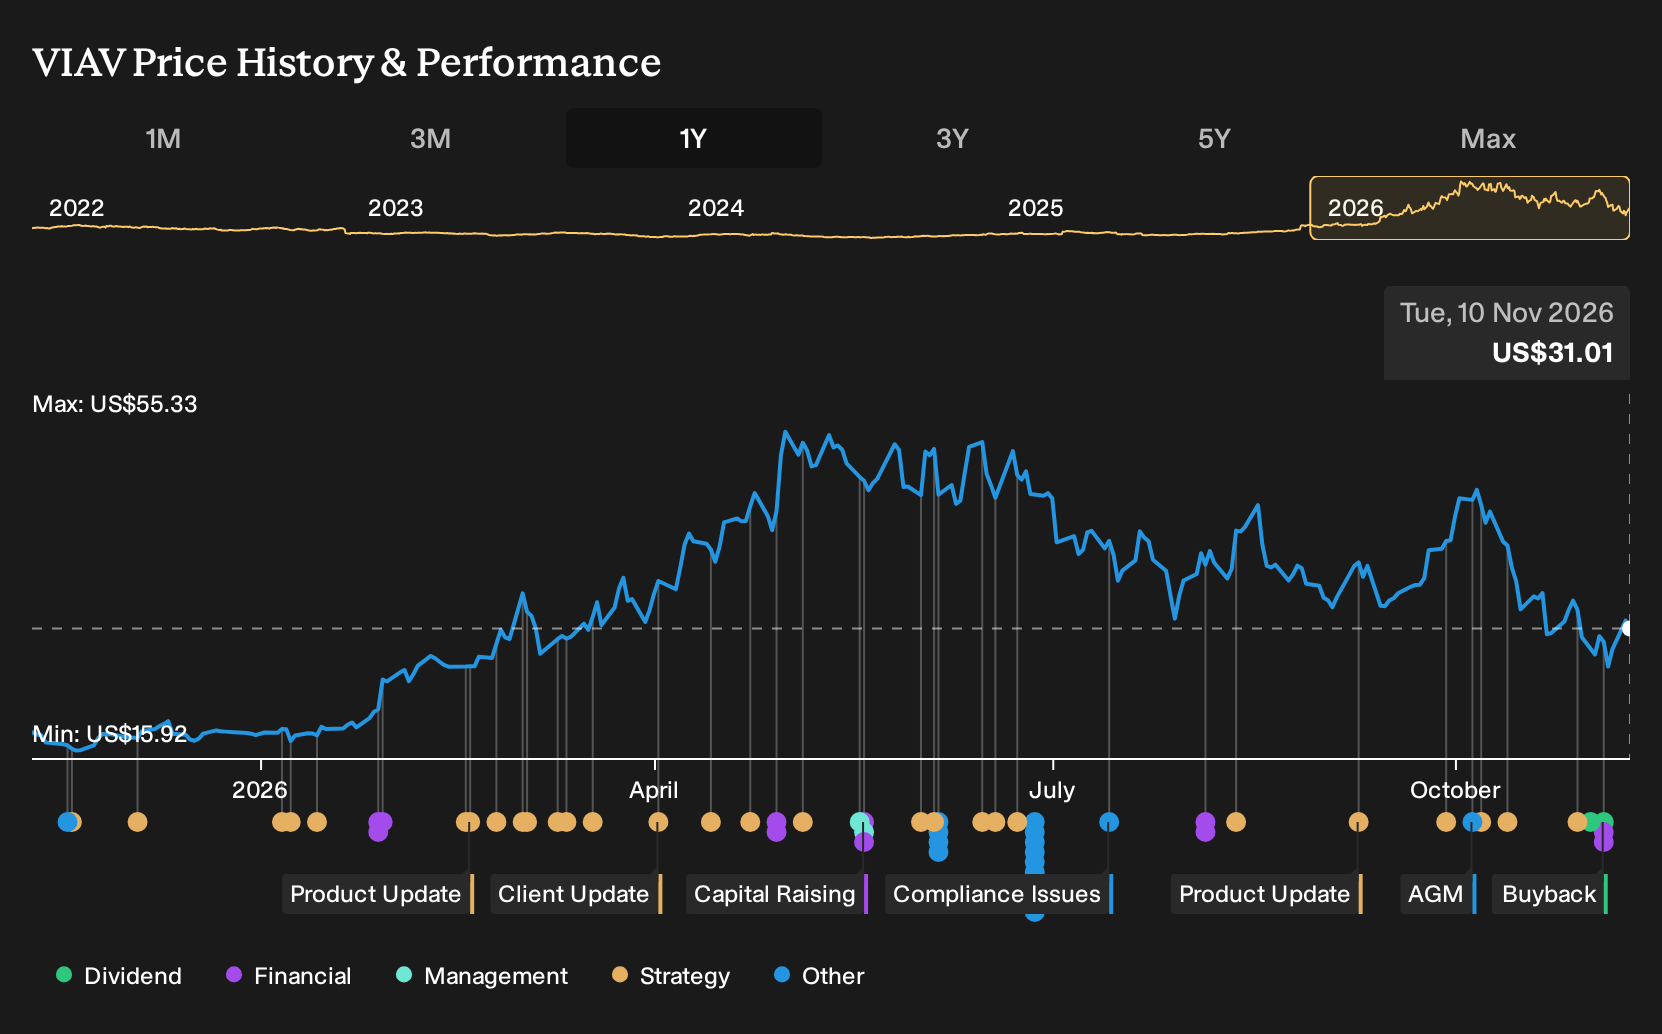
Exploring Other Perspectives
One alternative view focuses on Viavi Solutions' AI centric test platforms as the real swing factor. Bullish analysts were already pencilling in roughly US$2.6b of revenue and US$499.5 million of earnings by 2029, far above consensus. With this quarter’s AI and buyback news now on the table, those pre news assumptions may get revisited in very different ways. Investors look at the same facts and reach very different conclusions, so treat this as a prompt to compare several angles before deciding what the latest update means for you.
Explore 3 other Viavi Solutions fair value estimates, including one that suggests as much as 126% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so go with your instincts.
- A great starting point for your Viavi Solutions research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Viavi Solutions. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Viavi Solutions' overall financial health at a glance.
Looking for more investment ideas beyond Viavi Solutions?
Once you have a view on Viavi Solutions, it can help to widen the lens and compare it with other companies that match your risk profile and income goals. The Simply Wall St Screener lets you quickly filter for different traits so you can build a shortlist that actually fits the way you invest.
- If you want potential upside with tighter risk controls, start with a group of 30 resilient stocks with low risk scores that may better suit a steadier approach.
- For investors hunting for value backed by fundamentals, scan through our 36 high quality undervalued stocks and see which businesses you want to research next.
- If you care most about balance sheet strength, build your watchlist from a list of solid balance sheet and fundamentals (24 results) and focus your time on companies with financial resilience.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com