


EN
Penguin Solutions (PENG) Stock Dropped, So What Is Driving Attention Today?
Penguin Solutions (PENG) has put high performance AI hardware in the spotlight by pairing its upcoming SC26 showcase of the Full Stack AI Factory Platform with a fresh DDR5 MRDIMM launch for AI data centers.
Despite the SC26 spotlight and fresh AI hardware announcements, Penguin Solutions’ share price has recently come under pressure. The stock is down 16.1% over the past week and 41.5% over the past month. However, the year-to-date share price return of 120.1% and 1-year total shareholder return of 113.9% still point to strong longer term momentum that continues to shape how investors view its growth prospects and risks.
See how Penguin Solutions compares with other AI infrastructure companies by reviewing the hand picked 53 AI infrastructure stocks that are catching investors’ attention right now.
After a 41.5% slide in a month that still leaves Penguin Solutions up sharply over 12 months, the real tension is simple: does this pullback already reflect the risks, or is patience on a better entry price worth it as the valuation picture comes into focus next?
Most Popular Narrative: 48% Undervalued
On the analyst consensus Narrative on Simply Wall St, Penguin Solutions’ fair value sits at $85.63 compared with the last close of $44.64. That gap frames the entire discussion around what its AI centric mix and capital structure might deliver over time.
Increasing demand for scalable and energy efficient data center solutions is now coupled with a shift to AI factories. Penguin Solutions’ Full Stack AI Factory Platform, its recognition as an NVIDIA AI Factory Specialized Partner, and its role in helping partners deliver over US$3.45b of contracted AI infrastructure projects together point to further mix shift toward higher value AI solutions that can support gross margin and earnings.
See why 36 investors see Penguin Solutions as 48% undervalued.
Result: Fair Value of $85.63 (UNDERVALUED)
Still, the bullish Penguin Solutions story runs into two clear risks: heavy working capital tied up in receivables and inventory, and future dilution from 0% convertible notes.
Find out about the key risks to this Penguin Solutions narrative.
Another View: Cash Flow Paints A Tougher Picture
The P/E based fair value of $85.63 presents Penguin Solutions as materially undervalued, yet the Simply Wall St DCF model tells a very different story. On that measure, the shares at $44.64 trade above an estimated future cash flow value of $30.66, which suggests less upside and more valuation risk if cash generation lags expectations.
Our DCF model is only as strong as the assumptions that go into it, so it is worth stress testing those cash flow inputs for yourself. You could start by considering how receivables, inventory and future dilution might affect free cash flow over time, and then weigh that against the earnings based view that points to underpricing.
Look into how the SWS DCF model arrives at its fair value.
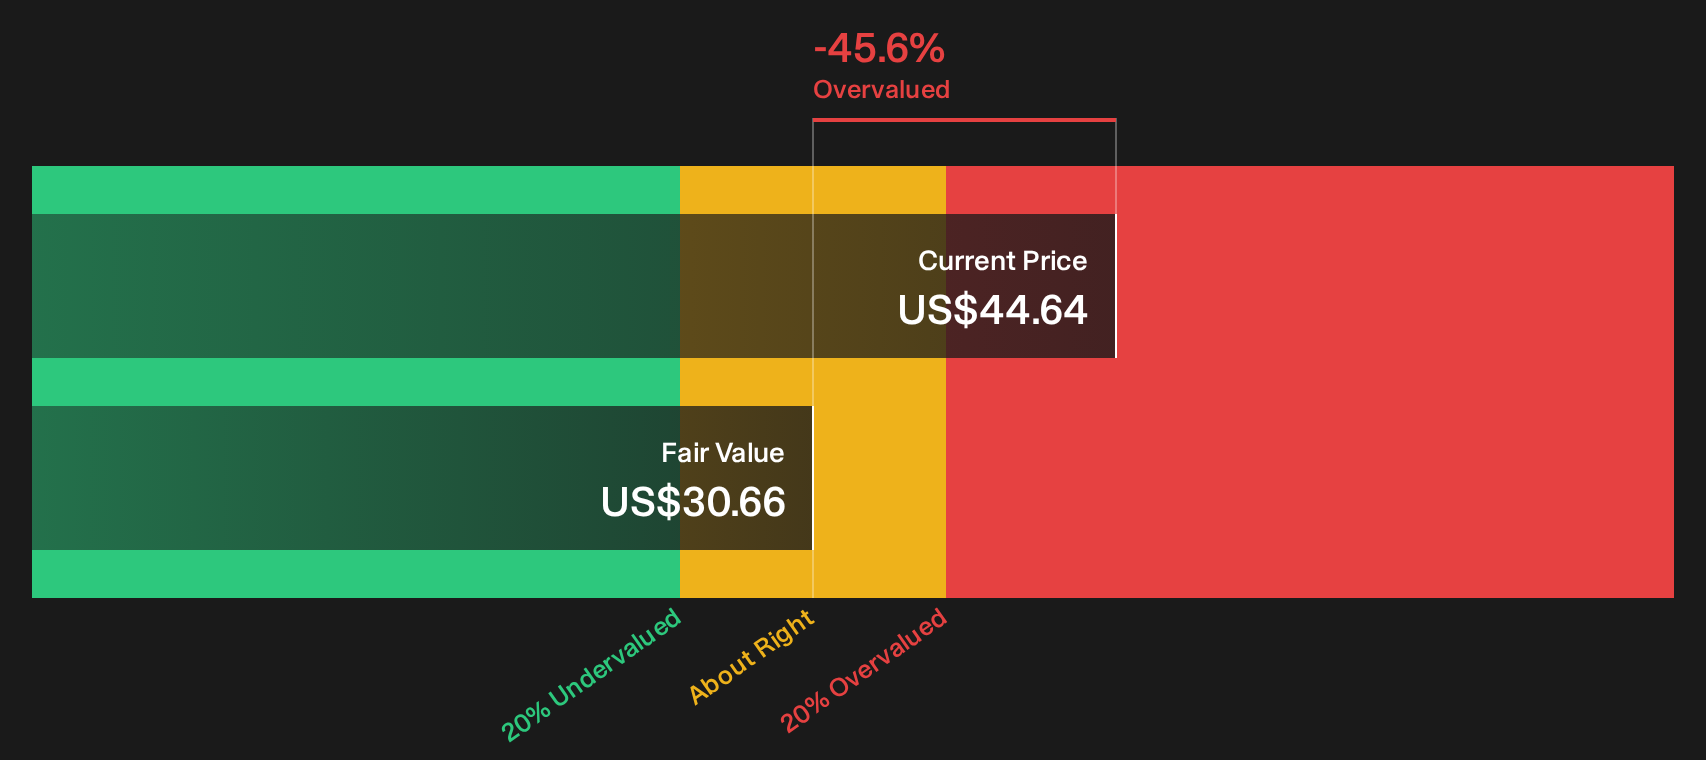
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Penguin Solutions for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 36 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Penguin Solutions can feel confusing. Move quickly to check the underlying data, weigh the downside and upside, and then judge it on your own terms by reviewing the 5 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Penguin Solutions?
If Penguin Solutions has sharpened your focus on AI infrastructure, now is the moment to broaden your watchlist with a few targeted screens that highlight different strengths.
- Target resilient cash generation by scanning companies with a history of meeting obligations and cushioning downturns through the list of solid balance sheet and fundamentals (24 results).
- Hunt for potential mispricings by reviewing the 20 high quality undiscovered gems that pair quality fundamentals with relatively low market attention.
- Lower portfolio stress by filtering for businesses that score well on stability and risk controls inside the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com