


EN
Intact Financial (TSX:IFC) Could Be 11% Undervalued As Results Highlight Resilience
Intact Financial (TSX:IFC) is back in focus after its latest quarterly update, which paired a 94% combined ratio and resilient regional performance with fresh commentary on AI investments and plans to expand recurring earnings.
Recent trading suggests momentum is rebuilding in Intact Financial, with a 1-month share price return of 14.51% and a 7-day gain of 5.60% from a year to date share price decline of 2.71%. The 5-year total shareholder return of 82.69% reflects a much stronger longer run outcome.
Capitalize on Intact Financial's momentum and income story by scanning a curated list of insurers and financials with resilient balance sheets and recurring cash flows in the list of solid balance sheet and fundamentals (5 results).After that sharp rebound and a rich history of total returns, Intact Financial now asks a blunt question of new money: Is the current price still skewed toward reward, or has the balance shifted toward risk?
Most Popular Narrative: 11% Undervalued
On the analyst consensus Narrative on Simply Wall St, Intact Financial screens as undervalued, with a fair value of CA$310.54 against the last close at CA$277.45, so the gap between price and modeled cash flows remains meaningful.
Ongoing expansion of global specialty and US platforms, with about C$7b of specialty premiums written at a sub 90% combined ratio and a target of at least C$10b by 2030, alongside verticals that operate in the 70s to low 80s combined ratio range, is cited as positioning Intact Financial to grow premiums while supporting earnings quality.
See why 46 investors see Intact Financial as 11% undervalued.
Result: Fair Value of CA$310.54 (UNDERVALUED)
Still, the Intact Financial narrative could be knocked off course if catastrophe losses stay above guidance for longer, or if UK&I underwriting lags behind expectations for improvement.
Find out about the key risks to this Intact Financial narrative.
Another View: Intact Financial Through The P/E Lens
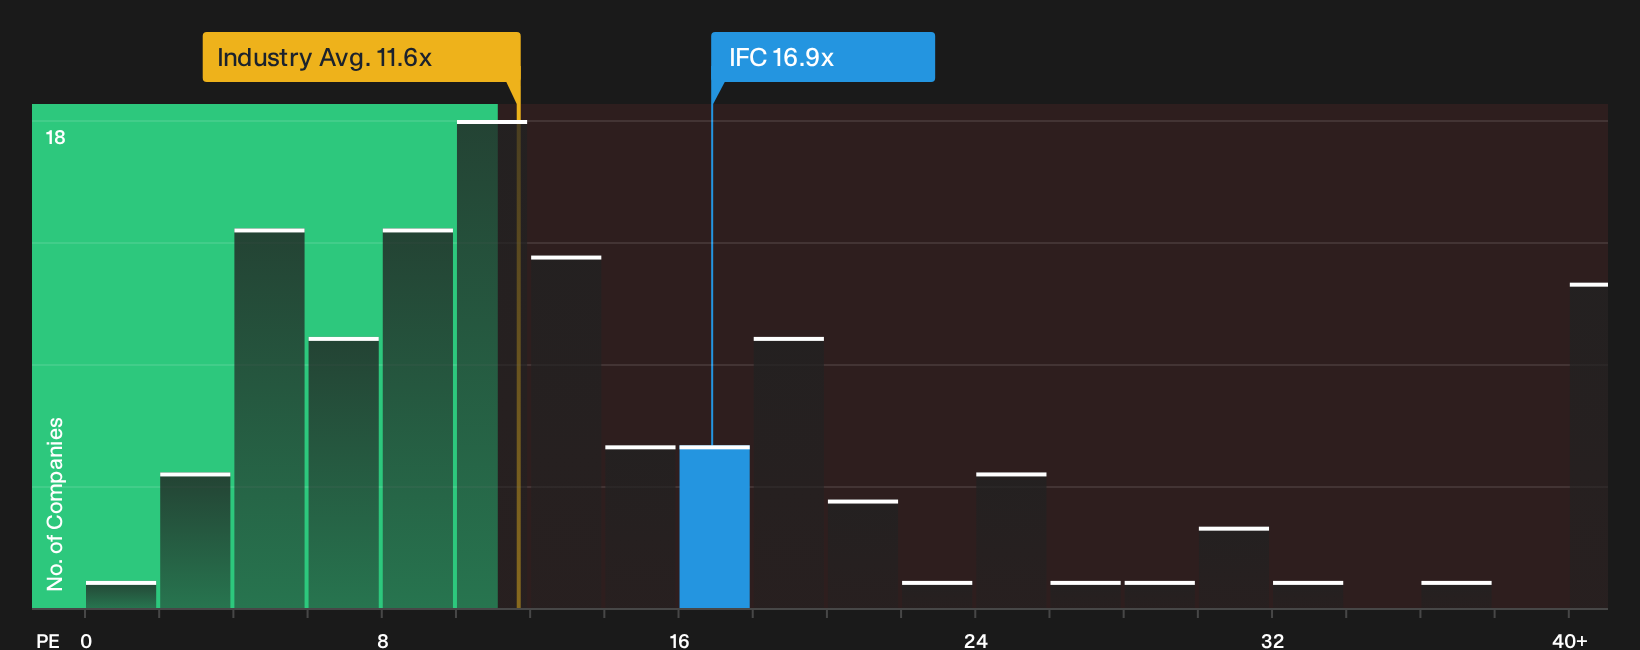
There is a very different message when you move from cash flows to earnings multiples. Intact Financial trades on a P/E of 16.9x, while the broader North American insurance group sits nearer 11.6x and its own fair ratio is 14.4x, so the stock carries a valuation premium that could matter if sentiment cools.
The gap versus peers points to investors already paying up for perceived quality, even though the share price is below some modeled fair values. That leaves a simple question for you to answer: Is that premium a comfort or a margin of error waiting to be tested?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
With sentiment on Intact Financial divided between reward potential and valuation risk, move quickly to stress test the upside story against the detailed reward drivers in the 3 key rewards.
Looking For More Investment Ideas Beyond Intact Financial?
If Intact Financial has your attention, do not stop here. Broaden your watchlist with fresh ideas so you are not relying on a single story.
- Target steady value by scanning a focused set of quality companies that currently look attractively priced in the 5 high quality undervalued stocks.
- Explore income opportunities by lining up businesses with robust payouts and consistency in the 3 dividend fortresses.
- Manage portfolio risk by filtering for businesses with resilient finances and lower overall risk in the 9 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com