


EN
What Real Matters Bears Saw Before The Fall
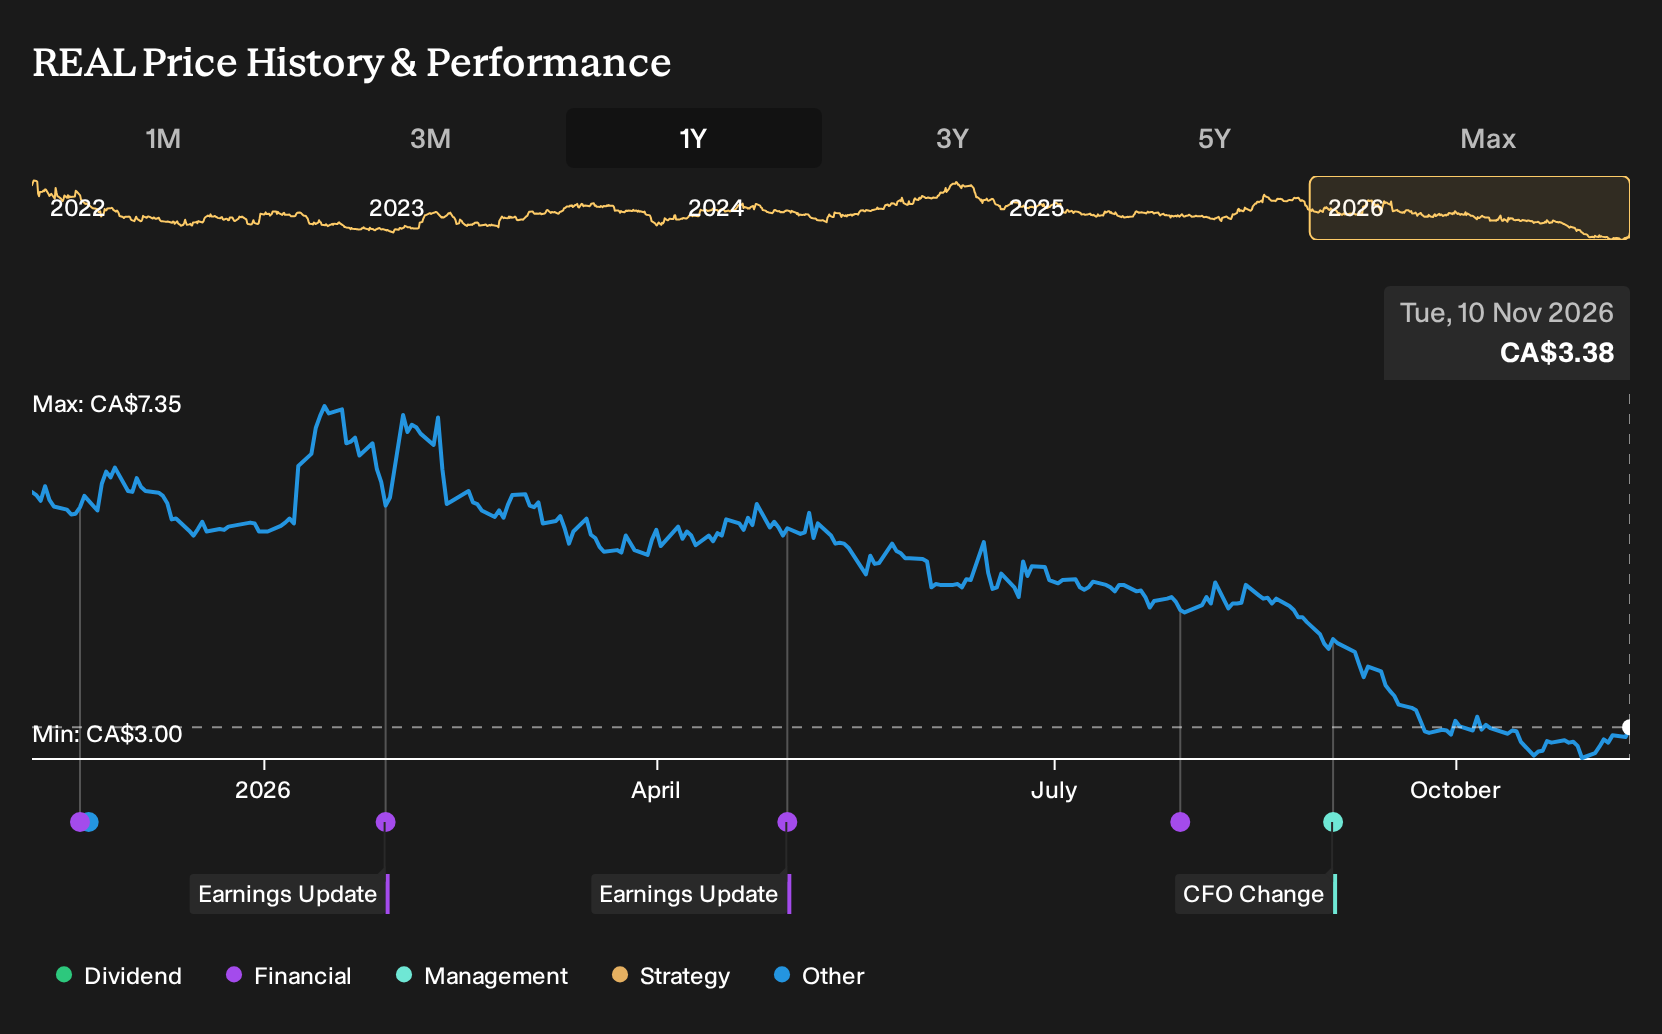
Real Matters has just told investors when to expect its next set of quarterly numbers, with a Q3 2026 release and conference call scheduled for July 30. For Real Matters shareholders, the loss over the past year was 45.3%, including dividends. If you had bought on 10 November 2025, that drop is the reality to explain. The key question now is whether upcoming results can support renewed confidence in the business model.
Real Matters has already moved. See which of 5 high quality undervalued stocks still trade below our estimates.
The Two Stories Investors Were Weighing On Real Matters
The shares cost CA$6.25 at the start of the period, and the Real Matters debate quickly split into two credible stories about what might come next.
The bullish narrative saw a tech focused platform winning more Tier 1 lenders, with a Fair Value of CA$7.18 that reflected assumptions about revenue rising 19.6% a year and profit margins lifting to 8.3%.
The cautious view pointed to subdued mortgage activity and client concentration, with a Fair Value of CA$5.72 and concern that competition and alternative digital valuation tools could pressure pricing and earnings stability.
What The Results Changed For Real Matters
The clearest new datapoint for Real Matters was the swing in profitability. Net income moved from a loss of US$4.854 million in Q3 2025 to a profit of US$1.019 million in Q3 2026, and net margin shifted from 10.7% negative to 2.0% positive. That supported the optimistic case on execution, although the cautious story around mortgage exposure remained untested by this single quarter.
The useful takeaway here is simple. When a thesis leans on better margins, treat net income and net margin as the key claims to check in future filings, not just the revenue line or share price moves.
What Real Matters' Lower Price Asks You To Believe
Real Matters now trades at CA$3.38, after a 45.3% loss over the past year from CA$6.25. The analyst consensus Narrative on Simply Wall St sees its Fair Value above that level, based on how U.S. Title and U.S. Appraisal could contribute to future profitability.
The distinctive thread in that Narrative is the bet on Tier 1 penetration, refinance sensitive volumes and UAD 3.6 readiness offsetting margin and cost pressure. A buyer today would need to judge that these segment level gains and technology investments can turn the share price fall into an opportunity rather than a warning.
"The combination of a debt free balance sheet and cash of more than $40 million gives Real Matters capacity to keep funding AI and platform investments that target efficiency gains in appraisal and title processing, which can support future net revenue margin resilience and consolidated earnings."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Real Matters And A Different Angle
Real Matters is trying to make real estate workflows cleaner and less manual. You could also look at a cousin problem nearby.
Property deals still hinge on how easily someone can buy or sell a home. Friction in that process can reduce the need for title and appraisal support.
One digital player focuses on controlling that transaction moment. It uses data, pricing models and a web platform to manage entire home trades.
This push to streamline listings and closings shifts where value sits along the chain. If it changes seller expectations, Real Matters' role could feel different too.
That argument has a Narrative and a number behind it. → See the company one Narrative values 199% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com