


EN
Is Ross Stores (ROST) Above Fair Value On Its Cash Flows?
Ross Stores has delivered a powerful run for shareholders in recent years, and that kind of climb naturally prompts a closer look at whether the current price lines up with the cash the business can generate. With the stock near recent highs, the key issue now is how its cash flows stack up against what buyers are being asked to pay today.
- Over the past 5 years the stock has returned 119.4%, which puts a lot of expectations into the price and makes the link between share performance and underlying cash generation a central question.
- Recently reported revenue growth of 13.3% and a 70.5% rise in earnings per share suggest stronger profitability, which can support higher cash flows and may influence what investors consider a reasonable valuation multiple on those cash streams.
- Prefer to judge Ross Stores on earnings? See what Ross Stores's 28.7x P/E says about the price.
For investors, the debate is whether Ross Stores' current share price is adequately backed by the future cash flows implied by a Discounted Cash Flow (DCF) view.
If you want more ideas that start with the same simple question as Ross Stores, namely whether today's price is justified by its cash flows, run your filters through the 37 high quality undervalued stocks
Has Ross Stores Run Too Far on Cash Flow?
The Discounted Cash Flow (DCF) model here takes the cash Ross Stores can return to shareholders and projects it forward. Latest twelve month free cash flow sits around $2.8b, and the projections used in this 2 Stage Free Cash Flow to Equity setup assume growing cash generation over the next decade rather than a shrinking base.
Analyst forecasts feeding into the DCF point to higher free cash flow in future years, with later estimates gradually easing in growth rates. This pattern is typical for a mature, profitable retailer like Ross Stores. On those assumptions, the DCF output points to an estimated intrinsic worth that is meaningfully below the current share price of $238.95. Because recent news highlights 13.3% revenue growth, a 70.5% jump in earnings per share and low net debt, the premium implied by the DCF helps explain why the market is comfortable paying up for the stock at the moment. Find out what Ross Stores could be worth using our Discounted Cash Flow (DCF) estimate.
The Ross Stores Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Ross Stores valuation puzzle leaves off by spelling out which paths for growth, margins and earnings would need to play out for the share price to look materially higher or lower than today. Each narrative ties its number to a concrete view of how Ross Stores' expansion prospects, profitability and risks might evolve, which you can then revisit as fresh information comes through.
Ross Stores splits opinion because one side sees underappreciated cash generation and traffic strength, while the other worries about paying up for a smaller off price player.
Bull case: 12% undervalued
According to the analyst consensus Narrative on Simply Wall St, Ross Stores could have more to give if recent operating momentum holds.
"Continued broad-based customer growth, with double digit increases in shopper counts across income levels, age groups and ethnicities and higher transaction counts driving recent comparable sales, could extend Ross Stores revenue and earnings..."
Discover why this Narrative puts Ross Stores at 12% undervalued.
Bear case: 220% overvalued
Esteban, a Simply Wall St Community investor who wrote the Narrative, argues the risk is paying too much for a smaller off price chain.
"The reason not to overpay for it is that Ross is the structurally smaller player in a business where buying scale is the moat itself..."
Explore why this Narrative puts Ross Stores at 220% overvalued.
One more Ross Stores signal that deserves a closer look
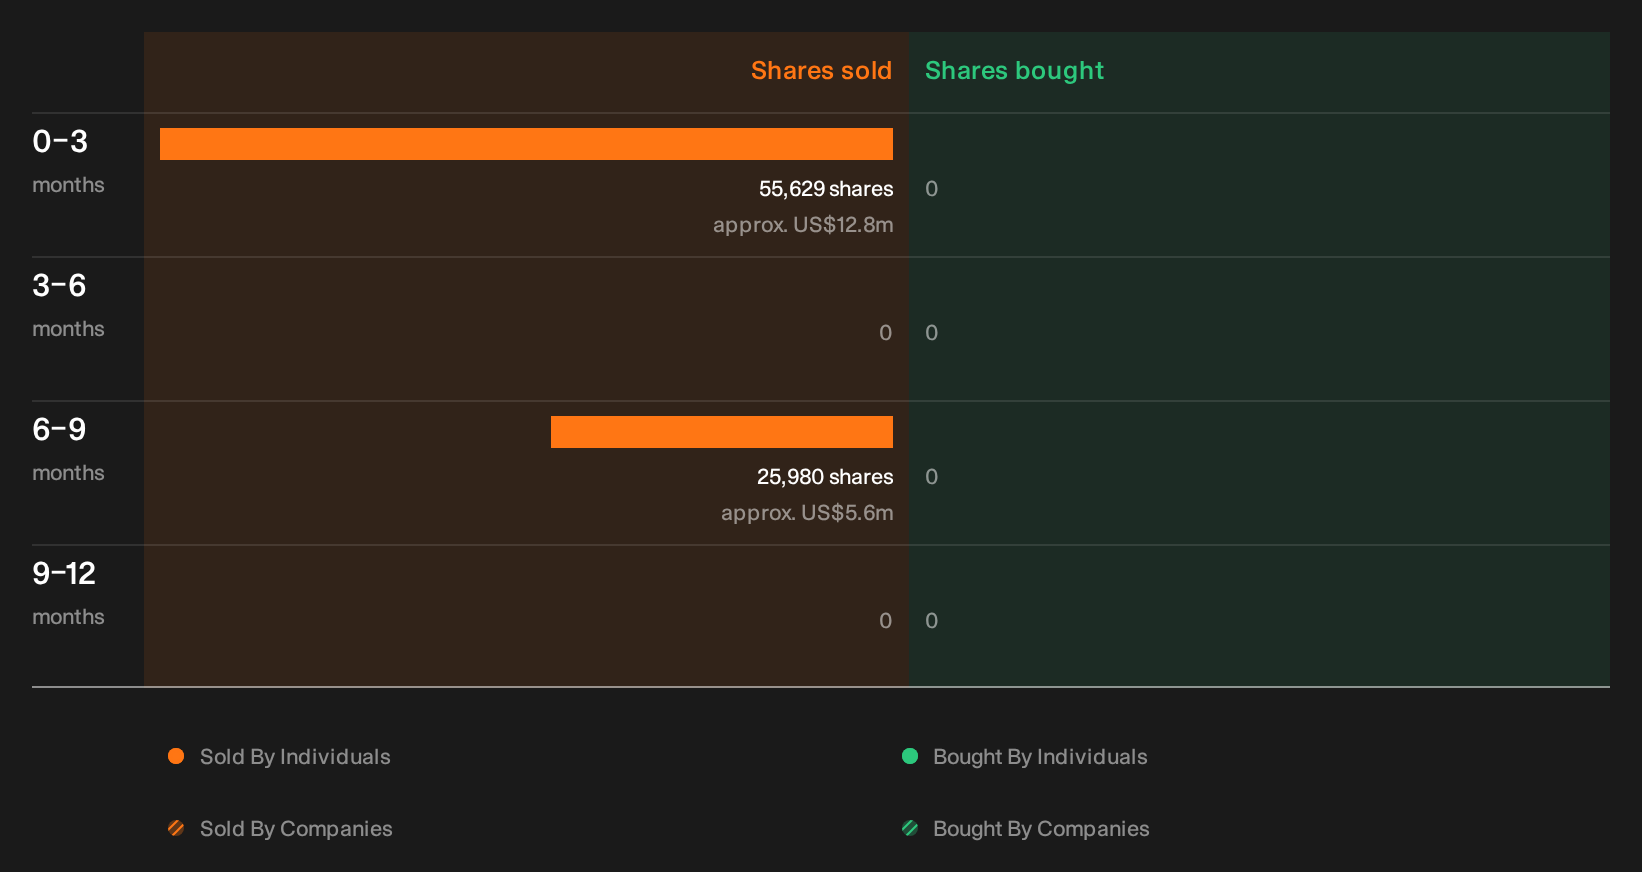
There is one more angle on Ross Stores that sits away from cash flows and Narratives. It involves recent moves by its own insiders, where the individuals, scale and possible read across are waiting for you to review. See the recent insider selling flagged for Ross Stores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com