


EN
Is AMETEK (AME) Undervalued After Raised Guidance And Stronger Asia Revenue?
AMETEK (AME) is back in focus after stronger international revenue, especially in Asia, coincided with raised sales and earnings guidance for 2026 and fresh quarterly results that reinforced existing analyst optimism.
Despite a softer 7-day and 90-day share price return, down 4.13% and 7.82% respectively, AMETEK now trades at US$238.31 after a year-to-date share price gain of 13.95%. Total shareholder return over 1, 3 and 5 years of 21.32%, 56.99% and 74.08% points to momentum that has built over time as investors weigh the stronger international revenue, higher 2026 guidance, steady dividends and recent boardroom changes together.
Scan how AMETEK’s international story compares with other industrial players by reviewing a curated list of solid balance sheet and fundamentals (24 results) in similar sectors.
Short term weakness against a backdrop of higher 2026 guidance and solid international momentum puts AMETEK at an interesting crossroads. Are you looking at a business reset, or just sentiment catching its breath before valuation does the explaining?
Most Popular Narrative: 16% Undervalued
On the analyst consensus Narrative on Simply Wall St, AMETEK’s fair value sits at $284.72 against a last close of $238.31. This frames the current setup as materially discounted while still hinging on specific execution risks and assumptions.
The main thing that has to go right is continued delivery on acquisitive growth and integration, including realizing planned cost synergies and cash EPS accretion from platforms such as Indicor while maintaining strong margins and cash conversion.
See why 20 investors see AMETEK as 16% undervalued.
Result: Fair Value of $284.72 (UNDERVALUED)
Still, the bullish AMETEK story can crack if the premium P/E multiple compresses or if acquisitions like Indicor underdeliver on margin and cash expectations.
Find out about the key risks to this AMETEK narrative.
Another View on AMETEK’s Valuation
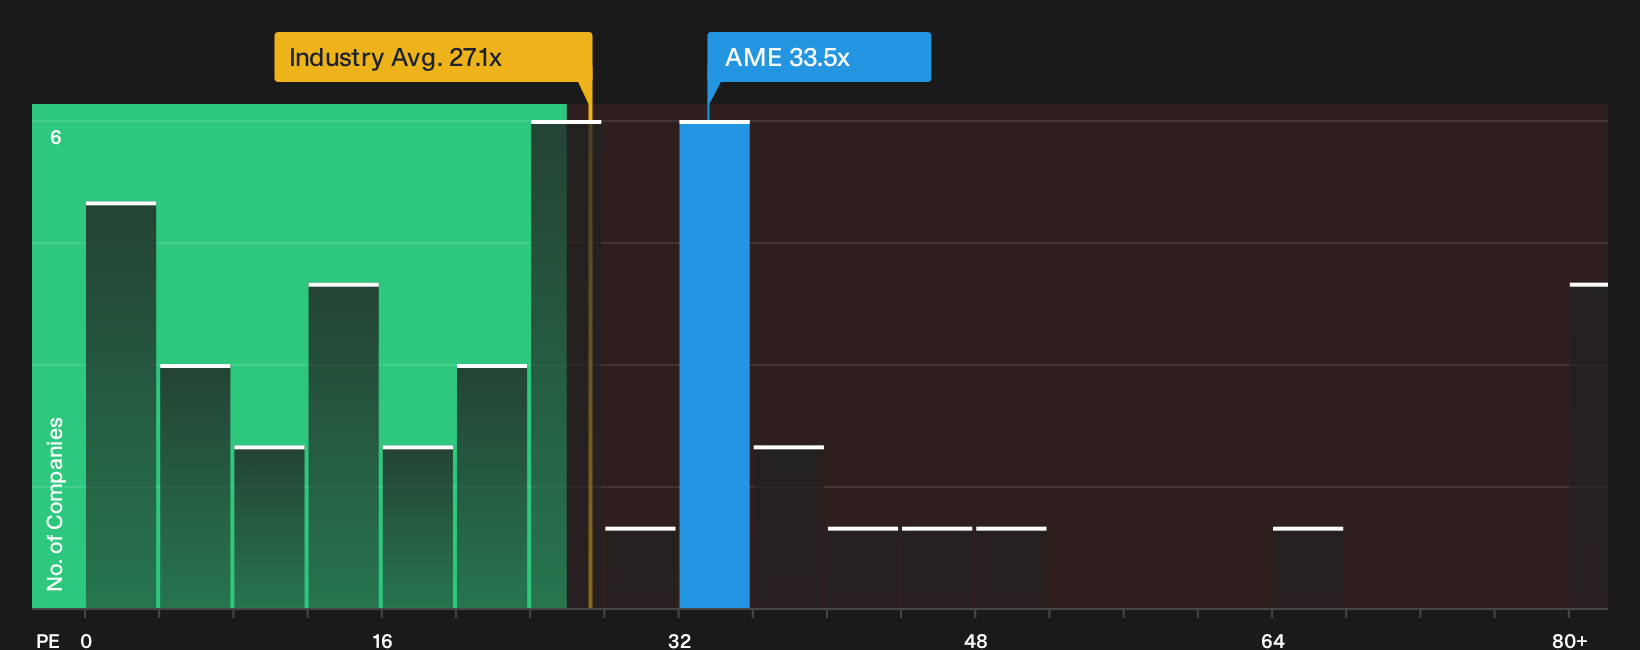
Analysts on Simply Wall St call AMETEK roughly 16% undervalued at a fair value of $284.72, yet the stock trades on a P/E of 33.5x versus a fair ratio of 26.1x, above both the US Electrical industry at 27.1x and peers at 31.8x. Is that premium a cushion or a crack in the story?
For a closer look at how this pricing gap shows up in the numbers, have a look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages around AMETEK’s premium P/E and fair value estimates only matter if you turn them into a clear stance of your own. Act while the numbers and narratives are fresh, and weigh up the 3 key rewards and 1 important warning sign.
Looking for more ideas beyond AMETEK?
If AMETEK has sharpened your thinking, do not stop there. Broaden your watchlist with fresh ideas that match the kind of portfolio you want to build.
- Target potential mispricing by scanning a focused group of quality companies using the 37 high quality undervalued stocks.
- Strengthen your income stream by reviewing a curated set of high-yield opportunities through the 5 dividend fortresses.
- Dial down portfolio stress and concentrate on resilience by filtering companies with steadier profiles in the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com