


EN
Sea (NYSE:SE) Stock Price Contrasts Strong Q3 Earnings With Margin Doubts
Sea entered its Q3 2026 earnings with its stock already under pressure, down over 40% across the past three months, and the immediate verdict today was more selling, with the share price slipping another 1.5% to US$76.80. That reaction came even as the group posted roughly US$8.6b in revenue and US$502m in net income, alongside what management described as Shopee’s most profitable quarter.
The core issue is a clash in sentiment. Traders are still reacting to a premium P/E and softer margins, while the actual earnings report points more toward solid execution than outright disappointment.
Love Sea’s revenue scale and its profitable Shopee quarter, but concerned about paying up for a premium P/E with softer margins in the mix? Compare this setup with a curated group of companies in our 37 high quality undervalued stocks
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$8.58b vs. US$5.99b (up about 43%)
- Net Income, Excl. Extra Items (Q3 2026 vs. Q3 2025): US$502.46m vs. US$374.99m (up about 34%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$0.81 vs. US$0.63 (up about 29%)
- Adjusted EBITDA, Group Level (Q3 2026 vs. Q3 2025): US$931m vs. roughly US$721m (up about 29%)
Sea just added a $1B buyback on booming Shopee and Monee. Ask Charlie which Sea growth driver really funds Sea Cloud.
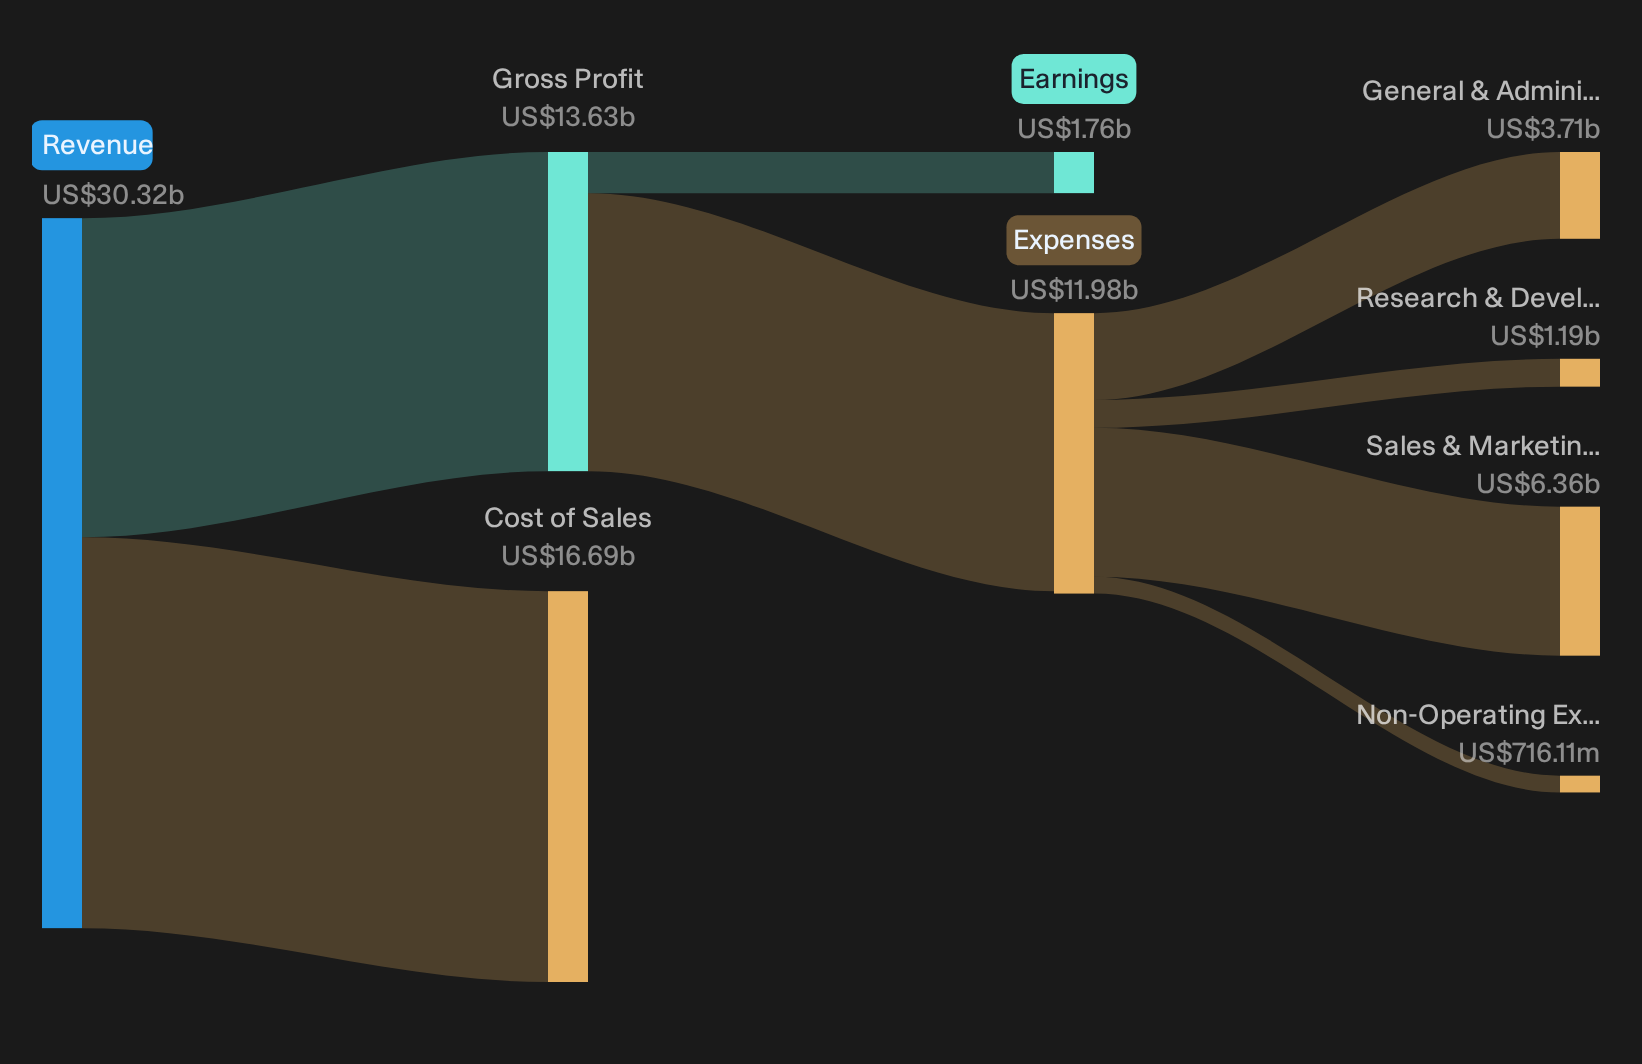
Sea’s Bull Case: Ecosystem Milestones Put To The Test
The bullish analyst Narrative on Simply Wall St pins a lot on Sea turning its three engines into a tighter profit machine.
"Bullish analysts expect Sea to compound Shopee, Monee, and Garena into a stronger, more profitable ecosystem, supported by rising Shopee monetization, an expanding AI-led credit franchise, and a growing portfolio of gaming titles."
On that score, Shopee’s record adjusted EBITDA, VIP members reaching 21m with approximately 80% retention, and ad take rate gains show clear progress on marketplace monetization. Monee adds evidence with US$1.6b in GAAP revenue, a US$12.6b loan book and a 1.3% 90 day NPL ratio. Meanwhile, Garena’s higher bookings and EBITDA signal that gaming is still pulling its weight in the ecosystem story.
The price and this Narrative do not agree. → Uncover what this Narrative says Sea is actually worth.
Sea Bear Case: Margin Fears Meet Mixed Evidence
The bearish analyst narrative on Simply Wall St argues that Shopee’s push into faster logistics could choke margin progress just as scale arrives.
"Although Shopee is benefiting from rising online retail adoption in Southeast Asia and Brazil, expanding instant and same day delivery and fulfillment requires continued upfront spend. This could limit how much of Shopee’s GMV scale flows through to net margins and earnings."
Sea’s Q3 print cuts both ways. Shopee posted its most profitable quarter with adjusted EBITDA of US$269m and GMV of US$39.7b, so efficiency clearly improved. At the same time, adjusted EPS of US$0.78 fell short of the US$0.99 consensus and the stock slipped about 1.5% on the day, which supports the view that investment-heavy logistics may keep group earnings below bullish expectations.
Hunt Mispriced Earnings Setups
Sea shows that earnings strength and share price reaction can diverge. The real opportunity is in stocks that might be undervalued before the market corrects them.
- Company 1 - 16% below our estimate - expand overseas teahouses while balancing same store GMV, franchise returns and company store cost ratios.
- Company 2 - 43% below our estimate - deploy advanced ATMs and retail automation so rising transaction volumes drive higher margin software and services revenue.
- Company 3 - 40% below our estimate - shift capital from a divested label into higher margin brands, cost programs and shareholder distributions.
Those are three of them. See the full list of 37 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com