


EN
Will Growth Call Change GameStop Stock Narrative
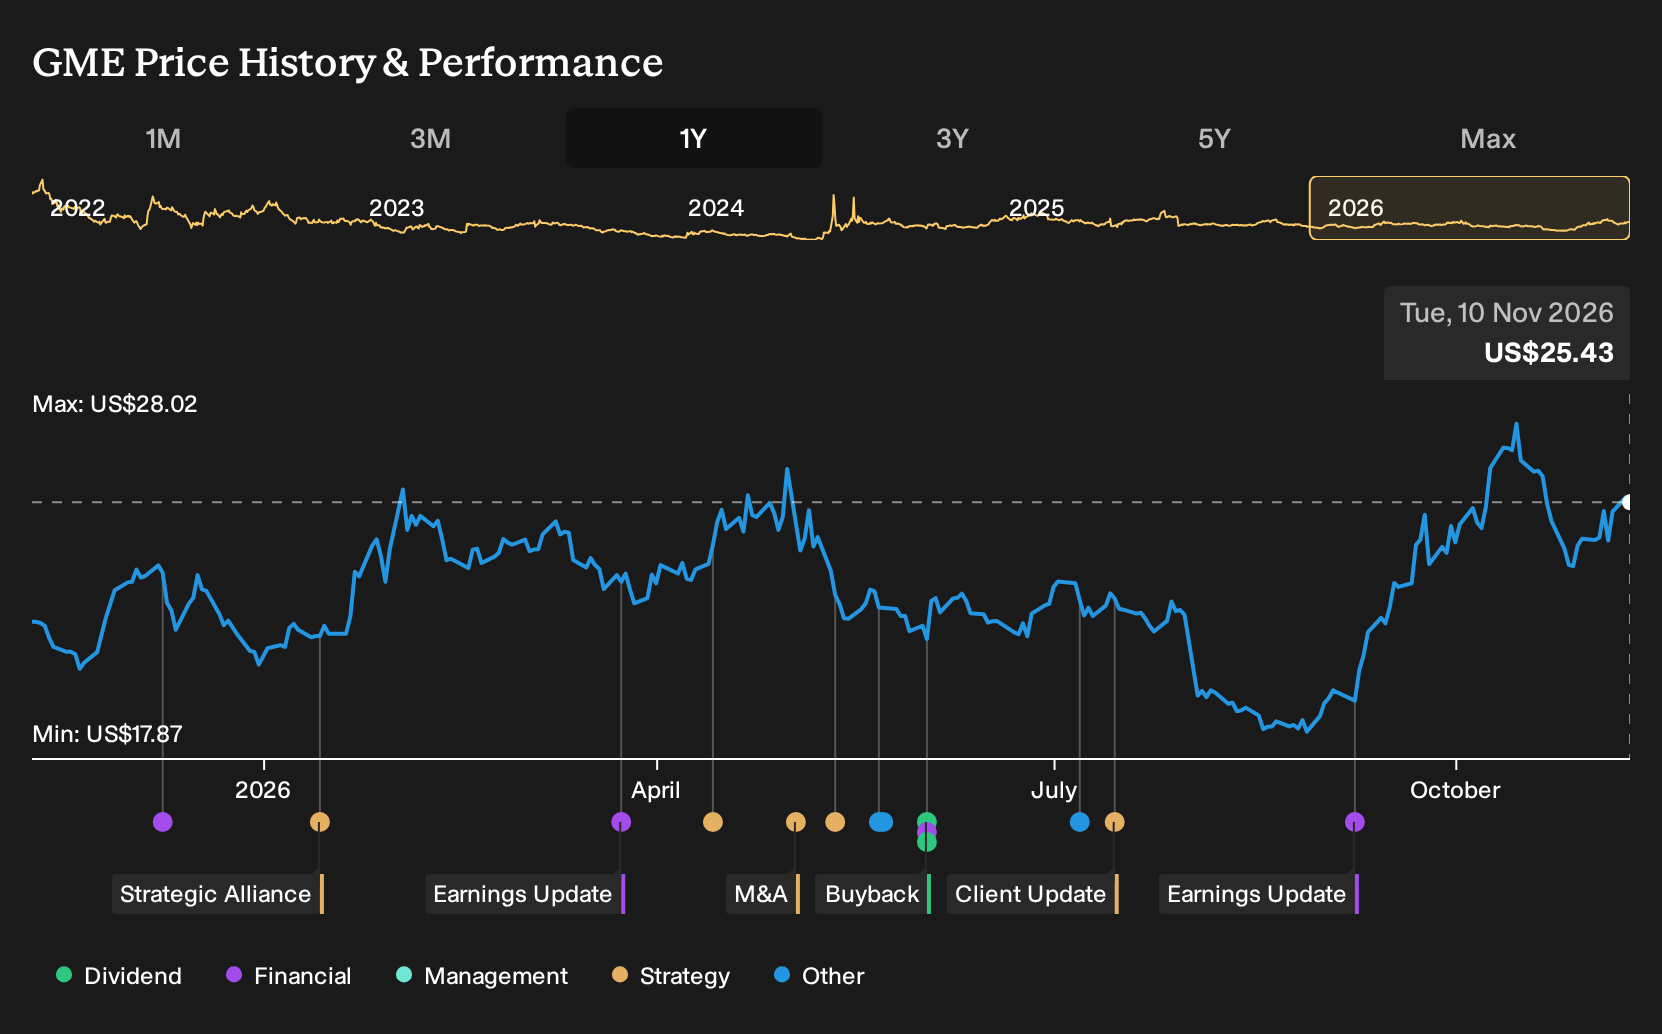
- GameStop is on track for its strongest annual share performance since 2024, after a Wall Street firm outlined fresh growth potential for the retailer’s underlying business.
- The more interesting shift is a renewed focus on GameStop’s operating model, with attention turning to whether execution can support a larger and more complex role in commerce.
- The next area of focus will be how this renewed growth narrative around GameStop, anchored in operating potential, could reshape its investment case.
Scan other retailers with similar momentum and compare how GameStop stacks up against 20 high quality undiscovered gems in terms of quality, balance sheets, and growth runways.
GameStop Investment Narrative Recap
Owning GameStop means believing the retailer can turn its large physical footprint and e commerce presence into a consistently profitable entertainment and collectibles platform. The recent share strength and the Wall Street growth call both point back to the same near term catalyst. Investors are watching whether management can keep earnings quality high while traffic and engagement shift between stores and online.
The biggest near term risk is execution. According to Simple_Jack, an investor in the Simply Wall St Community, the real test is whether GameStop can handle a much bigger and more complex commerce role without slipping on costs or operational focus. The latest news does not change that. It simply raises the bar on what “good enough” execution looks like.
The GameStop offer for eBay that Simple_Jack, a Simply Wall St Community investor who wrote the Narrative, analyzed so closely is the announcement that now sits in the background of this rally. It is directly linked to the current debate about how ambitious management wants to be. That proposed mix of cash and stock framed GameStop as an acquirer rather than a turnaround story stuck in neutral.
That bid brings fresh catalysts and fresh execution risks. Scale could deepen GameStop’s role in digital commerce and collectibles. At the same time, investors need to weigh financing complexity, integration demands and the risk that a very large deal distracts from the core US$3.6b revenue base. The share price reaction and the recent broker optimism sit on top of those unresolved questions, not in place of them.
Simple_Jack’s narrative reaches its US$63.00 fair value for GameStop by applying 32.5% yearly revenue growth and a future profit margin of 11.5%, which together point to a larger earnings base that, in the narrative, supports a higher valuation multiple on the business over time.
Discover why GameStop's fair value points to a 148% potential upside from its current price, which could narrow quickly.
Exploring Other Perspectives
You are seeing five fair value views from the Simply Wall St Community, ranging from about US$27 to US$220. This signals a very wide spread of opinion on GameStop. Those estimates predate the recent growth call, so treat them as a baseline and explore several alternative viewpoints before forming your own stance.
Explore 4 other GameStop fair value estimates, including one that suggests it could be worth just $27.26.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your GameStop research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for GameStop. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate GameStop's overall financial health at a glance.
Looking for more GameStop style investment ideas?
If the GameStop story has sharpened your thinking, use that momentum to scan a broader watchlist and pressure test your thesis against other companies with different strengths and risk profiles.
- If you want potential mispricing on your radar, start with a curated set of 37 high quality undervalued stocks that combine quality fundamentals with compressed expectations.
- If capital preservation sits high on your list, filter for 30 resilient stocks with low risk scores that score well on resilience and balance sheet strength.
- If you are hunting for stronger finances behind the story, run a search across a list of solid balance sheet and fundamentals (24 results) and see which tickers deserve a closer look next.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com