


EN
Caledonia Investments (LSE:CLDN) Could Be 78% Overvalued As Half Year Profit Jumps
Caledonia Investments (LSE:CLDN) just posted half year results to 30 September 2026, with revenue of £159.6 million and net income of £143.4 million, framing the latest move in the share price.
The latest earnings release appears to have reset sentiment around Caledonia Investments, with the 1-day share price return of 4.44% and 7-day gain of 4.71% lifting the stock to £4.0. Meanwhile, the 1-year total shareholder return of 6.03% and 5-year total shareholder return of 23.46% point to steadier long-run compounding and suggest that momentum is currently building rather than fading.
Scan how Caledonia Investments stacks up against a hand picked group of resilient businesses with strong balance sheets in the list of solid balance sheet and fundamentals (9 results).
Caledonia Investments now looks like a solid compounder with fresh earnings momentum baked into the share price. The real test is whether £4.0 already reflects that strength or still leaves room on the table.
Price-to-Earnings of 15.1x: Is it justified?
Valuation for Caledonia Investments hinges on a P/E of 15.1x, which sits against a £4.0 share price and leaves the stock trading richer than several benchmarks.
The P/E ratio compares what investors pay for each £1 of earnings. For an investment trust like Caledonia Investments, that figure often reflects how the market rates the durability and quality of its underlying portfolio profits rather than just a single reporting period.
Here, the 15.1x multiple is below the wider UK market average of 16.2x, so the shares are not priced at a broad market premium. At the same time, the same P/E is above both the UK Capital Markets industry average of 11.5x and the peer group average of 13.1x. This points to investors paying a higher tag than many closer comparables.
This mix suggests the market is attaching a stronger price to Caledonia Investments earnings than similar capital markets stocks, even though the ratio is not stretched against the overall UK market. Whether that premium feels comfortable or not comes back to how you view its earnings profile. This includes a recent 104.5% profit uplift against a backdrop of a 38.2% per year decline over five years and a current net margin of 82.5% compared with 68.4% last year.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 15.1x (OVERVALUED)
Still, concentration in private capital and heavy exposure to the United States mean any earnings setback or portfolio markdown could quickly challenge Caledonia Investments’ current P/E premium.
Find out about the key risks to this Caledonia Investments narrative.
Another view on Caledonia Investments valuation
The P/E discussion presents Caledonia Investments as expensive against capital markets peers, and our DCF model suggests an even higher valuation. On that measure, the shares at £4 trade above an estimated future cash flow value of £0.87, which points to a clear overvaluation signal.
The gap between £4 and £0.87 is wide in practical terms. It suggests you are paying materially more than our DCF estimate of what the portfolio’s cash generation is worth, so the margin for error leans toward valuation risk rather than a bargain. The key question is which yardstick you place more weight on for a long term holding.
Look into how the SWS DCF model arrives at its fair value.
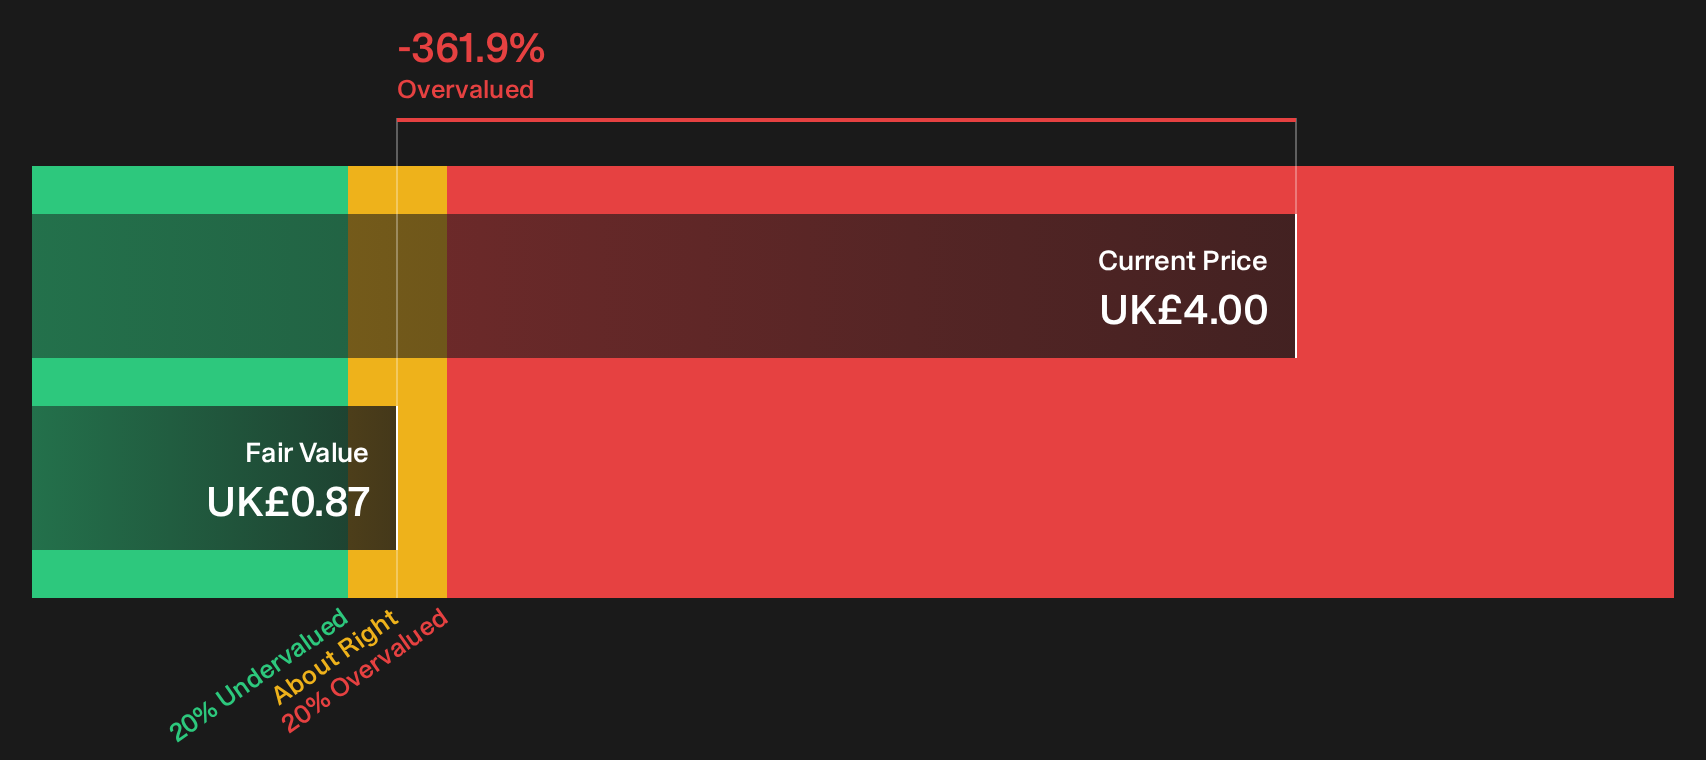
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Caledonia Investments for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 16 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment looks mixed, with rich valuation signals and strong profitability data pulling in different directions for Caledonia Investments. Act before the story moves too far without you and weigh both sides of the argument with the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Caledonia Investments?
If Caledonia Investments has sharpened your focus on valuation and quality, the next smart step is lining up a few more candidates that fit your style.
- Target potential upside by reviewing companies that combine quality fundamentals with attractive pricing through the 16 high quality undervalued stocks.
- Strengthen your income stream by scanning for higher yielding payers with robust profiles using the 6 dividend fortresses.
- Dial down portfolio stress by focusing on resilient businesses screened for stability and financial strength via the 4 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com