


EN
Downer EDI (ASX:DOW) Outlook Turns Negative, Is The Stock Still Undervalued?
Fitch Ratings has affirmed Downer EDI (ASX:DOW) at a BBB issuer rating but shifted the outlook to negative. This move refocuses attention on the group’s risk profile and financing flexibility.
At around A$7.30, Downer EDI’s 1 day share price return of 5.19% and 30 day share price return of 6.10% contrast with a year to date share price decline of 8.52%. The 3 year total shareholder return of 102.99% points to a much stronger longer run outcome despite near term swings in risk perception following the recent Homes Victoria contract win and the Fitch outlook revision.
Scan how other infrastructure and services stocks are priced against their risks using a curated set of 6 resilient stocks with low risk scores alongside Downer EDI's latest rating shift.
So after a 5.19% one day jump and a fresh negative outlook from Fitch, does Downer EDI still offer enough potential to justify the extra credit risk on the table as you weigh the valuation next?
Most Popular Narrative: 6% Undervalued
On the analyst consensus Narrative on Simply Wall St, Downer EDI screens as modestly undervalued, with a fair value of A$7.78 against the last close of A$7.30. That gap is small enough that the quality and length of contracts become the real swing factors.
Downer EDI''s ongoing focus on disciplined contract selection and a portfolio that is now largely services based, with a higher share of government related work in hand, leaves room for further uplift in EBITA margins and earnings quality as more of this pipeline converts into revenue.
See why 13 investors see Downer EDI as 6% undervalued.
Result: Fair Value of A$7.78 (UNDERVALUED)
Still, any stalling in the transformation program, or a sharper pullback in Australian telco work, could quickly challenge the current Downer EDI valuation story.
Find out about the key risks to this Downer EDI narrative.
Another View: How Multiples Frame Downer EDI
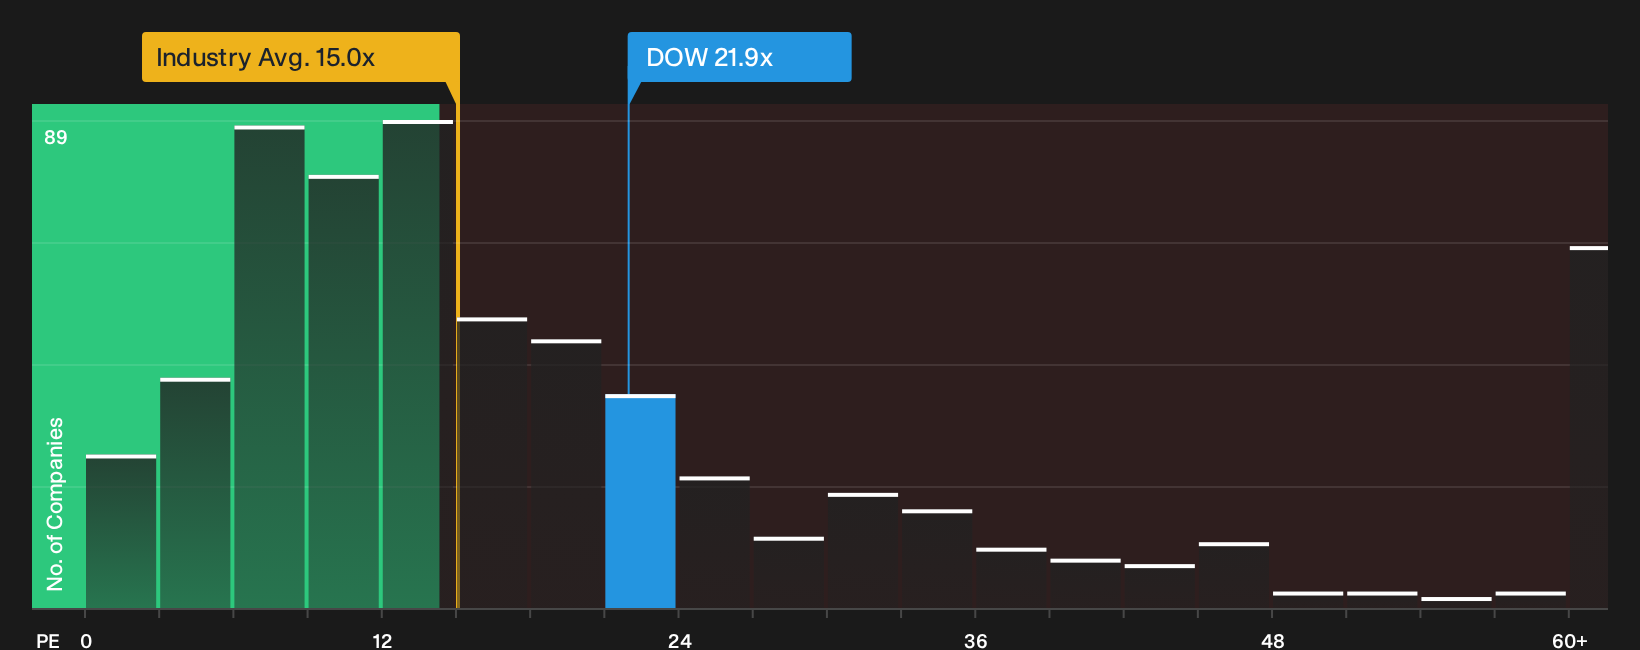
There is a different read on valuation when you look at Downer EDI through its P/E. The stock trades on 21.9x earnings compared with 15x for the global Commercial Services group and 20.4x for peers, while the fair ratio sits higher again at 26.1x. That mix points to a company priced above the sector but below where the fair ratio suggests the market could move. This raises a simple question: is this a premium that earns its keep or a margin of safety slowly being used up?
To see how the current pricing stacks up against peers and that fair ratio in more detail, take a look at the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Downer EDI is clearly mixed, with credit questions on one side and valuation support on the other. Move quickly, test the data against your own expectations, then weigh both sides through 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Downer EDI?
Do not stop at Downer EDI. Broaden your watchlist now with targeted ideas that match your risk comfort and income goals before others get there first.
- Hunt for potential mispricings by scanning a focused list of quality companies that may trade below their estimated value through the 2 high quality undervalued stocks.
- Explore income-led opportunities by reviewing businesses screened for strong yields and durability using the 5 dividend fortresses.
- Prioritise resilience by using a curated list of solid balance sheet and fundamentals (12 results) that can help you stress test your portfolio against tougher conditions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com