


EN
Descartes Systems Group (TSX:DSG) Is Back In The Spotlight, What Is Driving It?
Descartes Systems Group (TSX:DSG) recently expanded its logistics footprint by linking MacroPoint Advanced Ocean Visibility with SAP Business Network tools. This integration gives SAP users broader shipment tracking and a more unified multimodal view within their existing workflows.
Investors have reacted positively to these product moves from Descartes Systems Group, with a 30 day share price return of 14.2% helping lift the stock to CA$134.92. A 1 year total shareholder return of 15.91% suggests that momentum has been building rather than fading.
Capitalize on Descartes Systems Group's logistics momentum by scanning a hand picked set of supply chain and software players in the 7 high quality undiscovered gems.Descartes Systems Group now trades at a discount to one intrinsic value estimate even after the SAP driven rally. The real tension is whether that gap reflects opportunity or justified caution.
Preferred P/E of 43.2x: Is it justified?
Valuation on earnings is not cheap here. Descartes Systems Group trades on a P/E of 43.2x, while sitting 18.8% below an internal cash flow based estimate of fair value at CA$166.16, against a last close of CA$134.92.
The P/E ratio links what you pay today to the profits that Descartes Systems Group currently generates. For a subscription heavy software provider with CA$775.17m in revenue and CA$188.01m in net income, this metric gives a quick sense of how much the market is willing to pay for each dollar of earnings.
DSG is flagged as good value versus its immediate peer set at a P/E of 43.2x compared with a 44.9x peer average. Against the broader North American software group though, the stock is described as expensive, with that same 43.2x multiple sitting well above the 32.7x industry level. A fair P/E closer to 28x is implied by the estimated fair ratio. This is a level the market could move towards if sentiment cools on the growth story.
Explore the SWS fair ratio for Descartes Systems Group.
Result: Price-to-Earnings of 43.2x (OVERVALUED)
Still, any wobble in SAP execution or a slowdown in logistics software spending could quickly challenge the premium multiple that investors are currently paying for Descartes Systems Group.
Find out about the key risks to this Descartes Systems Group narrative.
Another View: SWS DCF Says Undervalued
The P/E math paints Descartes Systems Group as expensive, yet the SWS DCF model points the other way. On that cash flow based view, CA$134.92 sits about 18.8% below an intrinsic value estimate of CA$166.16. This frames today’s price as a potential discount rather than a premium. Which lens do you trust more when those signals disagree?
Look into how the SWS DCF model arrives at its fair value.
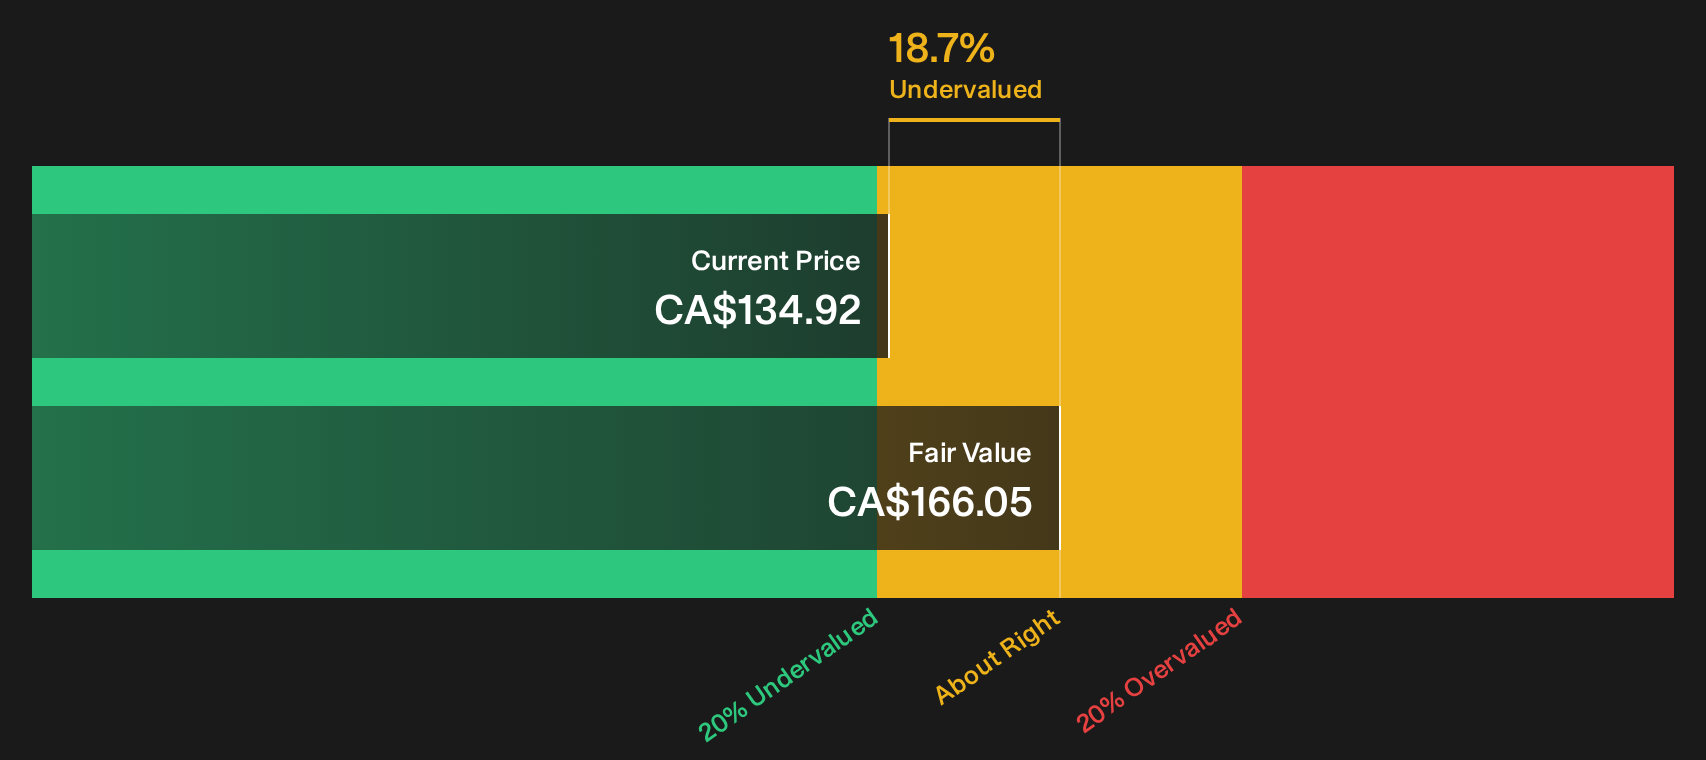
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Descartes Systems Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 5 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Descartes Systems Group so far and not much time if you want to ground your view in the underlying data. Weigh both the potential upside and the flagged downsides, then stress test your own expectations against the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Descartes Systems Group?
If you stop at Descartes Systems Group, you risk missing other setups that could fit your plan even better, so widen your search with focused screeners.
- Target stability first by checking a 9 resilient stocks with low risk scores that prioritises resilient balance sheets and steadier return profiles over headline grabbing swings.
- Hunt for value opportunities using a 5 high quality undervalued stocks where solid fundamentals and pricing gaps sit side by side for you to assess.
- Zero in on dependable cash generators with a 3 dividend fortresses geared to businesses offering higher yields backed by practical financial strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com