


EN
What OPmobility Bears Spotted Before The Slide
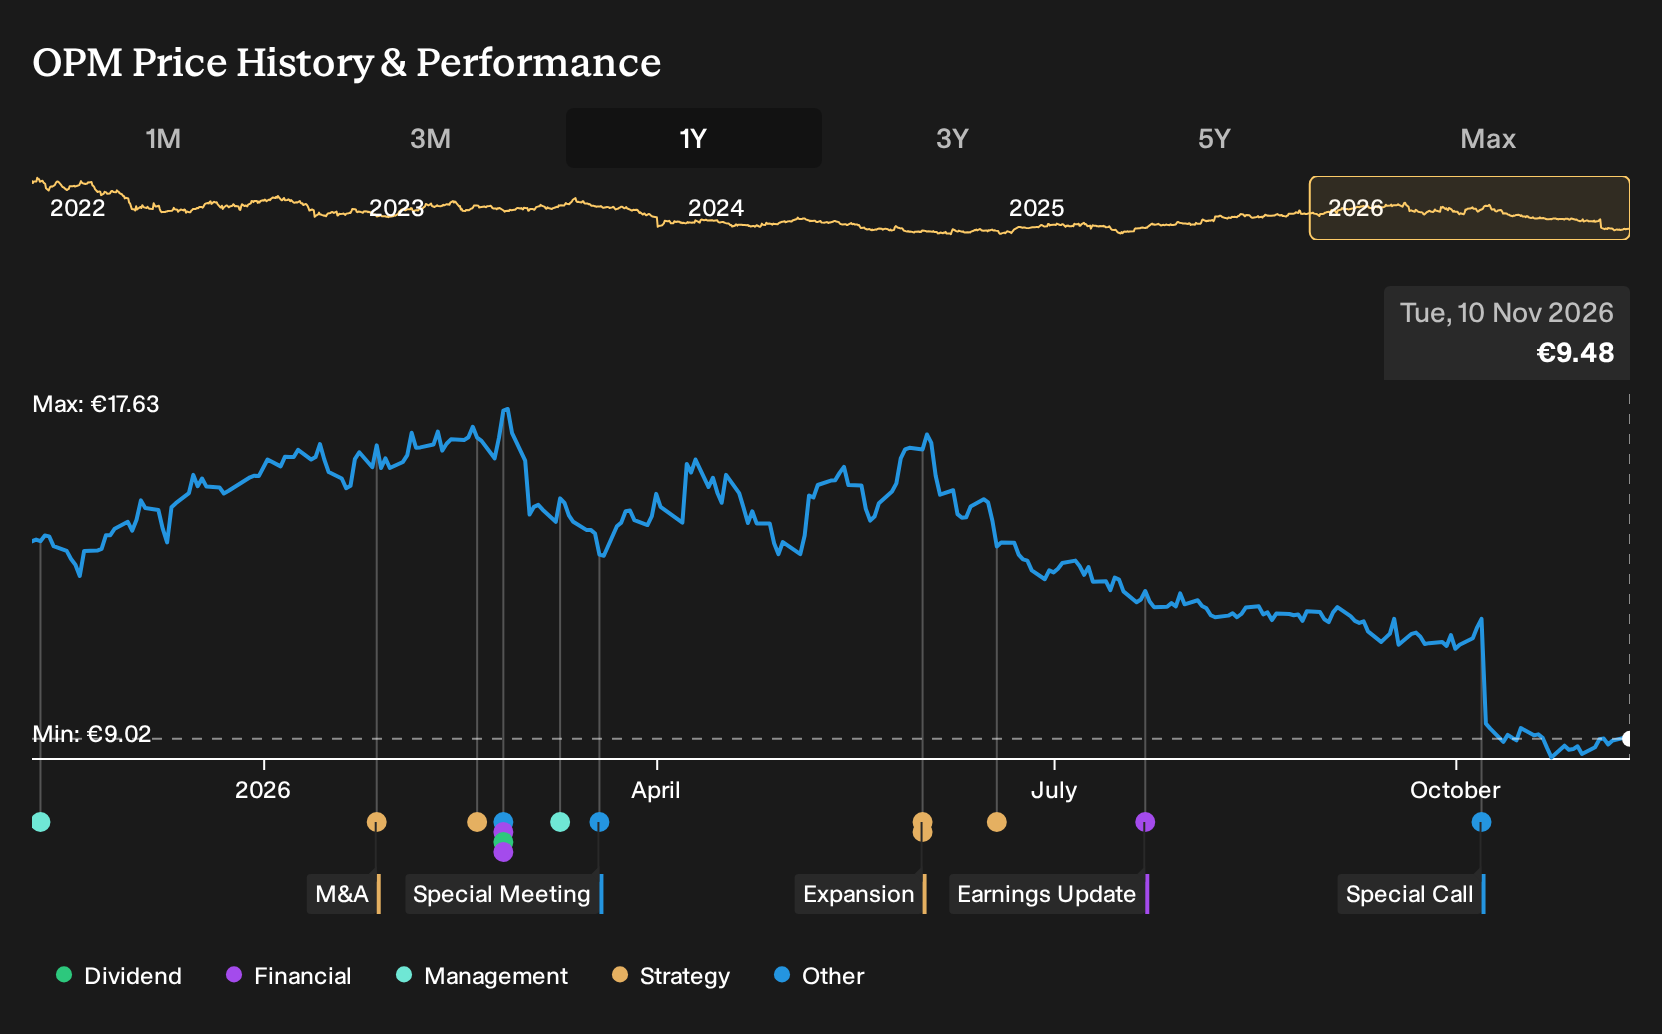
If you bought into OPmobility on the promise of expanding EV content and higher margins from integrated exterior and lighting systems, the past year has been bruising. Investors who held OPmobility over the past year are down 31.8%, including dividends. If you made that decision on 10 November 2025, what, exactly, did the original bullish and cautious analyst cases miss about execution, customer mix, or capital needs rather than the whole story being wrong?
The easy part of this move is behind OPmobility. Zero in on 198 high quality undervalued stocks for companies trading below our estimates.
The Two OPmobility Stories Investors Were Weighing
The shares cost €14.4 at the start of the period, and anyone looking at OPmobility then had to choose between two very different but reasonable stories about what came next.
On the optimistic side, the bullish argument pointed to a Fair Value of €16.3, a price implied by assumptions of 2.9% annual revenue growth and profit margins reaching 3.5% as integrated exterior and lighting contracts scaled up.
The more cautious narrative put Fair Value at €12.08, based on 1.8% expected annual revenue growth and concern that EV simplification, China exposure, and future R&D and compliance spending might cap margins near 2.7%.
What The Results Changed For The OPmobility Thesis
The most concrete development was OPmobility securing major hybrid battery pack contracts and reporting H1 2026 net income of €102 million on €5,202 million of revenue, with net margin at 2.0%. That supported the cautious case on capital intensity and mix, because revenue slipped from €5,332 million even as profitability ratios improved. Overall, the evidence cut both ways.
The lesson is simple. When a story leans on higher content per vehicle, keep checking contract wins against total revenue and net margin to see if new programs offset pressure on the rest of the portfolio.
What You Are Really Paying For With OPmobility Today
OPmobility now trades at €9.47 after a 31.8% loss over the past year. The analyst consensus Narrative on Simply Wall St describes Fair Value as being above that level.
The Narrative argues that the key question is whether capacity shifts, the Hyundai Mobis lighting deal and restructuring can offset China weakness and cost pressure. A buyer today would need to believe that execution on those moves keeps margins, cash flow and leverage broadly on track.
"The main thing that has to go right is OPmobility executing its restructuring and capacity shift toward higher growth regions while keeping margins, cash flow and balance sheet metrics broadly intact. The current valuation implies OPmobility is priced as if China headwinds, profit warnings and analyst downgrades will weigh heavily on earnings, even though the business continues to outperform auto production and generate free cash flow while investing for growth."
The price and this Narrative do not agree. → Uncover what this Narrative says OPmobility is actually worth
Looking One Step Beyond OPmobility
OPmobility is all about supplying more content per vehicle. You are really betting on carmakers wanting richer, more complex hardware.
Step sideways and you find another player chasing a different chokepoint. Instead of body parts, it focuses on brains and batteries inside the car.
This business builds the software heavy systems that run driver assistance and energy management. It treats high end driving intelligence as standard kit, not an optional subscription.
That shift turns code and sensors into a retention tool rather than a one off sale. If more automakers copy that model, the value map across the EV chain could look very different.
That argument has a Narrative and a number behind it. → See the company one Narrative values 112% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com