


EN
YETI Holdings (YETI) Earnings Outlook Improves, Is The Stock Still Undervalued?
Recent analyst projections for YETI Holdings (YETI) have put the upcoming quarterly earnings report in focus, with forecasts indicating higher profit per share and stronger performance across direct to consumer, wholesale, and international channels.
YETI Holdings has seen momentum pick up into this earnings window, with a 1-month share price return of 15.18% and a 1-day move of 1.91% lifting the stock to US$45.83. This comes even though the 90-day share price return is down 9.77% and the 5-year total shareholder return is down 55.11%, while the 1-year total shareholder return of 25.53% and 3-year total shareholder return of 12.25% point to improving sentiment around the story.
Scan beyond YETI Holdings and explore other consumer stocks showing similar earnings momentum using the hand picked 19 high quality undiscovered gems embedded in this report.
YETI Holdings has recently made a sharp near-term climb, which leaves you weighing a quick entry against waiting for a potentially cheaper price. So how far does the current price sit from fair value?
Most Popular Narrative: 16.6% Undervalued
On the analyst consensus Narrative on Simply Wall St, YETI Holdings screens as undervalued, with a fair value of $54.93 versus the latest close at $45.83. That view leans heavily on a detailed roadmap for revenue mix, margins, and free cash flow.
The plan to generate US$1.2b to US$1.4b of cumulative free cash flow through 2030, combined with a track record of meaningful share repurchases and a commitment to return at least 50% of free cash flow, provides scope for lower share count and higher earnings per share even if revenue growth remains in the guided range.
See why 13 investors see YETI Holdings as 17% undervalued.
Result: Fair Value of $54.93 (UNDERVALUED)
Still, the YETI Holdings story can break if input costs stay stubbornly high or if revenue and earnings drift below the analyst path that underpins this valuation.
Find out about the key risks to this YETI Holdings narrative.
Another View: What YETI’s P/E Is Telling You
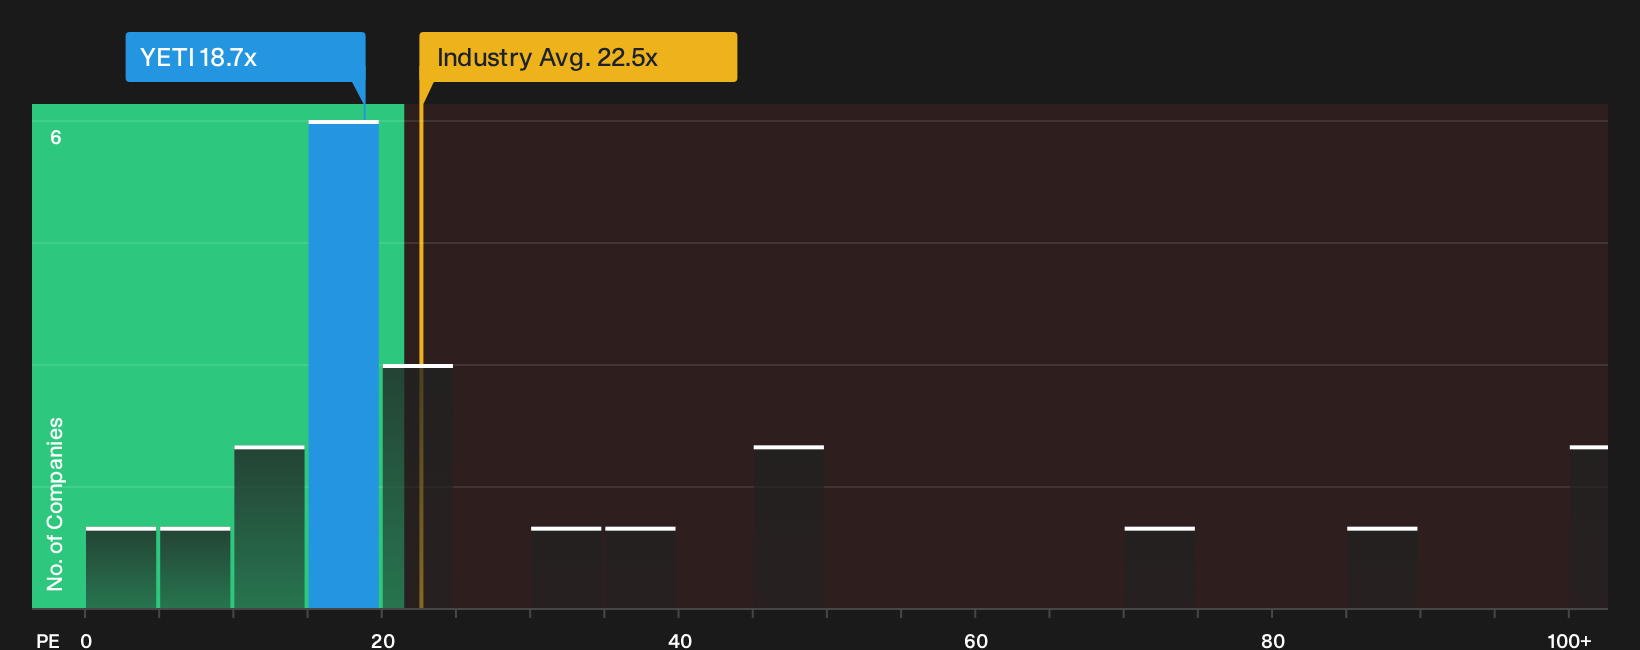
That fair value story leans heavily on cash flows. On simple earnings multiples, YETI Holdings looks less generous. The stock trades on a P/E of 18.7x, which is slightly above the peer average of 18.3x and above a fair ratio of 16.5x, even though it is below the North American Leisure group on 21.6x. In plain terms, you are not getting an obvious bargain on current earnings, so the question is how much weight to put on long range cash flow estimates.
For a closer look at how this earnings based view stacks up, including where valuation could shift if sentiment changes, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling torn between the bullish fair value case and the richer P/E story around YETI Holdings? Move quickly to review the numbers yourself, then weigh those potential upsides through 2 key rewards
Looking for more investment ideas beyond YETI Holdings?
Do not stop with a single stock. Use the broader toolkit of ideas to pressure test your thesis on YETI Holdings and refresh your wider watchlist.
- Target potential mispricings by scanning through 33 high quality undervalued stocks that pair solid fundamentals with prices that lag behind their underlying strength.
- Build a steadier income stream by focusing on 6 dividend fortresses that aim to combine higher yields with more resilient payout profiles.
- Protect the downside of your portfolio by filtering for 30 resilient stocks with low risk scores that score well on balance sheet quality and risk metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com