


EN
How Revenue Growth And EPS Decline Will Impact Weyerhaeuser Stock (WY)
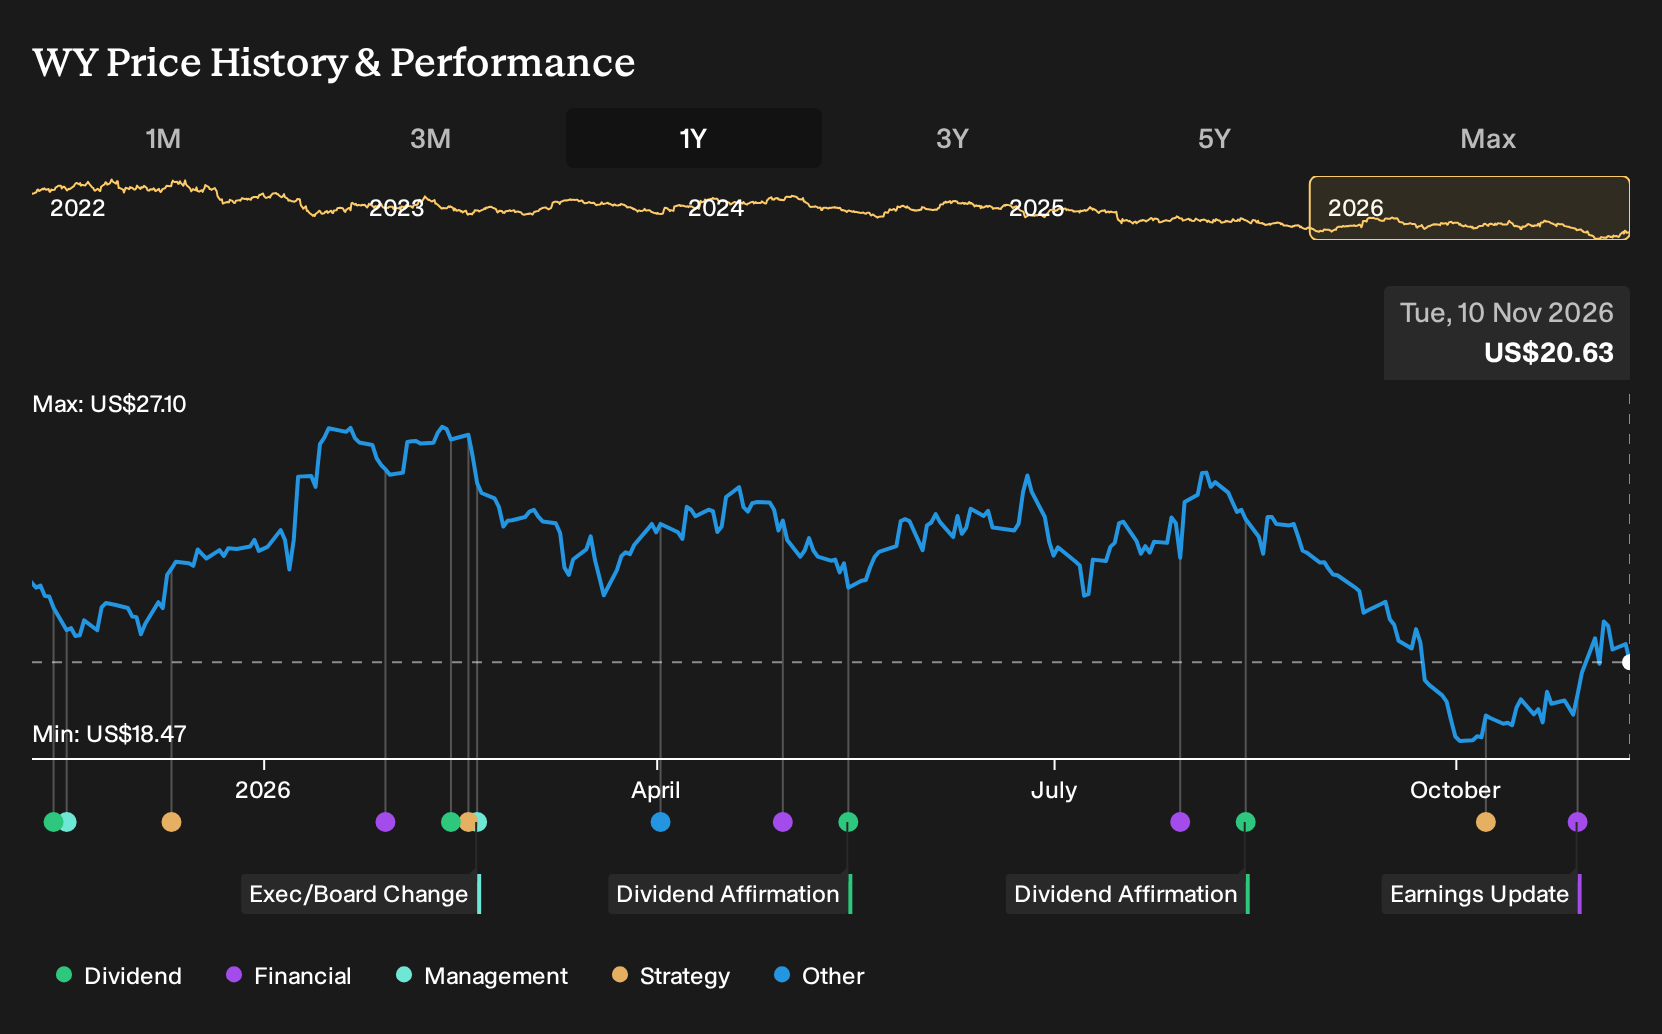
- Weyerhaeuser reported third quarter 2026 net income of US$61 million, down from US$80 million a year earlier, with diluted EPS from continuing operations at US$0.08 compared with US$0.11, while nine month net income reached US$379 million versus US$250 million in the prior year period.
- The mix of higher nine month earnings, an 8.4% quarterly revenue increase and a 27.3% drop in EPS, alongside net debt at roughly 7x EBITDA, highlights how funding growth projects and servicing leverage may be weighing on per share profitability.
- This article examines how Weyerhaeuser's investment narrative is affected by the EPS decline alongside revenue growth in the latest quarter.
Compare Weyerhaeuser's mix of rising revenue, softer EPS and higher leverage with other balance sheet focused stocks by scanning our hand picked list of solid balance sheet and fundamentals (25 results).
Weyerhaeuser Investment Narrative Recap
To own Weyerhaeuser, you have to believe the mix of timber, wood products and newer Climate Solutions projects can support earnings through a choppy housing backdrop and a still weak oriented strand board segment. The latest quarter did not really change that bigger picture. Revenue rose while EPS softened, so the story remains about execution rather than a new inflection point.
The short term swing factor still sits in wood demand and pricing, while the biggest current risk is leverage, with net debt around 7x EBITDA and interest not well covered by earnings. Softer quarterly EPS simply underlines that a highly geared balance sheet leaves less room for error if housing or OSB conditions worsen.
The analyst consensus Narrative on Simply Wall St leans heavily on Weyerhaeuser scaling higher value projects such as the Monticello TimberStrand mill and Climate Solutions pipeline. The recent earnings release, with nine month net income of US$379 million and EPS of US$0.53, gives you a snapshot of how much internal cash the business is generating to support that plan in real time.
Quarterly EPS of US$0.08, down from US$0.11, brings the focus back to execution risk around that capex heavy roadmap and a dividend that is described as not well covered by earnings or free cash flow. For a shareholder, the question is whether current profitability and cash generation can comfortably fund Monticello, climate projects and interest costs without forcing harder trade offs elsewhere.
Analysts expect Weyerhaeuser to generate about US$8.4b of revenue and US$558.6 million of earnings by 2029. This assumes revenue increases of 6.3% a year and an earnings rise of roughly US$105.6 million from the US$453.0 million reported today.
Uncover how Weyerhaeuser's fair value indicates a 29% potential upside to its current price before enthusiasm for the discount fades.
Exploring Other Perspectives
One alternate angle puts housing demand front and center. Before this EPS miss, the most cautious analysts were assuming Weyerhaeuser could still reach about US$8.0b of revenue and US$705.7 million of earnings by 2029. That is a more optimistic earnings path than the consensus, which shows how widely opinions can differ. You can use this quarter’s softer EPS to test which narrative you find more convincing and explore how those pre news forecasts might now shift.
Explore 3 other Weyerhaeuser fair value estimates, including one that suggests it could be worth just $26.64!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Weyerhaeuser research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Weyerhaeuser. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Weyerhaeuser's overall financial health at a glance.
Looking For More Weyerhaeuser Style Investment Ideas?
If the Weyerhaeuser story has you thinking about balance sheets, income streams and valuation gaps, the next step is to line it up against other companies using the Simply Wall St Screener.
- If you want potential value opportunities with quality fundamentals, scan our hand picked 33 high quality undervalued stocks that might warrant a closer look beside Weyerhaeuser.
- If capital preservation and steadier profiles matter most to you, check out a curated 30 resilient stocks with low risk scores that could complement a position in more cyclical holdings.
- If you enjoy finding early stage opportunities before they become widely followed, review a focused 10 elite penny stocks with strong financials that narrows the field to stronger financial profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com