


EN
Standard Life (LSE:SDLF) Following Its Dividend Push And Aegon UK Deal Looks Fully Valued
Standard Life (LSE:SDLF) has jumped onto many investors’ radars after renewed focus on its dividend income, with planned annual payout increases and strong operating cash flow supporting that income story.
Recent trading has been quietly supportive for Standard Life, with a 30-day share price return of 10.02% and a year-to-date share price gain of 25.64% indicating that momentum has been building rather than fading.
Scan other high-yield opportunities that are moving in tandem with Standard Life's income story by reviewing our hand picked 6 dividend fortresses tailored for dividend focused investors.
After a 25.64% gain so far this year, the question around Standard Life is simple. Is it worth paying up now for that dividend stream, or waiting for a cooler entry point as valuation settles?
Most Popular Narrative: 1% Overvalued
On the analyst consensus Narrative on Simply Wall St, Standard Life screens as slightly overvalued, with a fair value of £9.20 against a last close of £9.34, which leaves very little margin for error around that dividend case.
The integration of Aegon UK, which brings £160bn of additional assets under administration and about £190m of IFRS operating profit on a pro forma basis, is expected to increase Standard Life's capital light fee income and support higher operating margins and earnings. The move toward a higher capital light pensions and savings mix, with the pro forma share of capital light operating profit rising from 47% to 57%, points to a greater contribution from fee based revenue that could improve net margins and reduce reliance on balance sheet intensive products.
See why 93 investors see Standard Life as 1% overvalued.
Result: Fair Value of £9.20 (ABOUT RIGHT)
Still, the narrative around Standard Life could be tested if high retail outflows persist, or if pension risk transfer competition keeps pressuring returns on new deals.
Find out about the key risks to this Standard Life narrative.
Another View on Standard Life’s Valuation
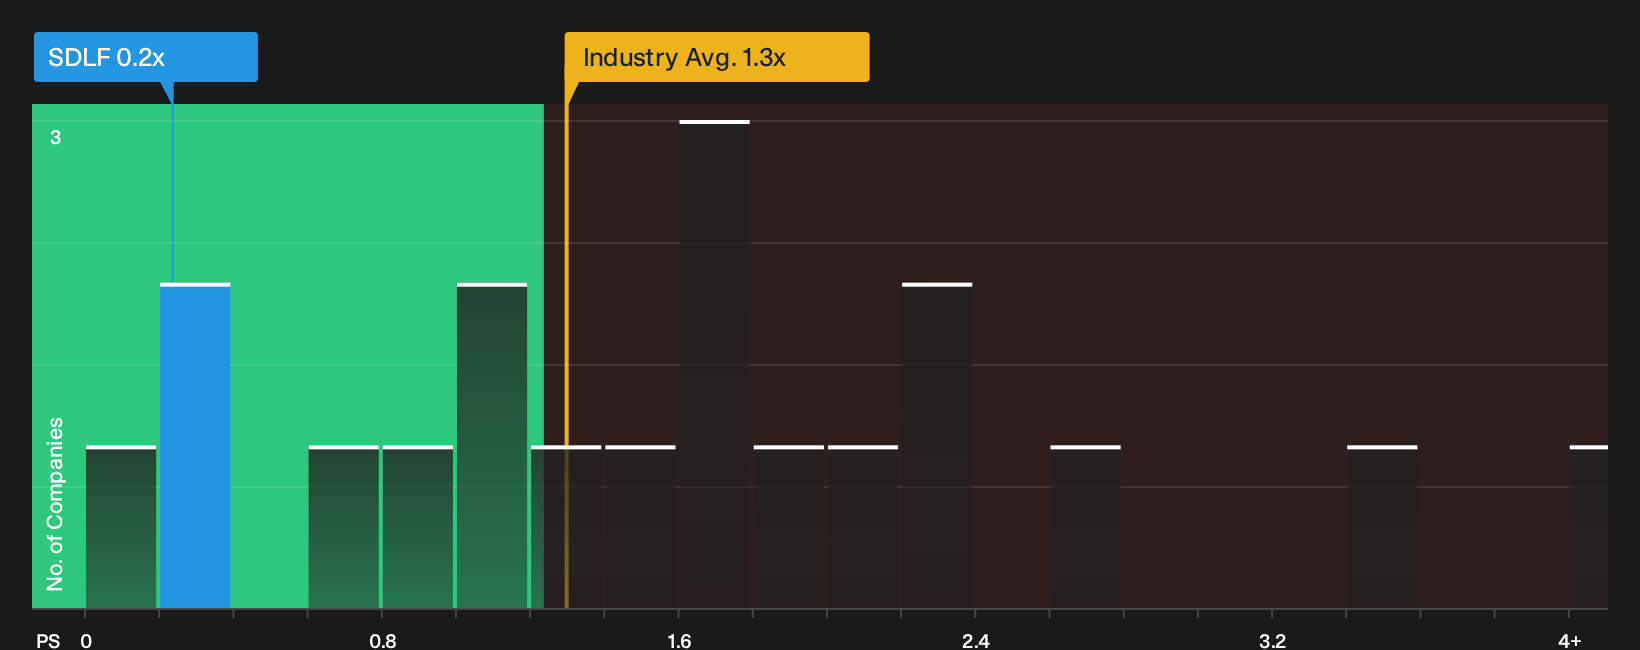
Analysts on Simply Wall St frame Standard Life as roughly fairly priced around £9.20, yet the market is assigning a much lower P/S of 0.2x compared with 1.3x for the European insurance sector and a 0.6x fair ratio. That gap suggests either mispricing or a different risk story. Which side of that argument do you think is closer to reality?
To see how this pricing gap fits into the wider picture for Standard Life, including where that fair ratio could move over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Standard Life's valuation and income case are exactly when it pays to interrogate the details yourself and move with intent rather than drift with consensus. Weigh the upside, weigh the downside and then walk through the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Standard Life?
If Standard Life has sharpened your focus on quality and income, do not stop here. Use the Simply Wall St screener to widen your opportunity set intelligently.
- Target resilient returns by reviewing 4 resilient stocks with low risk scores that aim to keep portfolio swings in check when markets turn choppy.
- Hunt for mispriced quality and scan the 16 high quality undervalued stocks that pair fundamentals with appealing valuations before the crowd catches on.
- Strengthen your core holdings by assessing a list of solid balance sheet and fundamentals (9 results) that can better handle shocks and still support long term compounding.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com