


EN
Nvidia Stock News Has Investors Looking At US Chip Shares Exposed to China
Geopolitics, personal scandal and chip export rules collided after Nvidia CEO Jensen Huang’s admitted affair and renewed scrutiny of China links, turning Nvidia into a flashpoint for Washington and Wall Street. That kind of pressure can punish some stocks while quietly creating openings in others. This piece walks through three U.S. semiconductor companies exposed to the same news cycle so you can judge where risk and potential opportunity may sit next.
The stocks covered next are only a first cut, and the full screen flags 18 more U.S. semiconductor and AI hardware companies with China links and export control sensitivity that could be just as interesting to you. To size up that wider field quickly, head straight into the U.S. Semiconductors with High China Revenue and Export-Control Risk screener to identify, filter and analyze the highest conviction plays.
Analog Devices (ADI)
Analog Devices sits in this screener because its analog and mixed-signal chips feed into AI hardware and China-linked demand, and the analyst consensus Narrative on Simply Wall St argues that the real story is how that exposure ties into a much larger AI infrastructure build-out.
Acceleration of AI data center and energy infrastructure build-outs, with Analog Devices now reporting data center revenue at about a 2b annualized rate and a more than doubled 2030 data center and energy market estimate versus last year, points to further content opportunities that can lift revenue and support earnings growth as this grid to chip build-out converts into higher volume shipments.
What happens to that upside depends heavily on how one unseen pressure shapes pricing power where customers most rely on Analog Devices content.
Analog Devices designs and sells a broad range of integrated circuits, software and subsystems used to convert and process real world analog signals. It earned about US$13.9b from this activity, and with a roughly US$191.2b market cap it is a large player in AI linked semiconductors.
That unseen pressure is exactly where things get interesting, and the full narrative for Analog Devices shows how that pricing squeeze could still accelerate value for long term holders.

Cohu (COHU)
Cohu is the pure play test and inspection specialist in this China export-control screen, wiring its gear into chip production lines that touch AI hardware, mobile devices and autos, with all of its US$569 million in sales coming from semiconductor test and inspection and a roughly US$1.8b market cap.
Cohu matters here because the business sits where AI chips and advanced semiconductors are actually tested, so regulatory headlines can ripple straight into customer spending plans. The analyst consensus Narrative on Simply Wall St frames what that position could mean when demand for high performance computing really bites.
Cohu is capitalizing on the surge in high-performance computing and the complexity of modern semiconductors (AI infrastructure, GPUs, HBM, and display drivers) by rolling out advanced, configurable handler platforms and test solutions. This is positioning the company for potential market share gains and higher equipment sales, directly impacting top-line revenue.
What happens if a single assumption about how quickly those new test platforms are adopted shifts will matter a lot for future returns.
That adoption wildcard is exactly what the full narrative for Cohu unpacks, separating short term order noise from where Cohu’s test footprint could quietly compound value next.

MetaX Integrated Circuits (Shanghai) (SHSE:688802)
MetaX Integrated Circuits (Shanghai) develops GPU chips and computing platforms in China for AI, cloud, and graphics workloads and sits squarely in the U.S. export control conversation around advanced processors. The business is valued at about CN¥203.7b, putting it among the larger listed chip designers in the region.
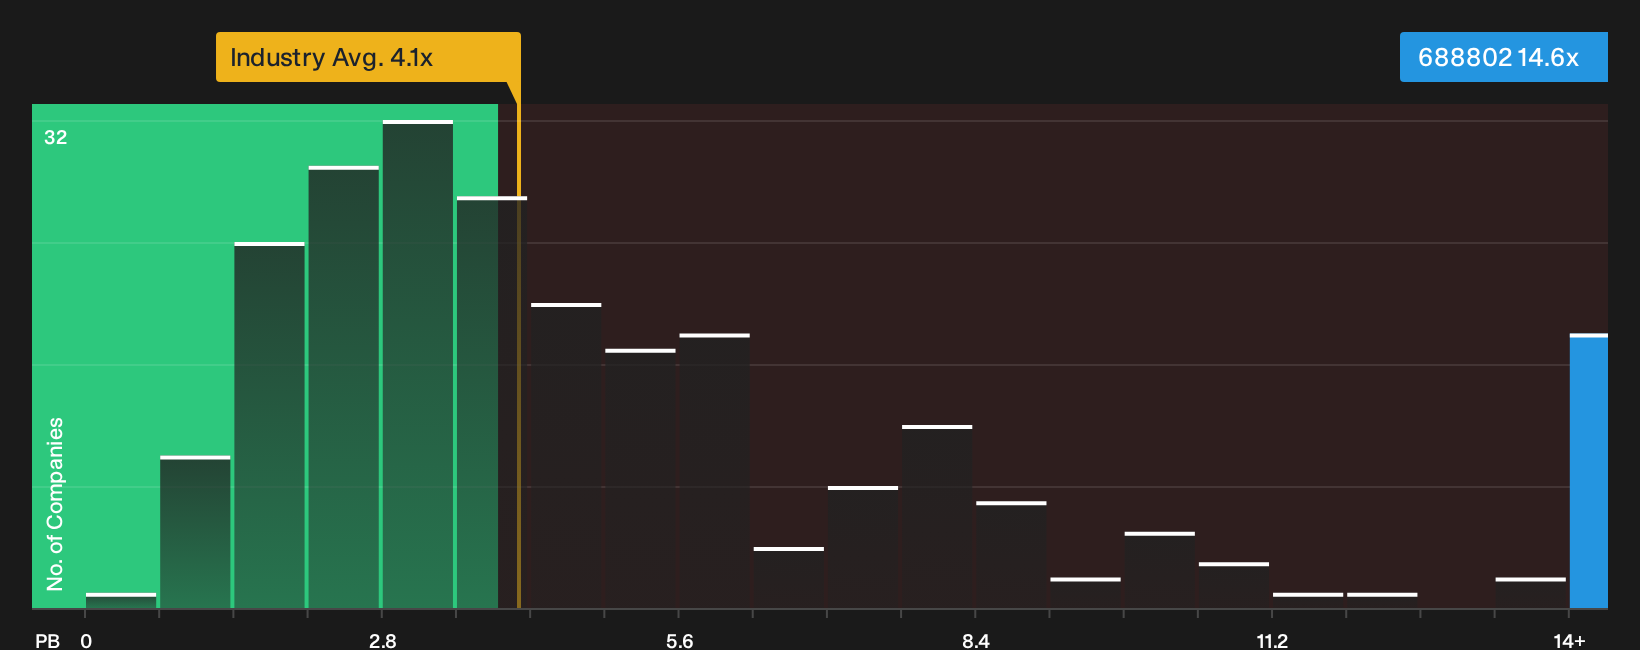
MetaX Integrated Circuits (Shanghai) gives you direct exposure to China’s push for homegrown AI compute at a time when U.S. export rules are tightening around high end GPUs. Rapid revenue and earnings expansion meet a very rich P/B multiple and governance questions, so much depends on how one unresolved pressure on capital allocation plays out.
That capital allocation question is exactly where the 2 key rewards and 2 important warning signs (2 are major!) starts to bite, showing how MetaX Integrated Circuits (Shanghai) risk could be masking underappreciated upside.
Seeking Alternatives Before Momentum Flies
Fresh breakouts rarely stay under the radar for long. Prices move, momentum builds, and the best entries get caught quickly. Scan these ideas while it matters and consider them promptly.
- Spot cash-generating compounds early and use the 33 high quality undervalued stocks to focus on sturdy balance sheets that could support the next leg of market momentum.
- Ride structural infrastructure trends by checking the 42 power grid technology and infrastructure stocks for companies tied to grid upgrades that might benefit if capital rotates into energy resilience.
- Target real earnings engines in AI by running through the 42 profitable AI stocks that aren't just burning cash before the crowd chases buzzier stories without the cash flow to support them.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com