


EN
Ventia Services Group (ASX:VNT) Back In Focus On Special Call As Valuation Debate Builds
Special call and sharp price move put Ventia back in focus
Ventia Services Group (ASX:VNT) moved into the spotlight after a special call on 8 November and a single day share price fall of 16.23% that tracked wider Australian macro concerns.
For context, Ventia Services Group shares have fallen over the past week and month, with the 7 day share price return down 14.11% and the 30 day share price return down 17.79%. The 3 year total shareholder return of 106.08% points to a very strong longer term outcome, suggesting recent momentum has faded even as longer horizon holders have still done well at the current A$4.99 share price.
Scan beyond Ventia Services Group and stress test your macro view against a hand picked 42 power grid technology and infrastructure stocks tied to construction, infrastructure demand and the health of the wider Australian market.
After a 16% one day slide and a longer stretch of weaker returns, Ventia Services Group now forces a timing call. Is this valuation already attractive enough to commit, or does patience still have an edge?
Price-to-Earnings of 15.2x: Is it justified?
Ventia Services Group now trades on a P/E of 15.2x at a last close of A$4.99, which points to a richer tag than the broader Global Construction industry but still below its closer peer group.
The P/E ratio compares the current share price with earnings per share. For an infrastructure services operator like Ventia Services Group, it is a quick way to see how much investors are paying for each dollar of profit in a sector where contracts, balance sheet strength and cash generation matter as much as growth.
On one hand, VNT is described as expensive relative to the Global Construction industry average P/E of 12.7x. This indicates investors are paying a premium versus the wider sector. On the other hand, that same 15.2x is flagged as good value versus a peer average of 22.1x. It also sits below an estimated fair P/E of 19.2x that the market could move towards if sentiment or fundamentals line up.
Explore the SWS fair ratio for Ventia Services Group.
Result: Price-to-Earnings of 15.2x (UNDERVALUED)
Still, your thesis on Ventia Services Group can be knocked off course if Australian infrastructure spending softens or if key contract renewals occur on tougher terms.
Find out about the key risks to this Ventia Services Group narrative.
Another view on Ventia Services Group’s value
The P/E lens presents Ventia Services Group as relatively cheap compared with peers, and the SWS DCF model offers an additional perspective. On that framework, A$4.99 per share sits about 33% below an estimated future cash flow value of A$7.49, which suggests a wider gap for investors to consider.
Look into how the SWS DCF model arrives at its fair value.
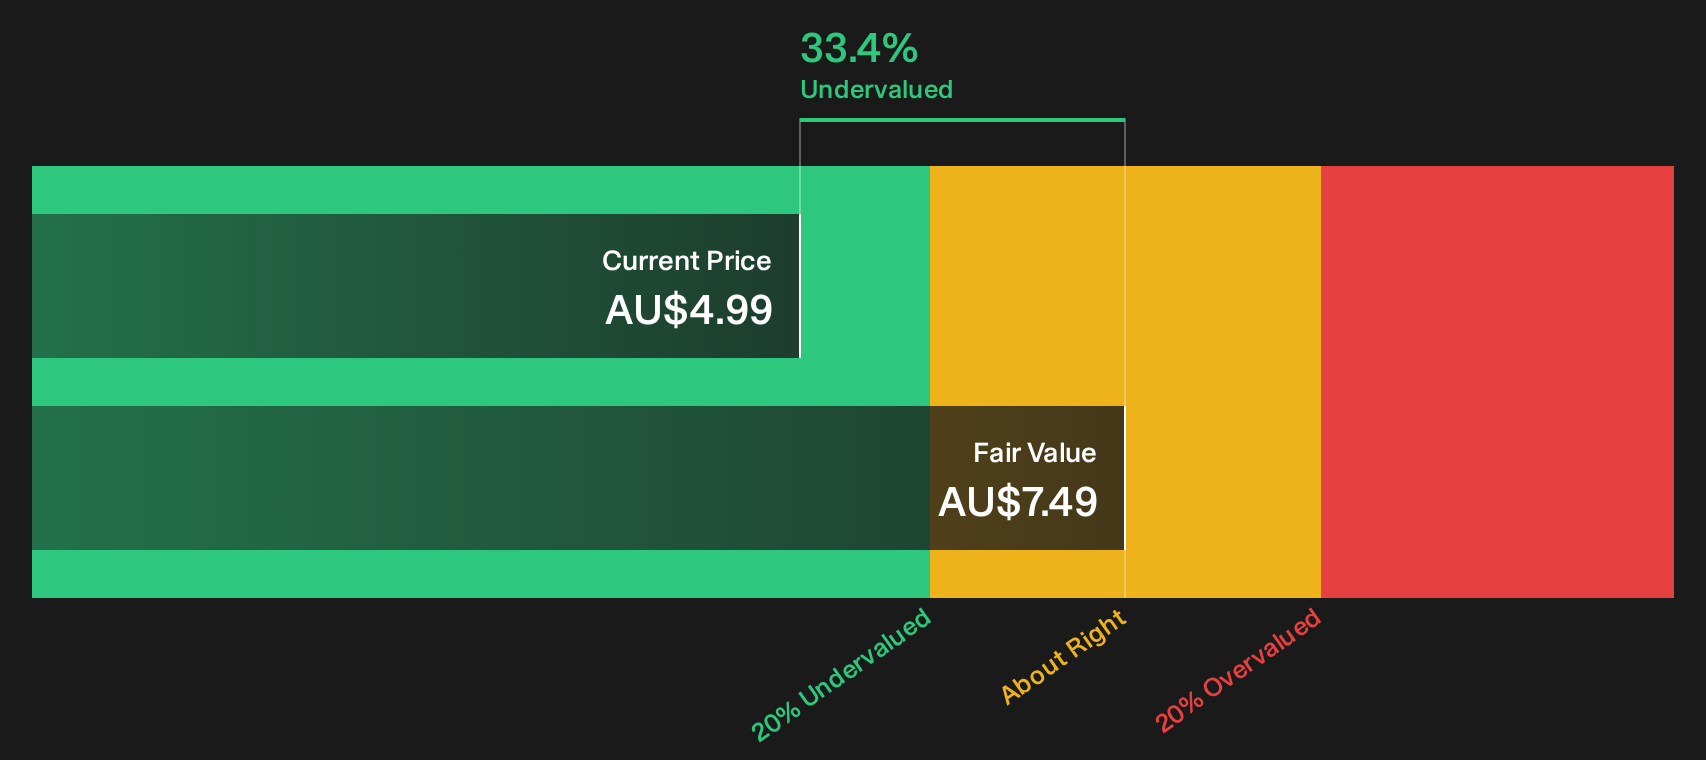
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Ventia Services Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 2 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Unsettled by the mix of sharp moves, valuation signals and shifting sentiment around Ventia Services Group, or see it as a chance worth investigating for yourself? Act quickly, review both the potential downsides and the upside drivers, then weigh the 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond Ventia Services Group?
If Ventia Services Group has your attention after this move, do not stop here. Broaden your watchlist now and give yourself better options.
- Target fresh opportunities by scanning a 14 high quality undiscovered gems that many investors may not be looking at yet.
- Prioritise resilience by reviewing a 6 resilient stocks with low risk scores that focuses on businesses with sturdier risk profiles.
- Strengthen your core holdings by tracking a list of solid balance sheet and fundamentals (12 results) and focus on companies with more robust fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com