


EN
Yancoal Australia (ASX:YAL) Renews Glencore Agreements, Does It Look Fairly Valued?
Yancoal Australia (ASX:YAL) just renewed its long running coal sales and purchase agreements with Glencore, locking in fresh annual transaction caps that outline potential volumes and counterparty exposure through to 2029.
The renewed Glencore arrangements land at a time when Yancoal Australia’s share price has eased in the short term, with a 30 day share price return of 2.92% and a 90 day share price return of 2.25%. However, the year to date share price return of 12.97% and a 5 year total shareholder return of 280.73% point to momentum that has built over a longer horizon as the market continually reassesses both earnings power and contract risk.
Spot fresh ideas by comparing Yancoal Australia's renewed contract visibility with a hand picked list of solid balance sheet and fundamentals (12 results)Yancoal Australia now has fresh visibility on Glencore volumes, yet its share price has cooled in the short term. Does that set up a reasonable entry today, or argue for patience and a cheaper shot later on?
Preferred P/E of 25.4x: Is it justified?
On Simply Wall St's numbers, Yancoal Australia trades on a P/E of 25.4x, which leaves the A$5.66 share price carrying a richer earnings tag than the wider Australian Oil and Gas industry average of 14.6x, even though it is described as good value against both peers and an estimated fair P/E of 33.6x.
The P/E ratio compares the current share price to earnings per share. It therefore shows how many years of current earnings the market is willing to pay for Yancoal Australia. For coal producers and wider energy stocks, investors often watch this metric closely because profits can swing with commodity prices and contract structures, and a higher multiple can signal that the market is comfortable underwriting that volatility.
Here, the picture is mixed. A 25.4x P/E is flagged as expensive against the Australian Oil and Gas sector at 14.6x, which suggests the market is assigning Yancoal Australia a premium relative to the broader group. At the same time, the ratio is labelled attractive versus a peer average P/E of 57.2x and an estimated fair P/E of 33.6x. Both of these reference points indicate potential for the multiple to move closer to that higher level if the business delivers on its earnings profile.
Yancoal Australia is therefore described as good value on Simply Wall St's framework, trading 1.5% below an estimate of its future cash flow value at A$5.75 while the earnings multiple sits between sector and peer benchmarks that tell a more supportive valuation story than the headline premium to the industry alone.
Explore the SWS fair ratio for Yancoal Australia.
Result: Price-to-earnings of 25.4x (ABOUT RIGHT)
Still, any comfort around Yancoal Australia's P/E can be shaken because its earnings are sensitive to coal pricing and its revenue is concentrated in a few key export markets.
Find out about the key risks to this Yancoal Australia narrative.
Another View: What Does The Cash Flow Say?
The P/E story presents Yancoal Australia as reasonably priced and only slightly richer than an industry benchmark. Our DCF model adds a different angle, with the A$5.66 share price sitting just 1.5% below an estimated cash flow value of A$5.75. That is a slim cushion. Is it enough for you?
Look into how the SWS DCF model arrives at its fair value.
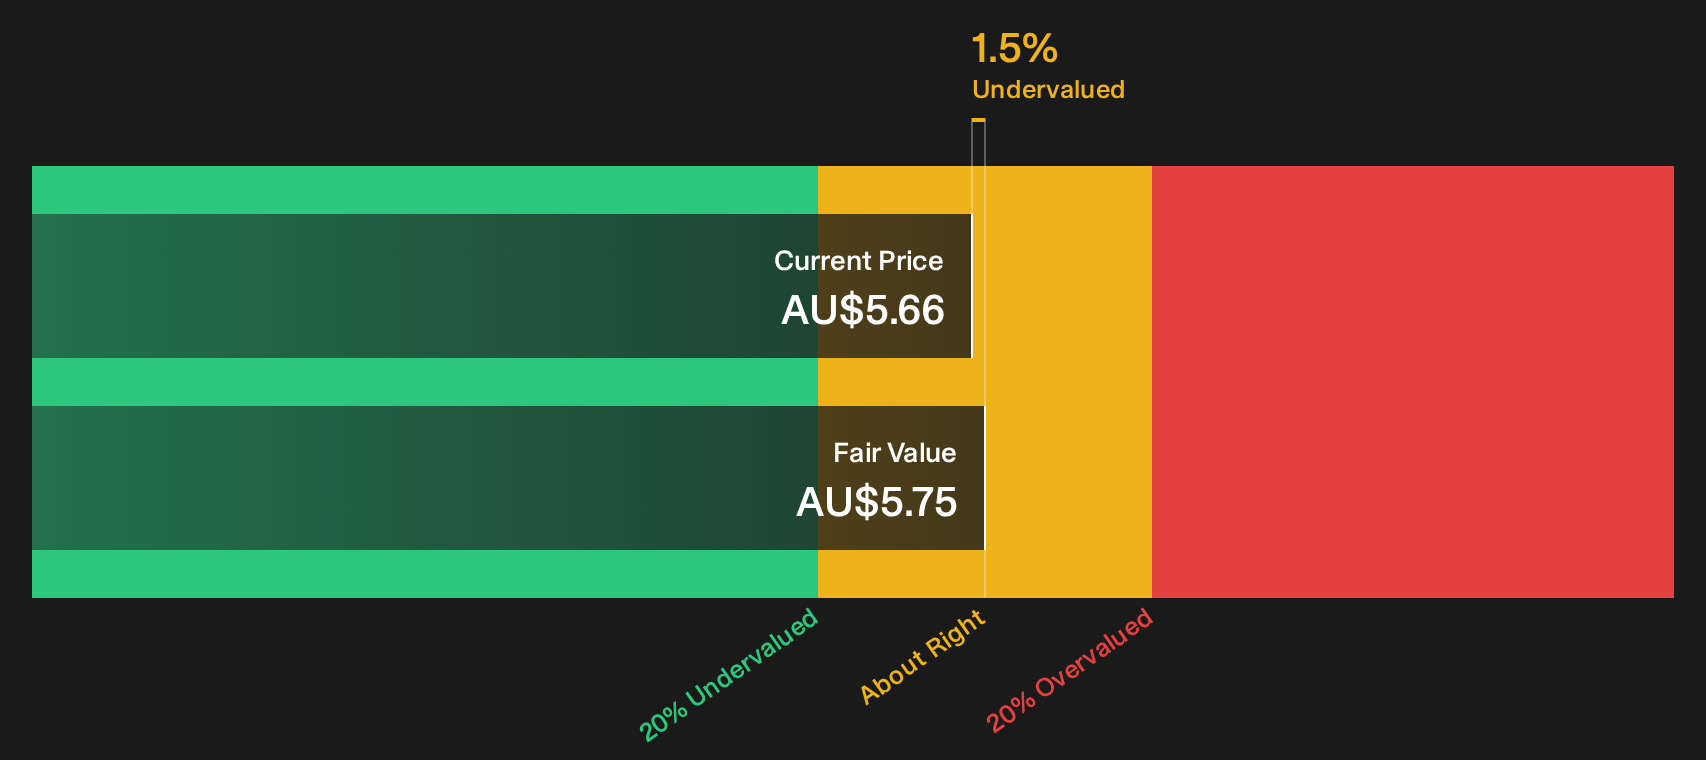
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Yancoal Australia for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 2 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Yancoal Australia so far, or a straightforward setup hiding in plain sight. Act quickly by checking both sides of the story through the 2 key rewards and 2 important warning signs.
Looking for more Yancoal Australia sized ideas?
Do not stop with just one stock. Use the Simply Wall St Screener to quickly surface fresh ideas that match your risk, income, and value preferences.
- Target resilient opportunities by scanning a 6 resilient stocks with low risk scores that aims to keep potential shocks on your radar before they hit your portfolio.
- Seek potential bargains through a 14 high quality undiscovered gems that highlights quality businesses the wider market may not be watching yet.
- Turn consistent income into a core pillar of your plan by reviewing a 5 dividend fortresses built around stronger yield candidates.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com