


EN
Vodafone Outage Might Change The Case For Investing In TPG Telecom (ASX:TPG)
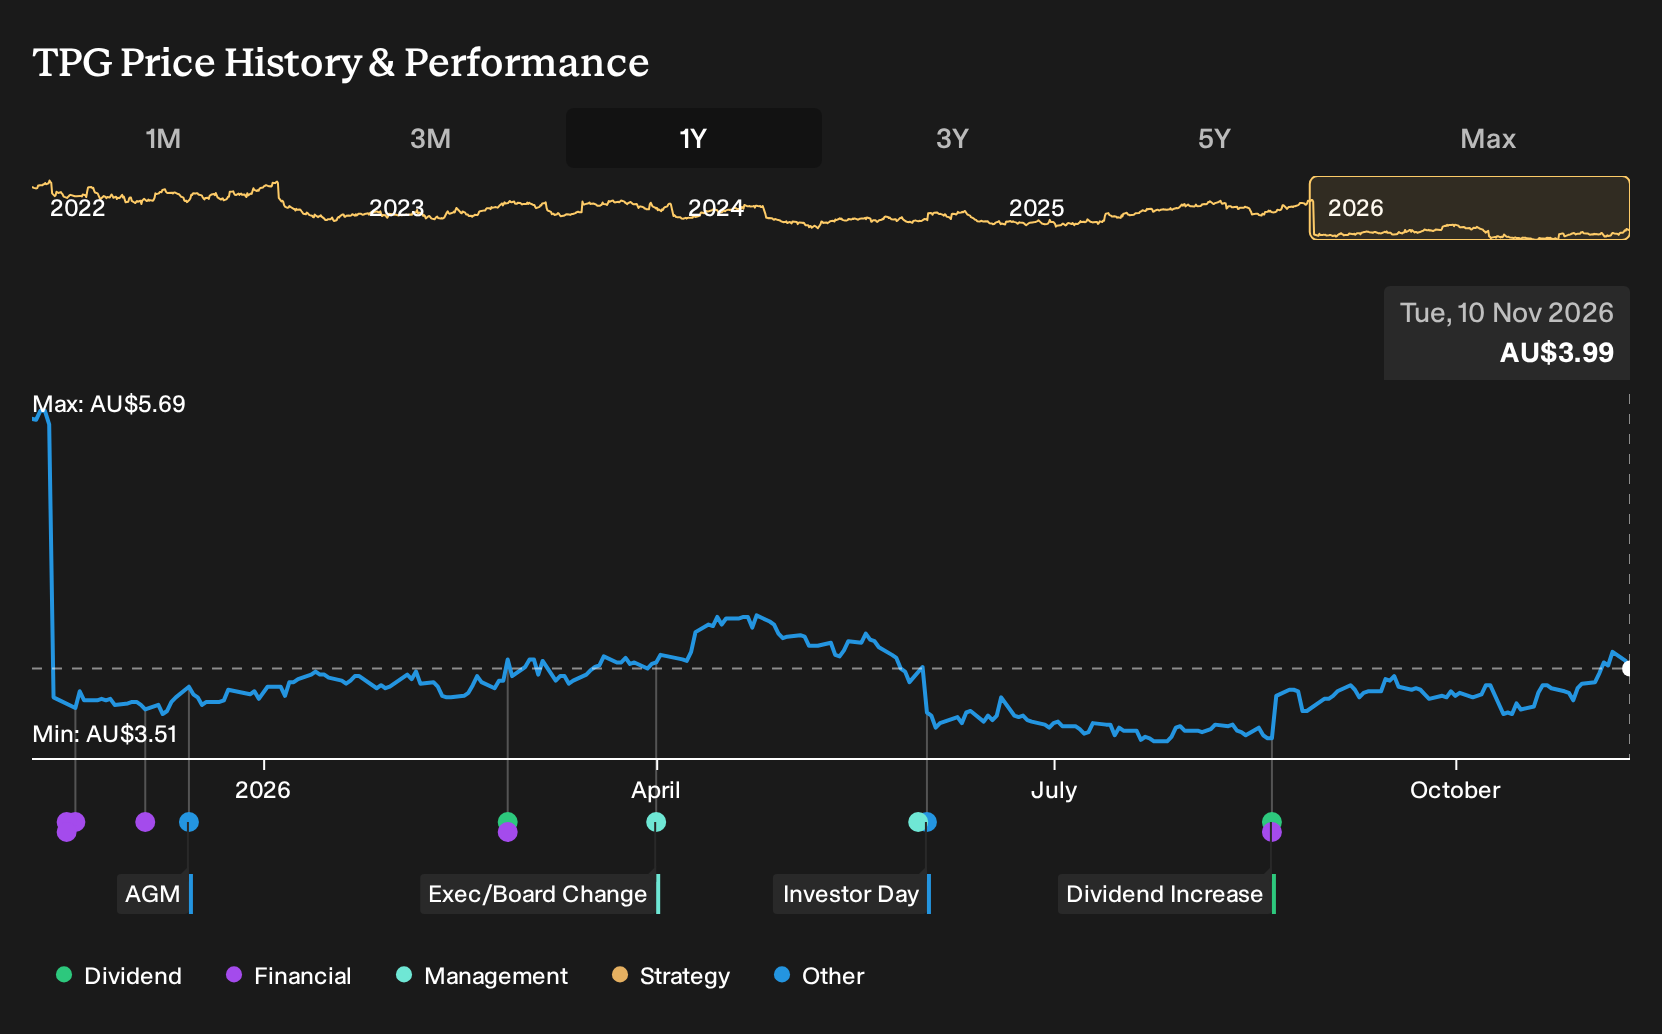
- Vodafone Australia, owned by TPG Telecom, suffered a nationwide mobile disruption in June 2026 after a power failure at a key network hub, disrupting services across major cities and triggering a review of network resilience.
- The outage puts TPG Telecom’s capital light network strategy under the microscope, since any perceived weakness in resilience can influence future investment priorities, regulatory focus and long term customer trust in its mobile brands.
- The next section examines how this network wide Vodafone outage could reshape TPG Telecom's broader investment narrative and risk profile.
TPG Telecom Investment Narrative Recap
To own TPG Telecom, you need to believe the telecom group can turn its capital light network model, digital only brands and broader mobile footprint into steadier earnings and free cash flow over time. The analyst consensus Narrative on Simply Wall St leans on earnings that are forecast to grow 36.47% per year, while revenue growth is expected to run at 3.2% annually.
The key near term swing factor is execution on cost efficiency and service reliability, including how quickly customers regain confidence after recent outages. The biggest immediate risk is that repeated network incidents lift churn and service costs, which could pressure margins and test support for a dividend that is not well covered by current earnings.
Recent outages sit directly beside one of the main red flags already highlighted for TPG Telecom. Analysts have pointed to national and regional Vodafone disruptions as a risk to mobile service revenue and net margins, through weaker trust, higher churn and extra remediation spending. The June 2026 hub failure fits squarely into that concern.
For catalysts, the same network is also where upside is expected to come from. Expanded coverage to 98.5% of the population through network sharing, the shift to app only brands like Felix, and the use of AI to reduce contact volumes all rely on reliable infrastructure. Any operational follow through on resilience upgrades now will matter for how those growth and margin drivers play out.
TPG Telecom's current analyst story points to A$5.5 billion in revenue and A$293.5 million in earnings by 2029, based on 3.2% yearly revenue growth and an earnings increase of about A$238.5 million from A$55.0 million today.
Uncover why TPG Telecom's fair value indicates a 3% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view leans heavily on spectrum renewal costs rather than outages. Those more pessimistic analysts already expected TPG Telecom to reach about A$5.4b of revenue and A$227.6m of earnings by 2029, on only 2.4% annual revenue growth. The June disruption could shift those pre outage assumptions, so consider several viewpoints before forming your own.
Explore 4 other TPG Telecom fair value estimates, including one that suggests there could be as much as 39% downside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your TPG Telecom research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for TPG Telecom. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate TPG Telecom's overall financial health at a glance.
Looking For More Investment Ideas Beyond TPG Telecom?
If the TPG Telecom story has sharpened your thinking on risk, income and balance sheet strength, you can use that same lens to scan a wider field of opportunities with the Simply Wall St Screener.
- For investors who care most about capital protection and steadier profiles, start with a curated 6 resilient stocks with low risk scores that emphasise resilience over excitement.
- If income is your priority, focus on cash flow and payout strength by reviewing a hand picked set of 5 dividend fortresses that put yield and durability front and center.
- To widen your watchlist with potential future leaders, browse a tighter 14 high quality undiscovered gems that combine financial quality with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com